My Investments Update - April 2026

My Investments Update – April 2026

Here is my latest monthly update about my investments. You can read my March 2026 Investments Update here if you like.

I’ll begin as usual with my JP Morgan Personal Investing (previously NutmegStocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

As regular readers will know, in June last year I transferred most of the money in my former Nutmeg Fully Managed portfolio (just under £25,000) to a new Nutmeg Income Portfolio. I discussed this in detail in this post, but basically money in this port is invested to generate an income from share dividends and other sources. This is then paid monthly. Capital appreciation is targeted as well, but these portfolios are aimed primarily at older people (and others) who want/need their investment to generate a regular cash income.

In January my JPM Investing income portfolio generated £75.54 of income, which was duly paid in to my bank account on 24 March 2026. That means I have now received tax-free income of £273.68 in 2026 and a total of £745.14 since I opened the account in June last year. That’s about what I would have expected based on JPM’s projected annual return of just under 5% for income ports at my chosen risk level (five).

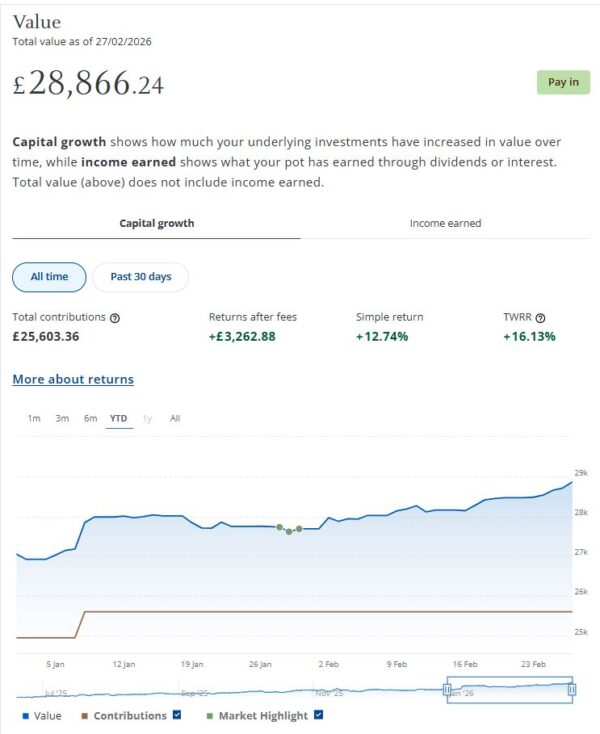
The less good news is that my income portfolio declined in value in March. It’s now worth £27,320 compared with £28,866 at the start of last month, a fall of £1,546. You don’t need to be an investment expert to know that this is mainly due to events in the Middle East. Nearly all of my share-based investments have been affected by this. Clearly it is disappointing, but as I always say, you do have to expect ups and downs when investing. As the screen capture below shows, my income port is still up by a respectable £1,716.97 (6.71%) after fees since I opened it last June.
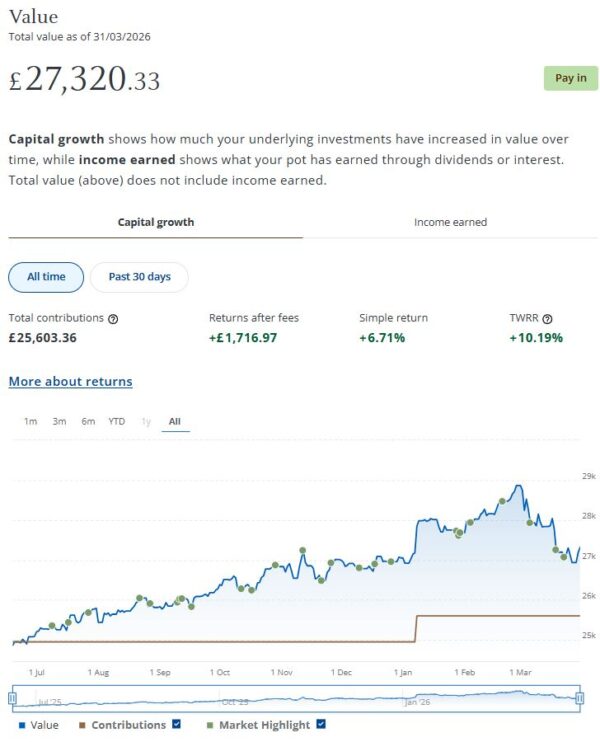
JPM Income Portfolio April 2026

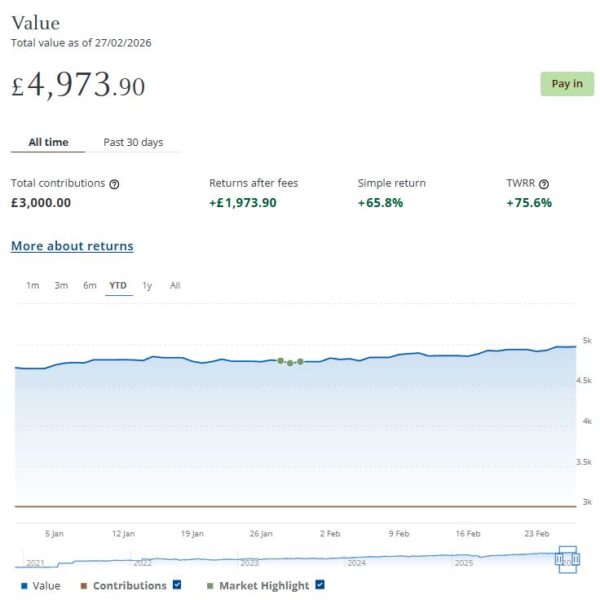
I still have a smaller, growth-oriented pot using JPM Investing’s Smart Alpha option. This is now worth £4,606 compared with £4,974 (rounded up) a month ago, a fall of £368. Here is a screen capture showing performance over the last year.
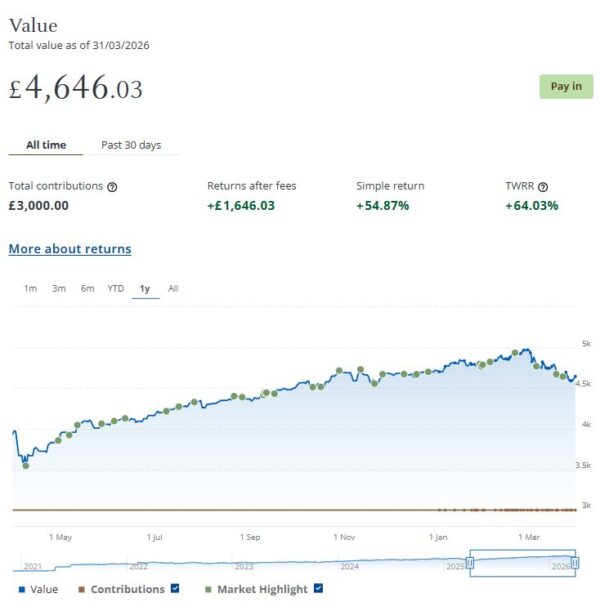
Nutmeg Smart Alpha port April 2026

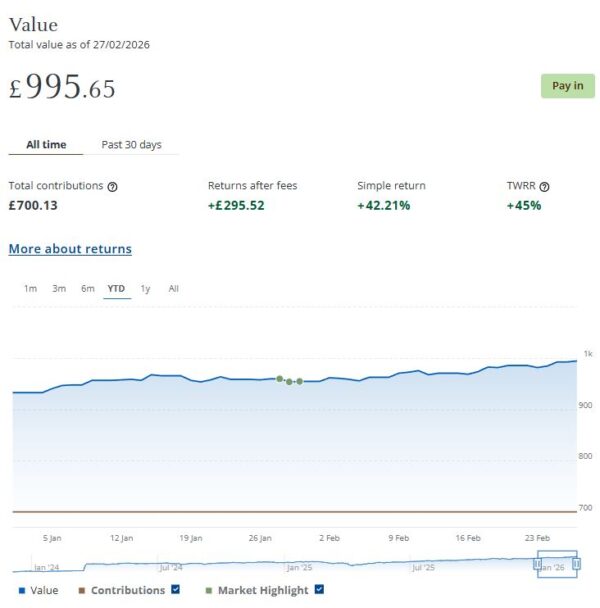
Finally, at the start of December 2023 I invested £500 in one of Nutmeg/JPM’s thematic portfolios (Resource Transformation). In March 2024 I also invested a further £200 from referral bonuses (something I no longer receive). As you can see from the one-year screen capture below, this portfolio is now worth £934 compared with £996 (rounded up) last month, a decrease of £62.
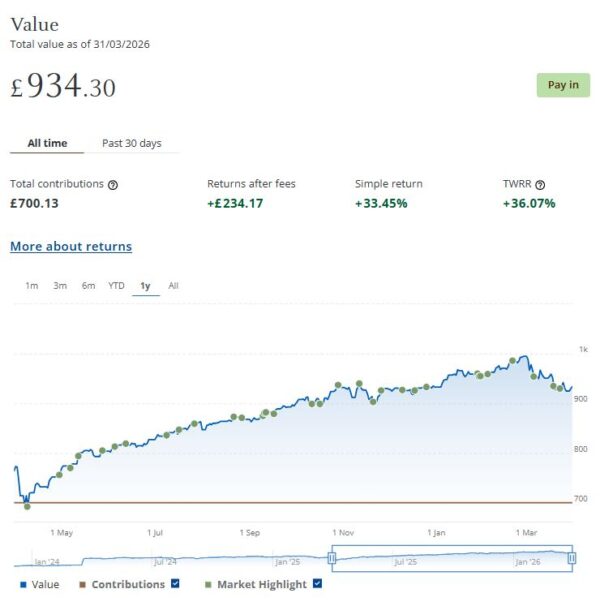
Nutmeg THematic port April 2026

Overall in March the value of my JPM investments fell by £1,976 or 5.55%. Against that I did, of course, receive £75.54 in income from my income portfolio. In total, then, I am £1900.46 down for the month.

On a more positive note, excluding income generated, the overall value of my JPM investments is still up by £3,385 or 11.47% since the start of April 2025. If you add to this figure the £745.14 of income generated by my Income portfolio to date, that gives a total profit for the last 12 months of £4,130.14 – still not a bad return in these uncertain times.

As I said above, some volatility is always to be expected with stock market investments, but in the longer term they tend to even themselves out (and typically outperform bank savings accounts, although that is never guaranteed). In general the worst thing you can do is panic and sell up when downturns occur (as happened last month). You are then crystallizing your losses rather than giving the markets time to recover. This is something I discussed last year in this blog post. Obviously nobody knows what will happen in the Middle East, but hopefully some sort of resolution will occur soon, if only because President Trump desperately needs an exit strategy to pacify his critics back home. Once a bit more stability returns to the region, we will hopefully see world stock markets rise again. Though of course there is no guarantee about this.

You can read my full original Nutmeg/JPM review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last nine years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Housemartin. As discussed in this post, the company rebranded last year from Assetz Exchange.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £309.64 in revenue from rental income. I have made a small net loss of £20.25 on property disposals. Capital growth generally has slowed, in line with UK property values generally.

At the time of writing, 17 of ‘my’ properties are showing gains, 3 are breaking even, and the remaining 24 are showing losses. My portfolio of 44 properties is currently showing a net decrease in value of £76.05. That means that overall (rental income minus capital value decrease and loss on disposal) I am up by £213.34. That’s still a respectable return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

  • A further consideration is that property investments on Housemartin are less likely to be affected by stock market downturns, as happened in March due to the war in the Middle East. This again demonstrates the potential value of such investments for diversifying your portfolio during challenging times.

The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I usually reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my original review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].

In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

In January this year, as Oil Worldwide hadn’t exactly been setting the world alight, I decided to switch my entire investment in this to another smart portfolio, InTheGame. This port, focusing on the computer gaming industry, has been the top performer for some time in my eToro virtual portfolio.

Unfortunately just as I switched away from Oil Worldwide, President Trump decided to invade Venezuela. This gave the oil industry a significant boost, which I would otherwise have benefited from. Meanwhile InTheGame has gone south, partly due to the recent fall in AI stocks along with the war in the Middle East. At the time of writing the value of my investment in this has fallen by nearly 17%. Hey ho! This does of course demonstrate that there are never any guarantees when investing and unexpected events can thwart the best-laid plans…

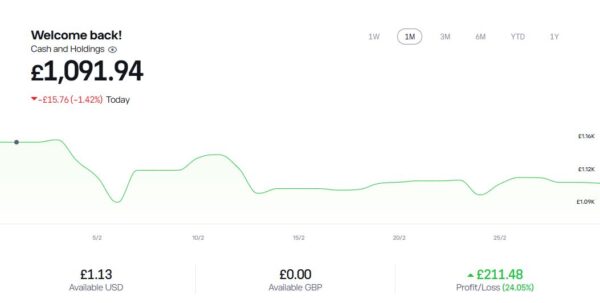
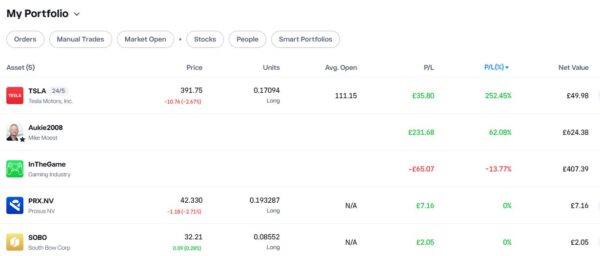
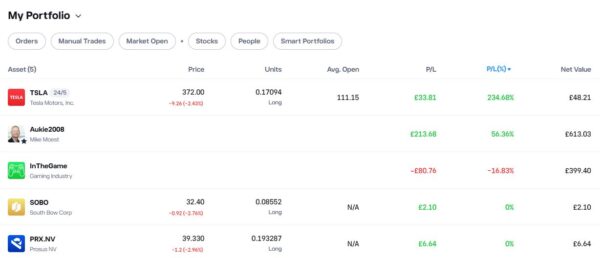
As you can see from the screen captures below, my original eToro investment (total value £888.36 in pounds sterling) is today worth £1,070.78, an overall increase of £182.42 or 20.53%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.
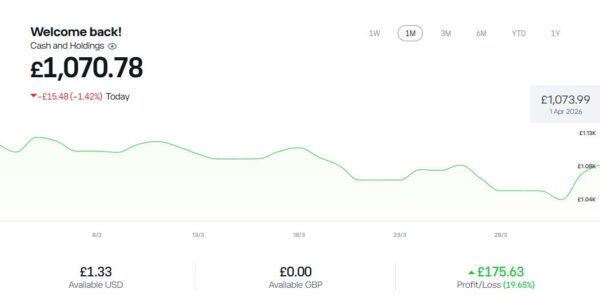
Etoro Home April 2026

Etoro port April 26

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this post.

As mentioned above, my new investment in InTheGame is currently down by nearly 17%. My copy trading investment with Aukie2008 also fell in value in March, but it’s still showing an impressive overall profit of 56.36%. Of course, I have held this investment for quite a bit longer.

My Tesla shares, which I purchased as an afterthought with some spare cash I had in my account, are also down this month, but still showing an overall profit of over 234% since I bought them. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio.

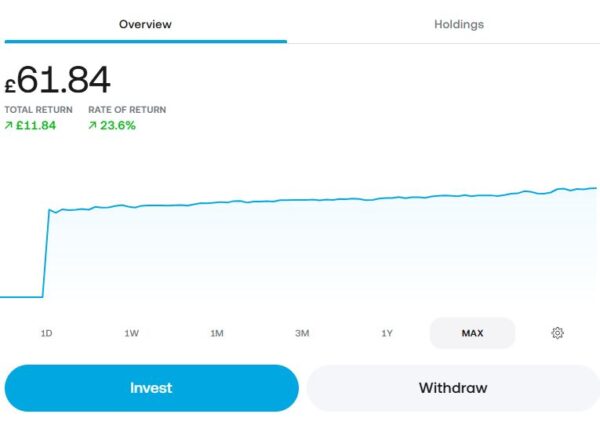
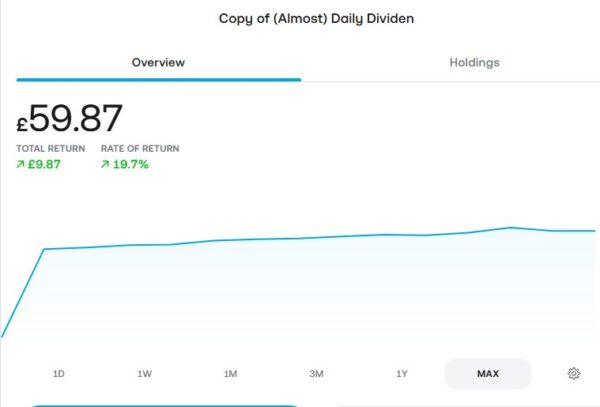
As an experiment, at the start of April last year I put £50 into an investment ISA with Trading 212. As mentioned in my blog post about dividend investing, I put it into the (Almost) Daily Dividends Portfolio, a ready-made portfolio or ‘pie’ on Trading 212. As you can see from the screen capture below, my portfolio is now worth £59.87. That’s a decrease of £1.97 since last month but an increase of £9.87 or 19.7% over the eleven-month period since I opened it. It has even accrued a grand total of £1.08 in dividends, most of which has now been (automatically) reinvested.
Trading 212 Dividends ISA April 26

I am quite impressed with how this investment has been faring, despite the small amount I put in (which means I may be missing out on some smaller dividends). If I increased my investment I would almost certainly become eligible for more dividends, and even more the longer I remain invested. If I had any spare money at the moment, I would consider doing this. Of course, I do now have an income-focused portfolio with JPM Investing as well (see above).


Moving on, I published various posts on Pounds and Sense in March. I have listed below those that are still relevant.

In Beat the Postage Stamp Price Rise, I pointed out that the cost of stamps is rising (again) on Tuesday 7 April 2026. That will be the SEVENTH rise in the price of first class stamps in just four years! Standard and large-letter stamps don’t have values printed on them and will still be valid after the April price rise comes in, so my top tip is to stock up now while stamps are still at the old price.

I also posted an updated version of Get a Free Share Worth up to £100 with Trading 212. Anyone who hasn’t done this before can get a free share worth up to £100 just by signing up for a new Trading 212 investment account via my link. The current offer closes on Tuesday 28th April 2026.

Also in March I published Are River Cruises Suitable for Solo Travellers. This was a follow-up to my earlier posts about how to save money on cruise holidays and the pros and cons of river cruises (for older travellers in particular). In this post I addressed a question asked by several readers as to whether river cruises are a good choice for solo travellers. The article sets out the pros and cons as I see them. My view, as expressed in the article, is that they can be, but it does depend on your travel style and budget.

What Is An Annuity – And Who Should Consider Buying One? discusses a subject that confuses many people. In simple terms, an annuity is a financial product that converts a lump sum of money – typically from your pension pot – into a guaranteed regular income for life (or for a fixed period). You buy an annuity from an insurance company. In return for handing over some or all of your pension savings, they promise to pay you a regular income, usually monthly, for the rest of your life. In the article I look at the pros and cons of annuities, and whom they are (and aren’t) likely to be suitable for.

How to Save Money on Travel Insurance covers a subject on many people’s minds at this time of year. Travel insurance is one of those expenses that can feel like a grudge purchase – until you need it. For UK travellers, especially older holidaymakers, having adequate cover is essential. In this article I set out some ways you may be able to save on travel insurance without compromising your safety or security. I also discuss saving money on travel insurance as an older person, and the issues that can be caused by war and civil unrest (especially relevant for destinations in or near the Middle East at the moment).

Finally, in March I published Don’t Miss Out – Use Your £20,000 ISA Allowance Before It’s Too Late! As I say in the article, the end of the tax year on 5 April 2026 is fast approaching and so is the deadline to utilize the annual tax-free Individual Savings Account (ISA) allowance. Unless you take action in the next few days, this opportunity to maximize your tax-free savings for the 2025/26 financial year will be gone for ever.

  • And speaking of deadlines, time is also running out to take advantage of EDF Energy‘s enhanced switching offer. Until 6 April 2026 you can get a FREE £75 (increased from £50) credited to your energy account when you switch to EDF via my link at https://edfenergy.com/quote/refer-a-friend/sunny-koala-9462. Terms and conditions apply.

I’ll close with my customary reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as it is now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out!

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. Twitter/X remains my primary social media platform, but I also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!

If you enjoyed this post, please link to it on your own blog or social media:
How to Save Money on Travel Insurance

How to Save Money on Travel Insurance

As we reach the end of a long, cold winter, many people’s thoughts are turning to holidays. And that makes the topic of travel insurance a lot more relevant – in these uncertain times especially.

Travel insurance is one of those expenses that can feel like a grudge purchase – until you need it. For UK travellers, especially older holidaymakers, having adequate cover is essential. The good news is that there are plenty of ways to keep costs down without cutting corners on protection.

Here are some practical strategies to help you save money on travel insurance while still getting the cover you need.

Money Saving Strategies

1. Shop Around and Compare Policies

Prices can vary significantly between insurers for broadly similar cover. Using comparison sites such as Compare the Market, MoneySuperMarket, and GoCompare can quickly highlight the best-value options.

However, don’t rely solely on comparison sites. It’s also worth checking insurers directly, including Aviva and Staysure, as they sometimes offer exclusive deals.

2. Consider an Annual Multi-Trip Policy

If you take more than one trip a year, an annual (multi-trip) policy can be far cheaper than buying single-trip cover each time.

As a rough guide:

  • Two or three holidays a year can make an annual policy worthwhile
  • Frequent travellers can save substantially over time

Just ensure the policy covers the length of your longest trip, as many impose limits (e.g. 31 or 45 days per trip).

3. Only Pay for the Cover You Need

Policies often include extras that you may not require. Common add-ons include:

  • Gadget cover
  • Winter sports cover
  • Cruise cover

If these aren’t relevant, opt out. For example, if you’re taking a simple European city break, you likely don’t need winter sports or high-value gadget protection.

4. Check Existing Cover First

You may already have some level of travel insurance included with:

  • Packaged bank accounts
  • Credit cards
  • Membership organisations

For instance, some premium current accounts from Nationwide Building Society or HSBC include travel insurance as a perk.

That said, always read the small print carefully – cover levels, age limits, and exclusions may apply.

5. Increase the Excess (Carefully)

Choosing a higher excess (the amount you pay towards a claim) can reduce your premium.

For example:

  • £50 excess → higher premium
  • £150 excess → lower premium

This can be a sensible way to save money if you’re unlikely to make small claims. However, ensure the excess remains affordable if you do need to claim.

6. Be Honest About Medical Conditions

Failing to declare pre-existing medical conditions can invalidate your policy entirely.

Specialist insurers like AllClear Travel Insurance and Saga cater specifically to older travellers and those with medical histories.

While premiums may be higher, proper disclosure ensures you are fully covered – potentially saving thousands if something goes wrong.

7. Use the GHIC Card

UK residents can apply for a Global Health Insurance Card (GHIC), which provides access to state healthcare in EU countries and some others at reduced cost or sometimes free.

This won’t replace travel insurance, but it can reduce the level of medical cover you need – and may lower your premium slightly.

8. Travel Less Often? Consider Single-Trip Cover

If you only travel once a year, a single-trip policy is usually cheaper than an annual one.

You can also tailor it closely to your itinerary, ensuring you don’t pay for unnecessary cover.

9. Book Early – but Not Too Early

Buying insurance as soon as you book your trip is usually best. This ensures you’re covered for cancellation from day one.

However, prices can fluctuate, so it’s worth checking a few providers before committing rather than simply accepting the first quote offered.

10. Look for Discounts and Cashback

Before purchasing, check for:

  • Cashback offers via sites like TopCashback
  • Voucher codes
  • Discounts for couples or families

Even modest savings of £10–£20 can add up over time.

Saving as an Older Traveller

Travel insurance tends to become more expensive as you get older, but there are still ways to keep costs under control without sacrificing essential cover.

One of the main issues older travellers face is higher premiums due to increased medical risk. Insurers often apply age bands, and prices can rise quite sharply once you reach your late 60s or 70s. In addition, pre-existing medical conditions – more common in later life – can further increase the cost or limit the number of insurers willing to provide cover.

Some mainstream providers also impose upper age limits, particularly on annual policies, which can restrict your options. This is where specialist insurers such as Saga and Staysure can be especially valuable, as they are geared towards older customers and often have no upper age limit.

To manage costs, it’s worth considering the following approaches:

  • Compare specialist providers: Companies focusing on older travellers may offer better value than standard insurers.
  • Tailor your cover carefully: Avoid unnecessary add-ons, but don’t skimp on medical cover, which is the most important element.
  • Consider single-trip policies: These can sometimes work out cheaper than annual cover for older travellers, particularly if you only take one holiday a year.
  • Get medical screening right: Providing accurate and detailed information can help avoid inflated premiums and ensures valid cover.
  • Travel within Europe where possible: Premiums are typically lower than for worldwide cover, especially when combined with a Global Health Insurance Card (GHIC).

While costs may be higher, careful shopping around and using specialist providers can make travel insurance much more affordable in retirement – allowing you to travel with confidence and peace of mind.

Travel Insurance and Wars

The ongoing conflict in parts of the Middle East is a reminder that global events can have a direct impact on your travel insurance – sometimes in ways that aren’t immediately obvious.

One key point is that most standard travel insurance policies exclude claims arising from war, military action or civil unrest. This means that disruption caused directly by the conflict – such as flight cancellations, airspace closures, or evacuations – may not be covered.

In addition, insurers often treat major conflicts as a “known event” once they are widely reported. If you buy a policy after this point, it’s unlikely to cover any claims related to that situation.

Another crucial issue is official government advice. The UK Foreign, Commonwealth & Development Office (FCDO) regularly updates its guidance for travellers. If it advises against travel to a destination (or all but essential travel), your insurance may be invalidated if you still choose to go.

Where plans are already in place, cover may depend on timing and policy wording. Some insurers will allow cancellation claims if FCDO advice changes after you have booked, but this is not guaranteed and varies between providers. Read your policy wording carefully, especially exclusions relating to war and unrest, and contact your insurer directly if travelling anywhere near affected regions.

The overall message is clear: if you are considering travel to, or even near, areas affected by conflict, proceed with caution. Insurance protection may be limited, and official advice should be taken seriously – not just for financial reasons, but for your personal safety as well.

Final Thoughts

Saving money on travel insurance isn’t about choosing the cheapest policy – it’s about finding the best value for your circumstances. For older travellers in particular, ensuring adequate medical cover should always be the priority.

By comparing providers, tailoring your cover, and making use of existing benefits, you can often reduce costs significantly without compromising on safety or protection.

As always, if you have any comments or questions about this post, please do leave them below. I am always delighted to hear from PAS readers.


If you enjoyed this post, please link to it on your own blog or social media:
Use Your Tax-Free ISA Allowance Before It's Too Late!

Don’t Miss Out! Use Your £20,000 ISA Allowance Before It’s Too Late

As the end of the tax year on 5 April 2026 approaches, so too does the deadline to utilize the annual tax-free Individual Savings Account (ISA) allowance.

The clock is ticking, and unless you take action in the next few weeks, this opportunity to maximize your tax-free savings for the 2025/26 financial year will be gone.

ISAs are a popular choice for savers and investors alike, offering a tax-efficient way to grow your wealth. With a diverse range of options available, from cash ISAs to stocks and shares ISAs and innovative finance ISAs, individuals have the flexibility to tailor their savings strategy to suit their financial goals and risk appetite.

The current ISA allowance stands at £20,000, providing a significant opportunity to shield your savings and investments from tax. This allowance represents a generous sum that, if left unused, cannot be carried forward to future years. In essence, any portion of the £20,000 allowance that remains untapped by the upcoming deadline will be lost, representing a missed opportunity for tax-free growth.

For those who have yet to fully utilize their annual ISA allowance, now is the time to take action. Whether you’re looking to bolster your rainy-day fund with a cash ISA, seeking to invest in the stock market through a stocks and shares ISA, or diversify your investment portfolio with an IFISA, there’s no shortage of options available.

Cash ISAs offer a secure and accessible way to save, providing a tax-free environment for your savings with the added benefit of easy access to your funds when needed. Meanwhile, stocks and shares ISAs open the door to potentially higher returns by investing in a wide range of assets such as equities, bonds and funds, albeit with a higher level of risk. And an Innovative Finance ISA, or IFISA for short, allows you to invest via P2P/crowdfunding platforms, further diversifying your portfolio (though again with a higher level of risk).

With an ISA you will never incur any liability for dividend tax, capital gains tax or income tax, even if your investments perform exceptionally well. Of course, there is no guarantee this will happen, but over a longer period stock market investments have typically outperformed cash savings, often by a substantial margin.

In recent years I have invested much of my own annual ISA allowance in a stocks and shares ISA with JP Morgan Personal Investing (formerly Nutmeg). I have also invested some money in a property IFISA from Housemartin (previously Assetz Exchange). Check out the Housemartin website here [affiliate link].

You can also read my March 2026 Investments Update to see how my JPM and Housemartin investments (and others) have been faring recently.

Finally, for shorter-term savings, I am using the Trading 212 Cash ISA. This currently pays me an interest rate of 3.60% AER. Higher rates are typically on offer to new Trading 212 clients for their first 12 months.

  • Note that from April 2027 the Cash ISA allowance has been reduced from £20,000 to £12,000 per year for savers under the age of 65. Until then it remains at £20,000 a year for all savers, though. 

With just a few weeks left to take advantage of this valuable tax benefit, delaying now could prove costly. By acting swiftly you can ensure that your savings and investments are positioned to grow tax-free, setting yourself up for a better financial future.

In summary, the £20,000 annual ISA allowance for the 2025/26 tax year presents a golden opportunity to maximize your tax-free savings and investments. Time is of the essence, though. Unless you act before the looming deadline of 5th April 2026, this valuable allowance will be lost forever. If you have the money available, therefore, seize the opportunity now to help secure your financial future.

As always, if you have any comments or questions about this article, please feel free to leave them below.

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss.


If you enjoyed this post, please link to it on your own blog or social media:
What is an Annuity - And Who Should Consider Buying One?

What Is an Annuity – and Who Should Consider Buying One?

If you’re approaching retirement (or have retired already), you’ve probably come across the term annuity. For some people it represents security and peace of mind. For others it feels restrictive and poor value.

So what exactly is an annuity – and who should consider buying one?

Let’s take a closer look.

What Is an Annuity?

In simple terms, an annuity is a financial product that converts a lump sum of money – typically from your pension pot – into a guaranteed regular income for life or for a fixed period.

You buy an annuity from an insurance company. In return for handing over some or all of your pension savings, they promise to pay you a regular income, usually monthly, for the rest of your life.

This is most commonly done using funds built up in a defined contribution pension such as a personal pension or SIPP.

In the UK, buying an annuity used to be the default retirement option before the pension freedoms introduced by the Pension Schemes Act 2015. Today, it’s just one option among several.

How Does an Annuity Work?

Here’s a simple example:

  • You retire at 67.

  • You have £100,000 in your pension.

  • You use that £100,000 to buy an annuity.

  • The insurance company pays you, say, £6,000 a year for life.

The exact amount you receive depends on:

  • Your age

  • Your health

  • Current interest rates

  • Whether the income rises with inflation

  • Whether it continues to a spouse after your death

Once purchased, most annuities cannot be changed or cancelled. That’s a crucial point. You’re effectively swapping flexibility for certainty.

Different Types of Annuity

There isn’t just one type. The main options include:

1. Lifetime Annuity

Pays you a guaranteed income for the rest of your life, no matter how long you live.

2. Fixed-Term Annuity

Pays income for a set number of years (e.g. 5 or 10).

3. Level Annuity

Pays the same income every year. Starts higher, but inflation erodes its value over time.

4. Inflation-Linked Annuity

Income rises each year, often in line with inflation. Starts lower but protects purchasing power.

5. Joint-Life Annuity

Continues paying income to a spouse or partner after your death.

6. Enhanced Annuity

If you have certain medical conditions or lifestyle factors (e.g. smoking), insurers may offer a higher income because of reduced life expectancy.

👍 The Advantages of Buying an Annuity

1. Guaranteed Income for Life

You cannot outlive your money. This removes longevity risk entirely.

2. Simplicity

Once set up, there’s nothing to manage. No investment decisions. No worrying about stock market falls.

3. Peace of Mind

For many retirees, knowing the bills are covered every month is invaluable.

👎 The Disadvantages

1. Irreversible Decision

Once you buy most annuities, you can’t change your mind.

2. Inflation Risk

A level annuity can lose real value over time.

3. Potentially Poor Value If You Die Early

If you die shortly after purchase (and haven’t chosen guarantees or joint-life options), the insurer keeps the remaining capital.

4. Less Flexibility

You lose access to your capital.

How Do Annuities Compare With Drawdown?

Since pension freedoms were introduced, many retirees instead choose flexible-access drawdown, keeping their money invested and withdrawing income as needed.

Drawdown offers:

  • Flexibility

  • Potential for investment growth

  • Ability to pass on unused funds

But it also carries:

  • Investment risk

  • The possibility of running out of money

  • Ongoing management and decision-making

An annuity, by contrast, provides certainty but little flexibility. Of course, there is nothing to stop you dividing your pension pot between both. You can also start off using drawdown and switch some or all of your pot to an annuity later, e.g once you reach your mid-70s.

👍 Who Should Consider Buying an Annuity?

An annuity isn’t right for everyone. But it may be suitable if:

You Want Certainty

If you value guaranteed income over flexibility, an annuity may suit you.

You Don’t Want Investment Risk

If market ups and downs worry you, locking in income could help you sleep better at night.

You Have No Other Guaranteed Income

If you don’t have a defined benefit (final salary) pension, an annuity can provide similar security.

You’re in Poor Health

An enhanced annuity may offer an attractive income rate.

You Want to Cover Essential Expenses

Some retirees use part of their pension to buy an annuity that covers core bills, leaving the rest invested for flexibility.

👎 Who Might Not Benefit?

You may want to think carefully if:

You have a strong desire to leave a financial legacy

You are comfortable managing investments

You have significant other guaranteed income already

You are relatively young and rates are less attractive

One Important Tip: Shop Around

You are not obliged to buy an annuity from your existing pension provider.

Using the “open market option” can significantly increase your income. Different insurers offer different rates, and enhanced terms are not always automatically applied.

This is one area where independent financial advice can genuinely add value.

How Much Income Could a £100,000 Annuity Buy You?

Example: 70-Year-Old Single Man (Standard Lifetime Annuity)

Annuity Type (Single Life) Estimated Annual Income from £100,000
Level (fixed each year) ~£8,400 per year (≈ £700/month)
Level (best-buys from comparison sites) ~£8,000–£8,500+ per year
Escalating (income grows ~3% annually) ~£6,400 in first year
Inflation-linked (RPI) ~£6,200 in first year

These are rough current illustrations – if you lock in a level annuity at age 70 with £100,000, you might expect around £8,000–£8,500 a year before tax as a starting point.

How Income Varies with Age

Age has a big impact because providers expect to pay income for fewer years the older you are:

Age When Purchased Typical Annual Income (£100,000)
60 years ~£6,500–£7,000
65 years ~£7,300–£7,600
70 years ~£8,000–£8,400
75 years ~£9,000+

What This Means in Practice

Let’s put those figures into context:

  • If a 70-year-old buys a level lifetime annuity with £100,000, a payout of around £8,000 annually equates to about £667 per month before tax.

  • Choosing escalation or inflation protection reduces the initial income but helps protect your spending power over time. For example, a rising income might start at ~£6,400 (with 3% annual increases).

  • These examples are illustrative only – actual quotes vary by provider, postcode, health and product features. For a more precise quote, try an online calculator such as this independent one on the MoneyHelper website.

💡 Tip: Enhanced annuity rates may be higher if you have certain health conditions or lifestyle factors – always compare quotes across the market rather than accepting the first offer.

Quick Takeaways

  • Older age = higher annuity income for the same pension pot.

  • If you have health issues and/or an “unhealthy” lifestyle, you may get a better rate.

  • Level income gives the highest starting payout but won’t keep pace with inflation.

  • Inflation-linked or escalating options reduce initial income in exchange for rising payments.

  • Shopping around is crucial – you don’t have to buy from your existing pension provider.

Final Thoughts

Annuities fell out of favour after pension freedoms were introduced, but rising interest rates in recent years have made them more competitive again.

They aren’t exciting. They aren’t flexible. But for the right person, at the right time in their life, they can provide something that’s hard to put a price on: certainty.

As always with retirement planning, the best solution may not be either/or. A blended approach – part annuity, part drawdown – can often provide the best of both worlds.

If you’re approaching retirement (or there already), it’s well worth understanding how annuities work before ruling them out entirely.

As always, if you have any comments or questions about this article, please do post them below. But note that I am not a qualified financial adviser and cannot give personalized advice. You should always do your own “due diligence” before making investment decisions and seek professional advice if in any doubt how best to proceed. Personally I strongly recommend getting independent professional advice and assistance before purchasing an annuity.


If you enjoyed this post, please link to it on your own blog or social media:
Are River Cruises Suitable for Solo Travellers

Are River Cruises Suitable for Solo Travellers?

My recent posts about cruise holidays and river cruises have generated quite a bit of interest among PAS readers. One asked if I could say something about the suitability of river cruises for solo travellers. I thought that was an interesting question (and one that’s relevant to me personally). So today I shall be addressing this particular topic.

River cruising has traditionally been seen as a holiday for couples or groups. But in recent years, more solo travellers – especially active retirees and budget-conscious explorers – have been asking if it’s a good fit for them too. The short answer to this is Yes – but with some important things to consider before you book.

Let’s take a look at the pros and cons…

👍 Pros of River Cruises for Solo Travellers

1. Built-In Social Opportunities

With smaller ships and communal activities like guided excursions, happy hours and shared dining, solo travellers often find it easy to strike up conversations. If you’re someone who enjoys meeting new people, river cruises can be surprisingly good in this respect.

2. Guided Excursions Take Out the Guesswork

Instead of navigating a new city on your own, excursions included in many packages let you explore in a group — perfect if you want cultural immersion without logistical stress.

3. Special Solo Cabins Are Growing

More cruise lines are introducing single-occupancy cabins (or reduced single supplements) to prevent solo travellers paying double the fare for a standard cabin. This makes solo travel more financially appealing.

4. Safety and Ease

Especially for older solo travellers, river cruising provides an added layer of comfort and security:

  • Onboard support staff.

  • Port stops often right in town centres – no long transfers.

  • Lectures, entertainment and shared experiences that make connecting with others easier.

👎 Cons of River Cruises for Solo Travellers

1. Single Supplements Can Be Pricey

Even with growing options for solo cabins, many river cruise packages still charge a single supplement — a surcharge for solo travellers that can significantly increase the overall cost. Always compare total price (not just headline fare).

2. Smaller Ships Mean Fewer People

If you’re a social butterfly craving variety in company, the smaller onboard population might feel a bit limited. Some people thrive on that atmosphere; others miss larger group dynamics. If there are some fellow passengers you really don’t like, on a river cruise it may be harder to avoid them.

3. Some Shore Excursions May Require Good Mobility

While many tours are gentle, some exploring old towns can involve walking on uneven cobblestones. Plan ahead if you have mobility concerns.

💡 Money-Saving Tips for Solo Cruisers

If you decide a river cruise is your kind of holiday, here’s how to make it better value…

1. Seek Out Reduced (or Zero) Single Supplements

Some operators – especially those targeting UK solo travellers – offer promotional periods with no single supplement on selected departures. Check specialist sites like RiverCruising.co.uk or GlobalRiverCruising.co.uk regularly and sign up to any email newsletters they offer.

2. Book Early

New solo cabins and low-supplement departures often sell out quickly. Booking up to a year in advance can secure better rates.

3. Compare Inclusions Carefully

A lower headline price isn’t always better. Packages that include drinks, excursions and transfers may cost more upfront but save you money overall.

4. Consider Shared Shore Excursions

If mobility isn’t an issue and you’re comfortable exploring with others, opting for group excursions rather than private tours may save money.

5. Travel Outside Peak Dates

Shoulder seasons – spring and autumn – usually come with lower prices and fewer crowds, giving you a more relaxed experience at a better price point.

6. Check for dedicated solo departures

Some operators like Riviera River Cruises occasionally run solo-only cruises with no supplement – ideal for meeting other solo voyagers.

7. Compare direct vs agent pricing

Sometimes booking directly with the cruise line is cheaper; other times a specialist agent will have better exclusive rates.

8. Fly from Regional Airports

River cruise packages often include flights. Compare prices from regional UK airports – you may find cheaper deals than London departures.

9. Use Loyalty Programmes & Travel Agents

Cruise line loyalty programmes can bring discounts, upgrades or onboard credits. Specialist cruise agents often know about promotions that aren’t publicised online.

🛳️ River Cruise Operators Friendly to Solo Travellers

1. AmaWaterways – Offers a range of solo traveler specials, including reduced single supplements (as low as 10% on select sailings) and even waived single supplement on specific ships with dedicated single occupancy cabins. It’s one of the more flexible mainstream lines for solo travellers in Europe.

2. Riviera River Cruises – This UK-focused operator has expanded its solo traveller options by eliminating the single supplement on a number of European river cruise departures (especially on the Rhine and Rhone). These sailings often have multiple cabins available with no supplement for solo bookings.

3. Avalon Waterways – Known for no single supplement on selected departures, Avalon runs dedicated sailings where solo travellers pay just the standard fare with no extra charge. These promotions are seasonal and vary by departure date and cabin category.

4. Tauck – Offers no single supplement in its lowest category cabins on European river cruises, making it a strong choice for solo travellers looking for a fully guided and inclusive experience without hefty extras.

5. Uniworld Boutique River Cruises – Frequently runs reduced or waived single supplement offers on selected sailings and cabin grades, appealing to solo travellers who want a boutique, luxury river experience.

6. Scenic – Provides significant single supplement discounts — on some sailings up to 75% off the usual extra charge — which can make luxury river cruising much more affordable for those travelling alone.

7. Emerald Cruises – Often offers solo-friendly specials including waived single supplements on select itineraries and dedicated single cabins. This gives solo cruisers the chance to book at twin-share prices for certain departures.

8. CroisiEurope – Another line regularly mentioned in travel roundups for offering single occupancy cabins or reduced single supplements on selected routes, helping solo travellers avoid paying double fares on all departures.

🧠 Final Verdict: Is River Cruising Good for Solo Travellers?

Yes – but it depends on your travel style and budget.

  • If you enjoy engaging with fellow travellers, appreciate guided experiences, and want a secure, stress-free way to see multiple destinations, river cruising can be a fantastic solo holiday.

  • Just be mindful of pricing structures like single supplements and cabin availability – and do your homework before booking.

For many UK solo travellers, the combination of cultural discovery, social opportunities and value-focused packages makes river cruising a very attractive option.

As always, if you have any comments or questions about this article, please do leave them below. And if you’ve been on a river cruise yourself (solo or otherwise), I’d love to hear what you thought and if you have any other tips for making the most of them.


If you enjoyed this post, please link to it on your own blog or social media:
Beat the Postage Stamp Price Rise

Beat the Postage Stamp Price Rise!

A quickie today to let you know that the price of stamps is rising again on Tuesday 7 April 2026. That will be the SEVENTH rise in the price of first class stamps in just four years.

On this occasion a standard first class stamp is going up from £1.70 to £1.80, a 6% increase. The price of sending a large letter first class is going up from £3.15 to £3.30, a 5% increase.

The price of sending a standard letter by second class post is increasing from 87p to 91p (a 5% rise), One small bit of good news is that the cost of sending a large letter second class is not rising and remains at £1.55.

Standard letters can weigh up to 100g and measure a maximum of 24cm x 16.5cm x 5mm. Large letters can measure 35.3cm x 25cm x 2.5cm but still have to weigh under 100g. If they weight over 100g, higher rates apply, and if they weigh over 750g they have to go at parcel rates.

The cost of many of Royal Mail’s ‘Signed For’, ‘Special Delivery Guaranteed’ and ‘Tracked’ services will also rise from 7 April, as will the price of sending parcels first and second class. You can see a full list of prices by clicking here.

Saving Money on Stamps

So is there anything you can do to mitigate the impact of the latest price rises?

Well, my number one recommendation is to stock up now while stamps are still at the old price. Standard and large-letter stamps don’t have values printed on them and will still be valid after the April price rise comes in. If you can afford to buy (say) 100 standard first-class stamps and 100 standard second class stamps, that will save you £14 in total.

The best bet for buying stamps is – of course – your local post office. If you don’t have one near at hand, however, you can also buy in bulk from The Royal Mail Shop (minimum order £50 for free delivery)..

Amazon also sell postage stamps, though costs vary and when I checked some prices were significantly higher than at post offices. But they may be worth a look, especially if you are an Amazon Prime member.

Another option you could consider is the online auction site eBay. There can be good savings to be made here, but check reviews and ratings carefully and be wary of offers that are clearly too good to be true.

  • Remember, also, that older UK stamps without barcodes are no longer valid.

For more information about the price rise and all the new rates from 7 April 2026, you can see a full list of prices here

If you have any comments or questions about the above, as always, please do post them (no pun intended!) below.


If you enjoyed this post, please link to it on your own blog or social media:
My Investments Update - March 2026

My Investments Update – March 2026

Here is my latest monthly update about my investments. You can read my February 2026 Investments Update here if you like.

I’ll begin as usual with my JP Morgan Personal Investing (previously NutmegStocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

As regular readers will know, in June last year I transferred most of the money in my former Nutmeg Fully Managed portfolio (just under £25,000) to a new Nutmeg Income Portfolio. I discussed this in detail in this post, but basically money in this port is invested to generate an income from share dividends and other sources. This is then paid monthly. Capital appreciation is targeted as well, but these portfolios are aimed primarily at older people (and others) who want/need their investment to generate a regular cash income.

In January my JPM Investing income portfolio generated £124.25 of income, which was duly paid in to my bank account on 24 February 2026. That means I have now received a total (tax-free) income of £198.14 in 2026 and £669.60 since I opened the account in June last year. That’s about what I would have expected based on JPM’s projected annual return of just under 5% for income ports at my chosen risk level (five).

My income portfolio grew in value in February. It’s now worth £28,866 compared with £27,687 at the start of last month, a quite impressive rise of £1,179.

As the year-to-date screen capture below shows, this port has increased by £3,268 (12.74%) after fees since I opened it last June. That’s clearly good going, though I don’t suppose it will carry on like this indefinitely. Performance may have been helped a bit by the no-fees introductory offer on Nutmeg/JPM income portfolios until the end of 2025. That has of course ended now.

JPM Income portfolio March 2026

I still have a smaller, growth-oriented pot using JPM Investing’s Smart Alpha option. This is now worth £4,974 (rounded up) compared with £4,790 a month ago, an increase of £184. Here is a screen capture showing performance in the year to date.

JPM Smart Alpha port March 2026

Finally, at the start of December 2023 I invested £500 in one of Nutmeg/JPM’s thematic portfolios (Resource Transformation). In March 2024 I also invested a further £200 from referral bonuses (something I no longer receive). As you can see from the YTD screen capture below, this portfolio is now worth £996 (rounded up) compared with £956 last month, an increase of £40.

JPM Thematic port March 26

Overall in February I was up by £1,403 or 4.20%. In addition I did, of course, receive £124.25 in income from my income portfolio. In total, then, I am in profit for the month by £1,527.25.

Excluding income generated, the overall value of my JPM investments is up by £4,029 or 13.08% since the start of March 2025. If you add to this figure the £669.60 of income generated by my Income portfolio so far, that gives a total profit for the last 12 months of £4,698.60 – not a bad return in these uncertain times.

As I always have to say, some volatility is to be expected with stock market investments, but over the longer term they tend to even themselves out (and typically outperform bank savings accounts, although that is never guaranteed). In general the worst thing you can do is panic and sell up when downturns occur. You are then crystallizing your losses rather than giving the markets time to recover. This is something I had cause to discuss in this blog post.

You can read my full original Nutmeg/JPM review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last nine years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Housemartin. As discussed in this post, the company rebranded last year from Assetz Exchange.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £302.22 in revenue from rental income. I have made a small net loss of £20.25 on property disposals. Capital growth generally has slowed, in line with UK property values generally.

At the time of writing, 19 of ‘my’ properties are showing gains, 4 are breaking even, and the remaining 21 are showing losses. My portfolio of 44 properties is currently showing a net decrease in value of £69.21. That means that overall (rental income minus capital value decrease and loss on disposal) I am up by £212.76. That’s still a respectable return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I usually reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my original review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].

In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

In January this year, as Oil Worldwide hadn’t exactly been setting the world alight, I decided to switch my entire investment in this to another smart portfolio, InTheGame. This port, focusing on the computer gaming industry, has been the top performer for some time in my eToro virtual portfolio.

Unfortunately just as I switched away from Oil Worldwide, US President Trump decided to invade Venezuela. This gave the oil industry a significant boost, which I would otherwise have benefited from. Meanwhile InTheGame hasn’t been doing particularly well, partly due to the recent downturn in AI stocks. At the time of writing the value of my investment in this has fallen by nearly 14%. Hey ho! This does of course demonstrate that there are never any guarantees when investing and unexpected events can thwart the best-laid plans…

As you can see from the screen captures below, my original eToro investment (total value £888.36 in pounds sterling) is today worth £1,091.94, an overall increase of £203.58 or 22.92%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.

EtoroMainMarch26


Etoro Port March 26

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this post.

As mentioned above, my new investment in InTheGame is currently down by nearly 14%. My copy trading investment with Aukie2008 continues to do well, however, with an impressive overall profit of 62.08%. Of course, I have held this investment for quite a bit longer.

My Tesla shares, which I purchased as an afterthought with some spare cash I had in my account, are down again this month but still showing an overall profit of over 252% since I bought them. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio.

As an experiment, at the start of April last year I put £50 into an investment ISA with Trading 212. As mentioned in my blog post about dividend investing, I put it into the (Almost) Daily Dividends Portfolio, a ready-made portfolio or ‘pie’ on Trading 212. As you can see from the screen capture below, my portfolio is now worth £61.84, an increase of £11.84 or 23.60% over the ten-month period. It has even accrued a grand total of 97p in dividends, most of which has now been (automatically) reinvested.

Trading 212 Dividends Account March 26

I am quite impressed with how this investment has been faring, despite the small amount I put in (which means I may be missing out on some smaller dividends). If I increased my investment I would almost certainly become eligible for more dividends, and even more the longer I remain invested. If I had any spare money at the moment, I would consider doing this. Of course, I do now have an income-focused portfolio with JPM Investing as well (see above).


Moving on, I published various posts on Pounds and Sense in February. I have listed below those that are still relevant.

In How to Save Money on Cruise Holidays I looked at a type of holiday that has become increasingly popular with older adults. They offer a relaxed way to travel, with accommodation, meals, entertainment and transport between destinations all included in one package. Cruise prices can vary significantly, however, and it’s not always obvious where good value ends and unnecessary expense begins. So in this post I set out some ways to keep cruise costs under control, while still getting the most from your time away.

I also posted an updated version of Get a Free Share Worth up to £100 with Trading 212. Anyone who hasn’t done this before can get a free share worth up to £100 just by signing up for a new Trading 212 investment account via my link. The current offer closes on Wednesday 4th March so you will need to move quickly on this now!

Also in February I published a guest post on the subject Why a Post-Nuptial Agreement Could be a Wise Financial Decision. This concerns a subject that – while it might seem unromantic – could be crucial to ensuring your financial security in later life.  This article is  by Richard Scott, a partner in the family team at HCR Law. In it he explains the benefit of having a post-nuptial agreement in place if, sadly, your marriage (or civil partnership) should come to an end.

I also published another guest post, on the subject of How Your Morning Coffee Might Protect Your Brain as You Age. This concerns a subject close to many people’s hearts (including mine!) – what are the benefits (and risks) of coffee drinking and how much a day is best? It may be of particular interest to older people, as the latest research indicates that the caffeine in coffee (and tea) may offer some protection from dementia. The article is by Eef Hogervorst, Professor of Biological Psychology at Loughborough UniversityIt was originally published in The Conversation.

Is a River Cruise Right for You? was a follow-up to my earlier article about how to save money on cruise holidays. In this article I focused on river cruises, which have become a very popular option among older travellers. I explored the pros and cons of river cruising – particularly for older people – and shared some tips to help you get the best value for money on your river cruise holiday.

Finally, in Get Your Will Written Free of Charge in March, I explained how – if you and/or your partner are over 55 – you may be able to get your will written for free by taking advantage of Free Wills Month. Appointments are limited and on a first come, first served basis, so it’s important to take action on this as soon as possible. Once all available appointments are taken, the campaign will close. This may happen before the end of March.

I’ll close with a reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as it is called now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out!

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. Twitter/X remains my primary social media platform, but I also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂
Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!
If you enjoyed this post, please link to it on your own blog or social media:
Get Your Will Written Free of Charge in March

Get Your Will Written Free of Charge in March

Did you know that March is Free Wills Month?

Free Wills Month brings together a group of well-respected charities to offer members of the public aged 55 and over the opportunity to have their wills written or updated free using participating solicitors across the UK. The next one begins on Monday 2nd March 2026.

The charities involved include the NSPCC, Dogs Trust, Help for Heroes, Mind, Stroke Association, PDSA, Royal British Legion, Alzheimers Research UK, Mencap, British Heart Foundation, Age UK, and so on. You can see all the charities involved on this web page.

The scheme covers simple wills only, including ‘mirror wills’ for couples. In the latter case, only one member of the couple has to be 55 or over. If you need a complicated will (most people don’t) you can still have this done but may have to pay a top-up fee.

I strongly believe in using a properly qualified solicitor to draw up your will. In the last few years there have been a couple of occasions when failing to do this has caused problems and delays for members of my family. An up-to-date will written by a solicitor will ensure that your wishes are respected and will avoid causing legal complications for your loved ones after you are gone.

Free Wills Month means what it says. There are no catches, although the organizers obviously hope that you will choose to leave a donation to charity in your will. There is no obligation to do this, however.

To take part in Free Wills Month click through to the website on or after March 2nd 2026. You can then pick a solicitor from the list of companies taking part and contact them to book an appointment. Appointments are limited and on a first come, first served basis, so it’s important to call as soon as possible. Once all available appointments are taken, the campaign will close. This may happen before the end of March.

  • Until March 2nd you can enter brief details on the Free Wills Month website and will then receive an email reminder when the scheme opens.

If you have any comments or questions about this subject, as ever, please do post them below.

This is an annual update of this post.


If you enjoyed this post, please link to it on your own blog or social media:
Is a River Cruise Right for You?

Is a River Cruise Right for You?

In a recent post I talked about How to Save Money on Cruise Holidays. One or two people asked if I had any specific advice on river cruises, so today I thought I would address this subject.

River cruising has become one of the fastest-growing travel trends in recent years, and it’s not hard to see why. With scenic routes that wind through historic towns, a gentle pace, boutique ships and inclusive experiences, river cruises can feel like a dream holiday. But are they right for you?

In this post, I will explore the pros and cons of river cruising – particularly for older travellers – and share some  tips to help you get the best value for money.

🌊 What Is a River Cruise?

Unlike ocean cruises that traverse vast stretches of sea, river cruises sail inland waterways – think the Danube, Rhine, Seine, Douro, Nile or Volga. Ships are typically smaller, with fewer passengers and a focus on cultural immersion and sightseeing.

👍 Pros of River Cruises

1. Gentle Pace & Easy Exploration

River cruises are designed for relaxation, with stops in multiple towns and cities. You often disembark right in the heart of destinations – no long transfers from ports. This is ideal for older travellers who want culture without stress.

2. All-Inclusive Comfort

Most river cruise packages include meals, onboard entertainment and guided excursions. Fewer hidden costs mean easier budgeting – a big plus if you’re watching the pounds and pence.

3. Accessible & Stress-Free

Ships have fewer stairs and lots of public open space. Many cabins and facilities are designed for accessibility, which suits older passengers or anyone with mobility issues.

4. Scenic Days & Scenic Nights

You rarely miss a view, cruising through vineyards, past castles and alongside charming villages. It’s like a constantly changing hotel window.

5. Sociable but Calm Atmosphere

With smaller ships and more mature crowds, river cruising tends toward a relaxed, sociable vibe without the “big ship” bustle.

👎 Cons of River Cruises

1. Higher Cost per Day

River cruises are often more expensive per person, per day than equivalent ocean cruises or land tours – especially during peak seasons.

2. Smaller Cabins

Space is at a premium. Cabins can feel compact – which might be uncomfortable if you like extra room.

3. Limited Onboard Activities

If you crave night-time entertainment, water-slides or casinos, river cruising might feel too sedate. It’s more about sightseeing than onboard spectacle.

4. Mobility Needed for Excursions

Most shore excursions involve walking tours. While many are gentle, some may not be suitable for travellers with limited mobility unless you choose accessible options.

5. Seasonal & Weather Dependent

River levels vary with the weather. Drought or heavy rain can affect itineraries – something to keep in mind when planning.

💡 River Cruise Tips – Get the Best Value for Money

If a river cruise sounds appealing, here’s how to make sure it’s a smart financial decision:

1. Book Early – Or Last-Minute

Booking early often secures the best cabins and lower prices. But some lines also discount last-minute sailings to fill unsold berths. Stay flexible and watch for deals.

2. Choose Shoulder Seasons

Travelling in spring or autumn often means lower prices, fewer crowds and milder weather — great for cost-conscious explorers.

3. Compare Inclusions

Don’t just look at headline prices. Check what’s included. Flights, transfers, excursions and drinks packages can add up.

A slightly higher headline price with lots included may represent better value overall.

4. Compare direct vs agent pricing

Sometimes booking directly with the cruise line is cheaper; other times a specialist agent will have better exclusive rates.

5. Fly from Regional Airports

River cruise packages often include flights. Compare prices from regional UK airports — you may find cheaper deals than London departures.

6. Consider Solo or Shared Cabins

Some lines offer solo cabins or shared spaces that can be more affordable if you’re travelling alone.

7. Use Loyalty Programmes & Travel Agents

Cruise line loyalty programmes can bring discounts, upgrades or onboard credits. Specialist cruise agents often know about promotions that aren’t publicised online.

8. Plan Your Excursions Wisely

Shore excursions arranged through the cruise can be expensive. Look into local guides or self-guided tours where safe and feasible.

🛳️ How to Book Your River Cruise (and Where to Find Deals)

Booking a river cruise might seem daunting at first – there are many companies, rivers, dates and price points to choose from. But with a bit of know-how and the right resources, you can find great value and a cruise that suits your travel style and budget.

🌐 Specialist River Cruise Websites (UK Focused)

For many UK travellers, booking through a river cruise specialist can be one of the easiest ways to find the best deals and get expert advice:

  • RiverCruising.co.uk – A UK-based specialist agent offering cruises from a range of operators, with ABTA and ATOL protection and support in choosing the best itinerary for you.

  • GlobalRiverCruising.co.uk – Independent UK specialists focused on delivering tailored itineraries and exclusive savings across multiple top cruise brands.

  • Blue Water Holidays / CruisingHolidays.co.uk – UK travel agencies that cover river and small-ship cruises with plenty of detailed itineraries, customer reviews and exclusive deals.

  • LoveitBookit.com – Another trusted UK cruise agency where you can explore river cruise options and get personalised support from cruise experts.

These specialist sites often bundle flights, transfers and insurance into your holiday package and can help you navigate which cruise line and dates are best for your budget.

💻 Discount and Deal Sites

If you’re hunting for current deals and discounts, here are a few places worth checking regularly:

  • Wowcher – Offers curated travel deals, including discounted river cruise holidays in Europe.

  • Cruise comparison sites like Cruise1st also list special seasonal offers and upgrades on river cruise itineraries.

💡 Pro tip: Sign up for newsletters from these sites and the cruise lines themselves — many discount offers (especially early-bird or seasonal sales) go out first to email subscribers.

🚢 Leading River Cruise Companies for UK Travellers

Here are some of the most popular and reputable river cruise operators you might consider when booking:

🌍 Major International River Cruise Lines

  • Viking River Cruises – One of the best-known names in river cruising, with a wide range of European itineraries and good UK-specific resources.

  • AmaWaterways – Highly regarded for quality service, food, and wine, with promotional offers on many routes.

  • Emerald Cruises – Offers strong value deals with flights and extras sometimes included, plus seasonal discounts.

  • Uniworld Boutique River Cruises – Known for luxury, all-inclusive offerings and beautifully designed ships.

  • Amadeus River Cruises – A traditional European operator focused on elegant boutique-style river experiences.

  • CroisiEurope – A family-run French line with a vast range of European river routes and good mid-range pricing.

  • Saga River Cruises – A UK-focused operator tailored for travellers over 50, offering all-inclusive European river cruises with added UK perks such as included chauffeur services and local departures.

📍 How They Work for UK Travellers

  • Many of these companies have UK-specific websites and/or call centres and offer flight-inclusive packages departing from UK airports.

  • Booking early – often 12–18 months ahead – can secure the best cabins and prices, as river cruises tend to sell out popular routes well in advance. (Cruise community insights also suggest booking early rather than waiting for last-minute deals due to limited capacity.)

💭 Closing Thoughts: Is a River Cruise Worth It?

If you love scenic travel, cultural immersion and a relaxed pace – and you’re willing to pay a bit more for convenience and comfort – river cruising can be an unforgettable experience. For older travellers, the accessibility, ease and inclusive nature are major advantages.

But if you’re after huge ships with lots of entertainment or travel on a tight budget, alternative holiday types (like escorted tours or independent travel) might suit you better.

Ultimately, it comes down to your travel priorities, mobility and budget. With smart planning and savvy spending, a river cruise can be both affordable and deeply rewarding.

  • Have you tried a river cruise yourself and would you recommend it? Have any other tips for saving money or making the most of your holiday? Please do leave a comment below!


If you enjoyed this post, please link to it on your own blog or social media:
Coffee might protect your brain as you age

Guest Post: Your Morning Coffee Might Protect Your Brain as You Age – Here’s the Sweet Spot!

Today I have a guest post on a subject close to many people’s hearts (including mine!) – what are the benefits (and risks) of coffee drinking and how much a day is best?

This subject may be of particular interest to older people, as the latest research indicates that the caffeine in coffee (and tea) may offer some protection from dementia.

The article is by Eef Hogervorst, Professor of Biological Psychology at Loughborough University. It was originally published in The Conversation and is republished here under a Creative Commons licence.


Scientists have found that drinking two to three cups of coffee a day may significantly reduce your risk of developing dementia, but drinking more won’t help protect your brain any further.

A major study tracked 131,821 American nurses and health professionals for up to 43 years, starting when they were in their early 40s. During this time, 11,033 people – around 8% – developed dementia. But those who drank moderate amounts of caffeinated coffee or tea were notably less likely to be among them.

The protective effect was strongest in people aged 75 or younger, who saw their dementia risk drop by 35% if they consumed around 250mg-300mg of caffeine daily – roughly two to three cups of coffee. Crucially, drinking more than this didn’t provide any extra benefit.

Women in the study reported drinking around four and a half cups of coffee or tea per day when they joined, while men drank around two and a half cups. Those who drank more caffeinated coffee tended to be younger, but they also drank more alcohol, smoked and consumed more calories – factors that all have been found to increase dementia risk.

Interestingly, people who drank more decaffeinated coffee showed faster memory decline. Researchers believe this is probably because people switched to decaf after developing sleep problems, raised blood pressure, or heart rhythm disturbances – all of which are themselves linked to cognitive decline and dementia.

Why caffeine might protect the brain

There are sound biological reasons why caffeine could help keep our brains healthy. It works by blocking adenosine, a chemical that dampens the activity of brain messengers like dopamine and acetylcholine. These brain messengers (or neurotransmitters) can become less active as we age and in conditions such as Alzheimer’s disease, so caffeine’s stimulating effect may help counteract this decline.

Caffeine also appears to work through other mechanisms, including reducing inflammation and helping regulate blood sugar metabolism. People who did not have dementia (yet?) but drank more than two cups of coffee daily throughout their lives had lower levels of the toxic amyloid plaques, abundantly found in people’s brains who have Alzheimer’s disease.

Coffee and tea also contain many other beneficial compounds with antioxidant and blood vessel benefits which can all protect the ageing brain.

The American study found that only one to two cups of tea were linked to the best protection against dementia, which may reflect the fact that people in the US drink less tea than coffee overall. Green tea wasn’t examined separately, although most studies suggest it also protects against dementia.

Why does more caffeine stop being helpful? The researchers suggest it may be down to how our bodies break down coffee. Very high doses can also disrupt sleep and increase anxiety, which undermines any brain benefits.

A principle established back in 1908, known as the Yerkes-Dodson law, shows that when we become too stimulated – whether from anxiety or too much coffee – our mental performance starts to decline.

The findings from professional healthcare workers may not apply to everyone. But when researchers combined results from 38 other studies, they found similar results: caffeine drinkers had a 6%-16% lower dementia risk than non-drinkers, with one to three cups of coffee being optimal. Good news for tea lovers – in this broader analysis, drinking more tea was linked to greater protection.

Moderate caffeine intake doesn’t increase long-term blood pressure risk and may even reduce cardiovascular disease risk, which shares many risk factors with dementia. However, people with very high blood pressure are advised to limit themselves to perhaps one cup a day.

It’s worth noting that using “cups” as a measure doesn’t account for how much caffeine these actually contain. Fresh beans brewed at home contain different amounts of caffeine and can affect cholesterol levels differently than instant coffee, for instance.

But you don’t need much to feel a benefit. Even low doses of 40mg-60mg can improve alertness and mood in middle-aged people who normally did not drink (much) caffeine. More is not always better.The Conversation

Eef Hogervorst, Professor of Biological Psychology, Loughborough University

This article is republished from The Conversation under a Creative Commons license. Read the original article.

As always, if you have any comments about this article, please do post them below.


If you enjoyed this post, please link to it on your own blog or social media: