Investing

Post about boosting your funds through investment. Includes both traditional and non-traditional investment opportunities.

UK Government Bonds: Are Gilts Worth Considering Now?

UK Government Bonds: Are Gilts Worth Considering Now?

UK government bonds – better known as gilts – have been attracting renewed attention from investors.

That is hardly surprising. After years when interest rates and bond yields were unusually low, gilt yields have risen substantially. In September 2026, the yield on 10-year UK government bonds recently climbed above 5.3%, its highest level since 2007. Even more strikingly, yields on 20- and 30-year gilts have reached their highest levels since 1998.

For investors looking for a relatively low-risk home for some of their money, this may look attractive.

But there is more to gilts than simply seeing a headline yield of 5% or more. Bond prices can fall as well as rise, and the return you actually receive depends on which gilt you buy, the price you pay and how long you hold it.

So, are gilts worth considering now – and what are the best ways for private investors to buy them?

What exactly is a gilt?

A gilt is essentially a loan to the UK Government.

When you buy a gilt, you are lending money to the government. In return, the government normally pays you interest (known as the coupon) twice a year and repays the face value of the gilt when it matures.

For example, suppose you buy a gilt with a nominal value of £1,000 and a 4% coupon.

You would normally receive £40 a year in interest, paid in two instalments of £20.

At maturity, assuming the gilt is held to redemption, you receive the £1,000 face value back.

Gilts are issued by HM Treasury and the UK Debt Management Office (DMO) manages the gilt issuance programme.

There are also index-linked gilts, where both the interest payments and redemption value are linked to inflation. These work somewhat differently from conventional gilts and can potentially provide useful protection against inflation.

Why have gilt yields risen so much?

Bond yields move around for several reasons, but interest-rate and inflation expectations are particularly important.

The recent rise has been driven by a combination of factors, including concerns about inflation, higher oil prices, expectations about future Bank of England interest rates and worries about government borrowing.

The latest move has been particularly pronounced at the long end of the market. On 8 September, for example, the UK Government sold 30-year gilts at a yield of 5.82%, the highest borrowing cost for a comparable issue since 1998.

This matters to investors because higher gilt yields generally mean lower gilt prices.

That may sound counter-intuitive. After all, wouldn’t a higher yield be good news?

It is – if you are buying the bond now.

But existing bonds have to adjust in price to compete with newly issued bonds offering higher yields.

Coupon versus yield – an important distinction

One of the easiest mistakes to make with gilts is to confuse the coupon with the yield.

Suppose a gilt has a 3% coupon but can currently be bought for £90 for every £100 of face value.

You still receive the coupon based on the £100 face value. But because you only paid £90, your overall return if you hold the gilt to maturity is higher than 3%.

This is where the yield to maturity comes in.

The yield to maturity takes account of:

  • the purchase price
  • the coupon payments
  • the time remaining until maturity
  • the £100 redemption value.

The DMO gives a useful example of this. A gilt bought for £90 and held to maturity can produce a yield significantly above its coupon because the investor also receives a £10 capital uplift when the government redeems it at £100.

This is why investors should generally compare gilts using their yield to maturity, rather than simply looking at the coupon.

The big attraction: relatively low credit risk

One of the main reasons people buy gilts is security.

The borrower is the UK Government, rather than a company or individual. Provided the gilt is held until maturity and the UK Government meets its obligations, the investor receives the promised interest and redemption payment.

That makes gilts considerably less risky from a credit perspective than shares or corporate bonds.

However, “low risk” does not mean “no risk”.

There are two particularly important risks to understand.

Risk 1: Gilt prices can fall

If you buy an individual gilt and hold it until maturity, short-term movements in its market price may not matter much.

But if you need to sell before maturity, they certainly do.

Suppose you buy a 20-year gilt paying a relatively attractive yield today. If interest rates subsequently rise further, newly issued bonds may offer higher yields.

Your gilt therefore becomes less attractive and its market price can fall.

The longer the maturity, the more sensitive a conventional gilt tends to be to changes in interest rates. A 20- or 30-year gilt can therefore experience quite substantial price movements.

The DMO itself warns that the market value of gilts can go down as well as up, potentially resulting in a loss if you sell before redemption.

This is one reason why investors approaching or in retirement should be cautious about automatically choosing the longest-dated gilt simply because it offers the highest yield.

Risk 2: Inflation

A gilt paying 5% might sound very attractive.

But if inflation is running at 4%, your real return is much less impressive.

And if inflation were to remain high for several years, a fixed-interest gilt could lose purchasing power.

Index-linked gilts are designed to address this particular problem because their payments and redemption value are linked to an inflation index.

They have their own complexities, though, and aren’t necessarily suitable for everyone.

So why consider gilts now?

There are several reasons why gilts may be worth a look.

1. Yields are much more attractive than they used to be

For much of the 2010s and early 2020s, investors had to accept extremely low yields on government bonds.

That situation has changed.

With longer-term gilt yields now around 5% or more, bonds can potentially make a meaningful contribution to portfolio income.

2. You can lock in a return for a known period

With an individual gilt, you know the maturity date and the payments that are due under its terms.

If you choose a gilt maturing in, say, five years and hold it to redemption, you don’t have to worry about what the market price is doing in the meantime.

That can be particularly useful for someone who knows they will need a particular amount of money at a particular time.

3. Gilts can diversify a share portfolio

Shares and government bonds behave differently.

They can both fall in value, particularly during periods of financial stress, but they are driven by different factors.

Holding some gilts alongside equities can therefore reduce the overall volatility of an investment portfolio.

4. There is a valuable tax advantage

One particularly attractive feature for UK investors is that capital gains on UK government gilts are exempt from Capital Gains Tax. HMRC confirms that gains on qualifying UK government gilts are exempt from CGT.

This can make certain gilts particularly interesting to investors who hold investments outside an ISA or pension.

For example, if you buy a gilt below its £100 redemption value and hold it until maturity, the difference between what you paid and the £100 you receive at redemption is normally a capital gain. With qualifying gilts, that gain is not subject to CGT.

There is an important catch, however: the interest you receive is still taxable income when gilts are held outside a tax wrapper.

For that reason, gilts can also be worth considering inside an ISA or pension/SIPP, where the investment income receives the relevant tax advantages of the wrapper.


How can you invest in gilts?

There are several routes.

Option 1: Buy individual gilts through an investment platform

For many private investors, this is probably the most straightforward approach.

Platforms such as Hargreaves Lansdown, AJ Bell, Interactive Investor and others allow investors to buy individual gilts through their dealing services.

You can choose a particular gilt based on:

  • its maturity date
  • its current price
  • its coupon
  • its yield to maturity.

You can then hold it until maturity or sell it beforehand.

This approach gives you considerable control over exactly what you are investing in.

It can be especially useful if your objective is something like:

“I want to invest £20,000 and have it mature in approximately five years.”

You can select gilts with a suitable maturity date rather than leaving the timing to a bond fund manager.

Option 2: Buy gilts through the DMO’s retail service

The UK Debt Management Office also operates a Purchase and Sale Service for UK retail investors.

This provides access to gilts in the secondary market and is administered by Computershare.

However, it is an execution-only service and doesn’t offer the convenience or functionality of a modern investment platform.

For many investors, a mainstream investment platform will therefore be easier.

Option 3: Invest through a gilt fund or ETF

Instead of buying individual gilts, you can invest in a gilt fund or exchange-traded fund (ETF).

This has some important advantages.

A fund can hold dozens or even hundreds of government bonds, giving you diversification without having to select individual issues.

You also don’t have to worry about choosing a particular maturity date.

However, there is an important difference.

A gilt fund does not mature.

If you buy an individual gilt and hold it to maturity, you know that the government is scheduled to repay its face value at a specified date.

A bond fund continually buys and sells bonds as part of its management. Its value can therefore continue to rise and fall indefinitely.

This means a gilt fund can be more volatile than someone might expect from the phrase “government bonds”.

Funds and ETFs can nevertheless be an excellent choice for investors who want broad exposure to the UK government bond market rather than a specific maturity.

Which is better – individual gilts or a gilt fund?

It depends on what you are trying to achieve.

If your priority is… You might consider…
Knowing exactly when your investment matures Individual gilt
Locking in a yield to a particular date Individual gilt
Creating a ladder of future maturities Individual gilts
Diversifying across many bonds Gilt fund/ETF
Simplicity Gilt fund/ETF
Regularly adjusting the portfolio Gilt fund/ETF
Avoiding the need to select individual issues Gilt fund/ETF

For someone in or approaching retirement, I think the individual gilt approach is particularly interesting when you have a known future spending requirement.

For example, if you know that £10,000 will be needed in four years’ time, buying a suitable gilt maturing around then can potentially be a useful way of matching an investment with that future liability.

What about ISAs and SIPPs?

Gilts can be held within tax-efficient wrappers such as Stocks and Shares ISAs and SIPPs, subject to the rules of the particular platform.

This can be attractive because the interest and investment gains then benefit from the tax advantages of the wrapper.

However, remember that gilts already have the unusual advantage of being exempt from CGT when held outside a wrapper.

Consequently, the tax calculation isn’t always as straightforward as it is with shares or funds.

For someone with substantial taxable investment income, keeping interest-generating investments inside an ISA or pension can still be valuable.

And for investors who have already used their ISA allowance, the CGT exemption on qualifying gilts can make them worth considering in a taxable investment account.

What about short-dated gilts?

Don’t assume that longer-dated gilts are necessarily better.

If your main objective is protecting your capital over a relatively short period, a short-dated gilt may be more appropriate.

Shorter-term bonds are generally less sensitive to changes in interest rates than long-dated ones.

There is also a growing UK Treasury-bill market. Treasury bills are very short-term government securities and are intended primarily as liquidity and cash-management instruments rather than long-term investments. The government is also expanding the range of Treasury-bill maturities available.

For an investor who simply wants somewhere relatively low-risk to park money for a year or two, these shorter-duration instruments may be worth investigating alongside conventional gilts.

Should you buy now?

This is the difficult question.

The fact that gilt yields have risen sharply doesn’t mean they cannot rise further.

Indeed, recent events demonstrate how quickly bond markets can move. On 10 September, for example, the 10-year gilt yield reached 5.378%, while 30-year yields approached 5.95%.

If inflation remains stubbornly high or interest rates rise further, gilt prices could fall and yields could rise again.

On the other hand, if inflation subsides and interest rates eventually fall, today’s relatively high yields could prove attractive. Bond prices would also tend to rise, particularly for longer-dated gilts.

In other words, nobody knows whether today’s gilt yields represent the top of the market or merely another stage in a longer-term rise.

This is why I would be wary of trying to call the exact bottom or top of the gilt market.

Instead, investors could consider spreading purchases over time, particularly if investing a substantial lump sum.

A simple gilt strategy

One approach I particularly like for cautious investors is a gilt ladder.

Rather than putting £50,000 into one long-dated gilt, for example, you might divide the money between several gilts maturing at different dates.

You could have gilts maturing in approximately:

  • 2027
  • 2028
  • 2029
  • 2030
  • 2031

As each gilt matures, you receive the capital back and can decide what to do with it.

You could spend the money, reinvest it in another gilt, or use it for another investment.

This reduces the risk of having to make one big bet on where interest rates will be five, ten or twenty years from now.

Don’t confuse gilts with savings accounts

There is one final point worth stressing.

A gilt is not the same thing as a fixed-rate savings account.

With a savings account, you normally know exactly how much interest you will receive and how much money you will get back at the end of the fixed term.

With a gilt, you can lose money if you sell it before maturity.

For example, if you buy a long-dated gilt and interest rates subsequently rise sharply, its market value could fall considerably.

If you are certain you will need the money before maturity, this matters.

If you can hold the gilt until redemption, the interim price fluctuations are much less important.

My verdict

For many UK investors, particularly those approaching or in retirement, gilts are worth another look now that yields are substantially higher.

They can offer:

  • relatively low credit risk
  • a potentially attractive income
  • known maturity dates
  • portfolio diversification
  • protection from CGT on qualifying gilts
  • the ability to match investments with future spending needs.

But they are not risk-free.

The biggest danger is buying a long-dated gilt without appreciating how much its price can fall if interest rates rise further. And a 5% yield isn’t necessarily a 5% real return if inflation remains high.

For investors who want simplicity and diversification, a gilt fund or ETF may be the better choice.

For those who want to know exactly when their money will be returned, buying individual gilts and holding them to maturity can be particularly appealing.

With yields now at levels rarely seen in recent decades, I think gilts deserve a place on the shortlist of options for cautious investors. But, as ever, the right choice depends on your timescale, tax position, need for income and willingness to accept fluctuations in value.

And perhaps the most important lesson is this: Don’t buy a gilt simply because the headline yield looks attractive. Look at the yield to maturity, the maturity date and the risks involved before investing.

NOTE: This article is for information and education only and does not constitute personal financial advice. Investments can fall as well as rise and you may get back less than you invest. If you are in any doubt how best to proceed, I strongly recommend speaking to a professional financial adviser or financial planner. 


If you enjoyed this post, please link to it on your own blog or social media:
The £12,000 Cash ISA Limit

The £12,000 Cash ISA Limit: What Will Actually Change in 2027?

There has been quite a lot of discussion about the Government’s decision to reduce the annual Cash ISA allowance from £20,000 to £12,000 from April 2027. If you have money in Cash ISAs, you may therefore be wondering whether you should be doing anything differently before then.

There is, however, an important point that is sometimes missed in reports about the change:

The new £12,000 Cash ISA limit will only apply to people under the age of 65.

If you are aged 65 or over, you will continue to be able to put up to £20,000 a year into a Cash ISA.

Here’s what we know so far…

What Is Changing?

At present, the overall annual ISA allowance is £20,000. You can put this into a Cash ISA, a Stocks and Shares ISA, an Innovative Finance ISA (IFISA) or a combination of these, subject to the rules applying to each type.

For the 2026/27 tax year, the maximum you can subscribe to ISAs remains £20,000.

From 6 April 2027, however, the rules will change.

For people under 65, the annual Cash ISA subscription limit will become: £12,000

The overall ISA allowance will nevertheless remain at: £20,000

This means that the Government is not reducing the overall amount you can put into ISAs. Instead, it is restricting how much of that £20,000 can be put into a Cash ISA.

The remaining £8,000 could, for example, be put into a Stocks and Shares ISA, assuming you are happy to invest it and the relevant ISA rules are met.

The Important Exception for People Aged 65 and Over

This is particularly relevant to many Pounds and Sense readers. The £12,000 restriction does not apply to people aged 65 or over.

From April 2027, people aged 65 and over will continue to have a Cash ISA limit of £20,000 a year. There is also an interesting wrinkle here.

The Government says that entitlement to the higher £20,000 Cash ISA limit will apply from the start of the tax year in which you turn 65.

So, for example, if you turn 65 at some point during the 2027/28 tax year, you will qualify for the £20,000 Cash ISA limit for that whole tax year rather than having to wait until your 65th birthday.

This makes the age cut-off rather more generous than simply saying, “You can use £20,000 once you reach 65.”

What About Your Existing Cash ISAs?

The new £12,000 figure is an annual subscription limit. It does not mean that anyone with more than £12,000 already saved in Cash ISAs will have to withdraw the excess.

If you already have, say, £50,000 in one or more Cash ISAs, that money can remain there.

The new rules concern how much new money you can subscribe to Cash ISAs from 6 April 2027.

This is an important distinction.

Someone under 65 could therefore have considerably more than £12,000 in Cash ISAs after April 2027. They simply won’t be able to add more than £12,000 of new subscriptions to Cash ISAs during that tax year.

Can I Still Use the Full £20,000 ISA Allowance?

Yes.

For someone under 65, the overall annual ISA allowance will remain £20,000. The difference is that no more than £12,000 of this can normally be subscribed to Cash ISAs.

For example, someone could potentially put:

  • £12,000 into a Cash ISA
  • £8,000 into a Stocks and Shares ISA

That would use their full £20,000 annual ISA allowance.

Alternatively, they could put less than £12,000 into a Cash ISA and use the remainder for another type of ISA.

The Government says that the annual subscription limits for Stocks and Shares ISAs, Innovative Finance ISAs and Lifetime ISAs are not being reduced as part of this change.

Why Is the Government Doing This?

The stated aim is to encourage people to invest more of their savings rather than keeping everything in cash. The Government argues that some people hold substantial sums in Cash ISAs for many years when they might achieve better long-term returns through investments.

There is certainly a debate to be had about this. Cash has an important role in financial planning, particularly for people approaching or in retirement. It provides security and avoids the risk of investment losses.

On the other hand, money that is needed for the long term can potentially lose purchasing power if inflation is higher than the interest rate being earned. The Government’s policy is therefore intended, at least in part, to encourage more people to consider investing.

Whether that is appropriate for you is a separate question, of course.

What if I Don’t Want to Invest?

This is probably the biggest concern for many savers. Suppose you are aged 55, have £20,000 to save and don’t want to take investment risk.

From April 2027, you won’t be able simply to put the whole £20,000 into a Cash ISA. You could put £12,000 into a Cash ISA, but you would then need to decide what to do with the other £8,000.

One possibility would be an ordinary savings account. However, interest outside an ISA can be taxable, depending on your circumstances.

The Personal Savings Allowance means that many people can receive some interest tax-free, but the amount depends on your tax position.

Another possibility is to invest the remaining money through a Stocks and Shares ISA, but this is only appropriate if you are comfortable with investment risk and have a sufficiently long time horizon.

There is certainly no requirement to invest simply because the Government has made Cash ISAs less generous for under-65s.

Can I Put £20,000 Into a Stocks and Shares ISA and Then Move it Into a Cash ISA?

This is where the new rules become more complicated. Under the existing system, ISA transfers allow money to be moved between different types of ISA without losing its tax-free status, subject to the rules.

From April 2027, people under 65 will not be allowed to transfer money from a Stocks and Shares ISA or Innovative Finance ISA into a Cash ISA.

This is intended to stop people getting around the £12,000 Cash ISA limit by putting £20,000 into another type of ISA and subsequently moving the money into a Cash ISA.

Transfers in the other direction — from a Cash ISA to a non-Cash ISA — will remain possible.

What About Keeping Cash Inside a Stocks and Shares ISA?

The Government has also anticipated this potential workaround. From April 2027, people will still be able to hold some cash within a Stocks and Shares ISA.

However, there will be a 22% charge on interest paid on cash held in a non-Cash ISA. ISA managers will deal with this charge rather than the individual having to declare the interest to HMRC.

There will also be restrictions on using a Stocks and Shares ISA simply as a substitute Cash ISA. For example, an ISA portfolio consisting entirely of certain “cash-like” investments will not qualify in the same way.

The rules do, however, allow diversified Stocks and Shares ISA portfolios to contain some cash-like investments.

What Should You Do Before April 2027?

For most people, there is no need to panic.

If you are under 65 and have money that you were planning to put into a Cash ISA, however, it may be worth thinking about your plans before the new rules arrive.

For example, if you have £20,000 available and were intending to put the whole amount into a Cash ISA, you could potentially use the full £20,000 Cash ISA allowance during the 2026/27 tax year.

You should not, of course, put money into an ISA simply to beat a deadline if you don’t actually need or want the product. But if you already intended to save the money in a Cash ISA, the April 2027 change is worth bearing in mind.

What if I’m Already 65?

If you are 65 or over, the change is much less dramatic. You will continue to be able to subscribe up to £20,000 a year to a Cash ISA.

And, as mentioned earlier, if you turn 65 during a tax year, the Government says the £20,000 entitlement applies from the start of that tax year.

This means that the headline “£12,000 Cash ISA limit” is potentially rather misleading when talking to older savers.

For many Pounds and Sense readers, nothing will actually change regarding the amount they can put into a Cash ISA each year.

What About Existing ISA Savings?

Another important point is that the £20,000 annual ISA allowance is not a limit on the total amount you can have in ISAs. There is no £20,000 cap on your lifetime ISA holdings.

You could, for example, have £20,000 in an ISA from one year, another £20,000 from the following year, and so on, with the accumulated savings remaining tax-free.

The £20,000 figure is an annual subscription allowance, not a maximum ISA balance.

The new £12,000 figure works in the same way: it limits new Cash ISA subscriptions for under-65s from April 2027; it does not cap the amount you can have accumulated in Cash ISAs.

So, Is the New £12,000 Limit a Big Deal?

For some people, yes. For others, not at all.

If you are under 65 and normally put £20,000 a year into a Cash ISA, you will need to rethink what you do with the other £8,000.

If you normally save £5,000 or £10,000 a year in a Cash ISA, nothing changes.

And if you are aged 65 or over, your annual Cash ISA limit will remain £20,000.

For someone approaching 65, the rules may therefore be particularly worth understanding.

The key dates and limits

From 6 April 2027 Cash ISA limit Overall ISA limit
Under 65 £12,000 £20,000
Aged 65 or over £20,000 £20,000


The Government currently intends these changes to take effect on 6 April 2027. The detailed legislation is still going through the process, so some technical details could change before implementation. If that happens I will update this post accordingly and/or add a new post about it.

The Bottom Line

The most important thing to remember is that the Government is not abolishing Cash ISAs and it is not reducing the overall ISA allowance to £12,000.

From 6 April 2027:

Under 65: maximum £12,000 a year into a Cash ISA, within the overall £20,000 ISA allowance.

65 or over: maximum £20,000 a year into a Cash ISA, within the overall £20,000 ISA allowance.

Existing Cash ISA savings are not being capped at £12,000.

For many older savers, therefore, the change may have little or no direct impact. But for younger savers who prefer the safety of cash, it will mean making a decision about what to do with any amount between £12,000 and £20,000 that they would previously have put into a Cash ISA.

And that, rather than the headline figure of £12,000, is probably the most important point to understand.

  • As always, if you have any comments or questions about this post, please do leave them below. But note that I am not a professional financial adviser and cannot give personal financial advice. You should always do your own “due diligence” before investing and seek appropriate professional advice if in any doubt how best to proceed. All investing carries a risk of loss.


If you enjoyed this post, please link to it on your own blog or social media:
My Investments Update September 2026

My Investments Update – September 26

Here is my latest monthly update about my investments. You can read my August 2026 Investments Update here if you like.

I’ll begin as usual with my JP Morgan Personal Investing (previously Nutmeg) Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

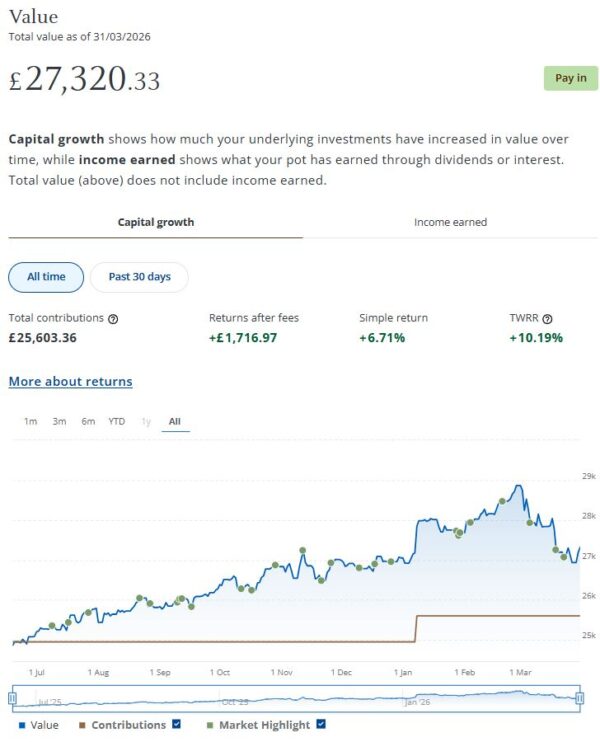
As regular readers will know, in June last year I transferred most of the money in my former Nutmeg Fully Managed portfolio (just under £25,000) to a new Nutmeg Income Portfolio. I discussed this in detail in this post, but basically money in this port is invested to generate an income from share dividends and other sources. This is then paid monthly. Capital appreciation is targeted as well, but these portfolios are aimed primarily at older people (and others) who want/need their investment to generate a regular cash income.

In August my JPM Investing income portfolio generated £157.02 of income, which was duly paid into my bank account on 24 August 2026. That means I have now received (tax-free) income of £894.41 in 2026 and a total of £1,365.87 since I opened the account in June last year. That’s a return on capital of around 5% to date. That is in line with JPM’s original projected annual return for income ports at my chosen risk level (five).

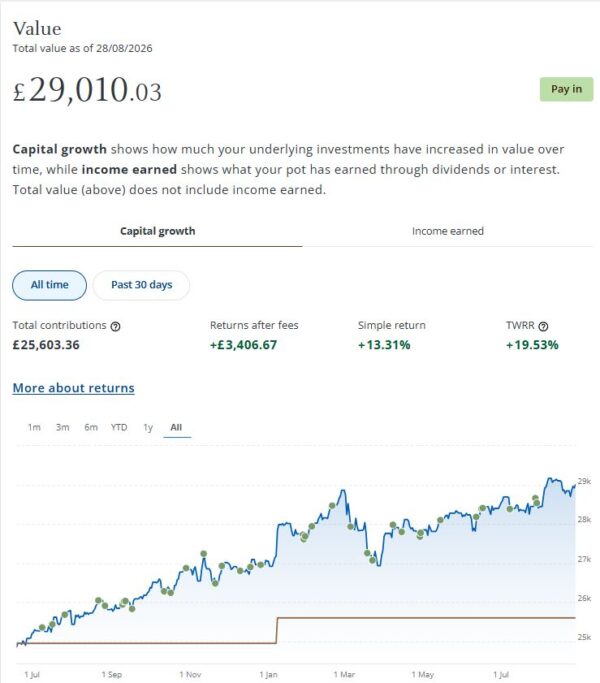
My income portfolio also increased in value in August. It’s now worth £29,010 compared with £28,447 at the start of August, a rise of £563. As the screen capture below shows, my income port is up by a respectable £3,406.67 (13.31%) after fees since I opened it in June 2025.

JPM Income port Sept 2026

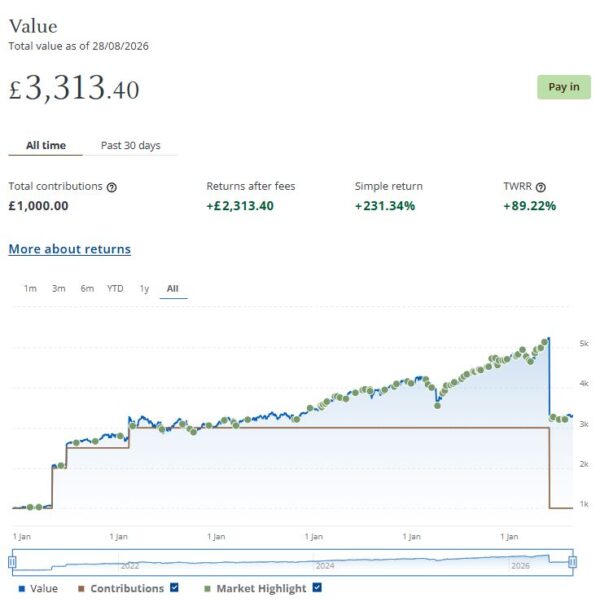
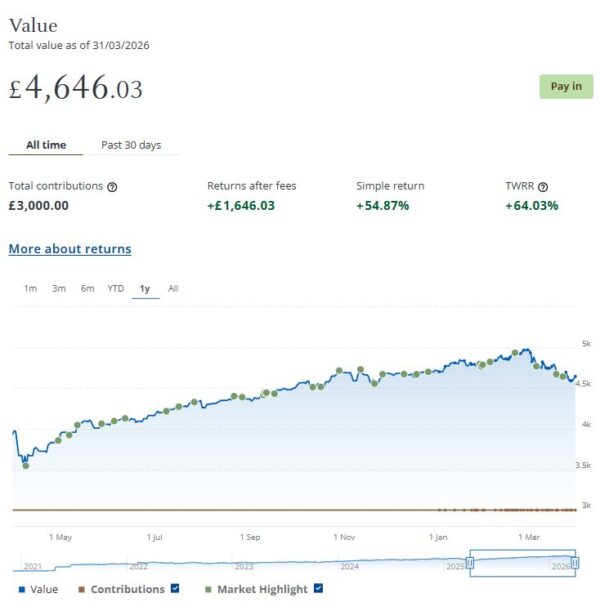
I still have a smaller, growth-oriented pot using JPM Investing’s Smart Alpha option. This is now worth £3,313 compared with £3,221 a month ago, a rise of £92. Here is a screen capture showing performance since I opened it in December 2020. As you may recall, I sold £2,000 worth of this portfolio in May this year to pay for some building work.

JPM Smart Alpha port Sep 2026

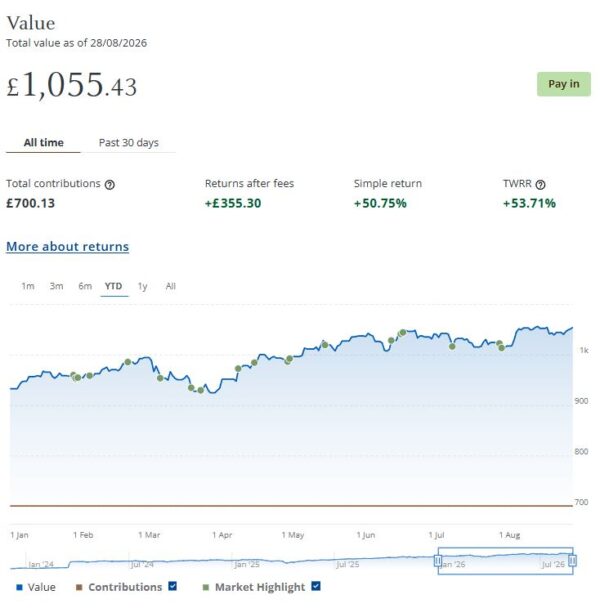
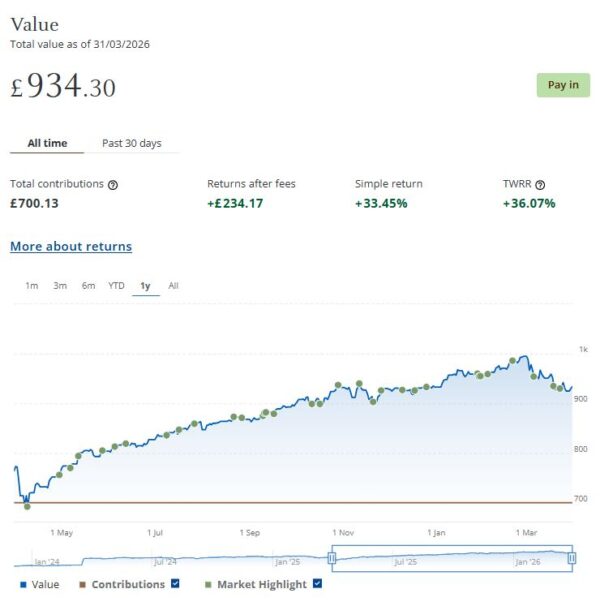
Finally, at the start of December 2023 I invested £500 in one of Nutmeg/JPM’s thematic portfolios (Resource Transformation). In March 2024 I also invested a further £200 from referral bonuses (something I no longer receive). As you can see from the YTD screen capture below, this portfolio is now worth £1,055 compared with £1,019 (rounded up) last month, a rise of £36.

JPM Thematic port Sep 2026

Overall in August the value of my JPM investments rose by £691 or 2.12%. In addition, I did of course receive £157.02 in income from my income portfolio. In total, then, I am up by a respectable £848.02 for the month.

Excluding income generated (and allowing for the £2,000 I withdrew in May this year) the overall value of my JPM investments has risen by £3,716 since the start of September 2025. If you add to this the £1,365.87 of income generated by my Income portfolio since August 2025, that gives a total profit for the last 12 months of £5,081.87 – a pretty good return in these uncertain times. Another way of looking at this (which I like!) is that the £2,000 I withdrew in May this year has been comfortably covered by the growth in value of my JPM investments over the last year.

Obviously it’s important not to read too much into a single month’s performance. Ups and downs are very much to be expected with stock market investments. In the longer term they tend to even themselves out and typically outperform bank savings accounts (though that’s never guaranteed). In general the worst thing you can do is panic and sell up when downturns occur. You are then crystallizing your losses rather than giving the markets time to recover. That is something I had cause to discuss last year in this blog post.

You can read my full original Nutmeg/JPM review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last nine years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Housemartin. As discussed in this post, the company rebranded last year from Assetz Exchange.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £339.75 in revenue from rental income. I have made a small net loss of £17.60 on property disposals. Capital growth generally has slowed, in line with UK property values generally.

At the time of writing, 25 of ‘my’ properties are showing gains, 4 are breaking even, and the remaining 18 are showing losses. My portfolio of 47 properties is currently showing a net decrease in value of £56.92. That means that overall (rental income minus capital value decrease and loss on disposal) I am up by £265.23. That’s still a respectable return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

  • A further consideration is that property investments on Housemartin are less likely to be affected by stock market downturns, as happened in March this year due to events in the Middle East. This again demonstrates the potential value of such investments for diversifying your portfolio during challenging times.

The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I usually reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my original review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].

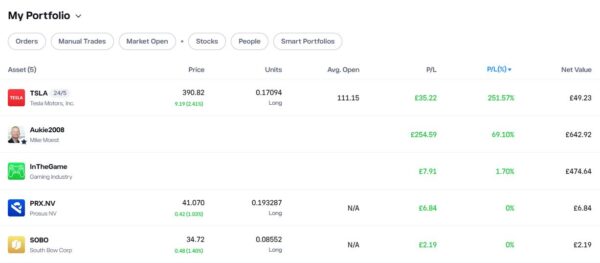
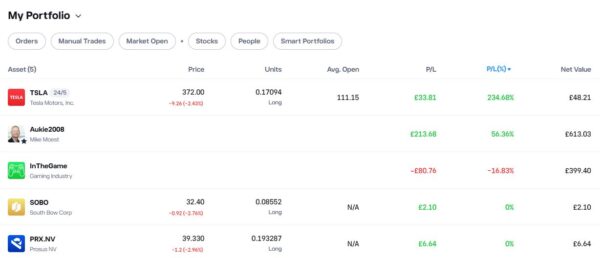
In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

In January this year, as Oil Worldwide hadn’t exactly been setting the world alight, I decided to switch my entire investment in this to another smart portfolio, InTheGame. This port, focusing on the computer gaming industry, had been the top performer for some time in my eToro virtual portfolio.

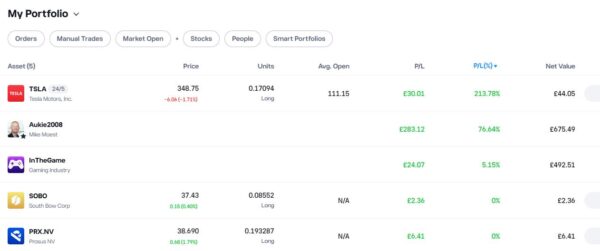
Unfortunately just as I switched away from Oil Worldwide, President Trump decided to invade Venezuela. This gave the oil industry a significant boost, which I would otherwise have benefited from. Meanwhile InTheGame went south, partly due to the war in the Middle East. At one point I was down by over 10% on this investment. Fortunately in the last few months InTheGame has made a recovery and is now in profit by 5.15%.

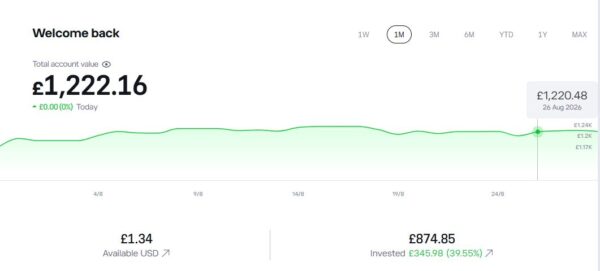
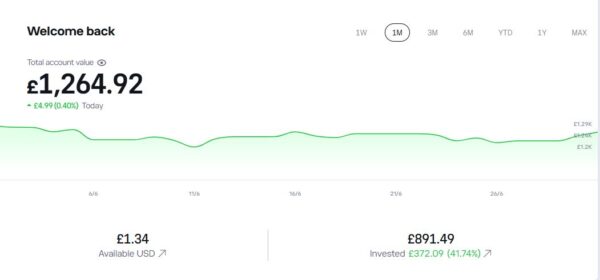
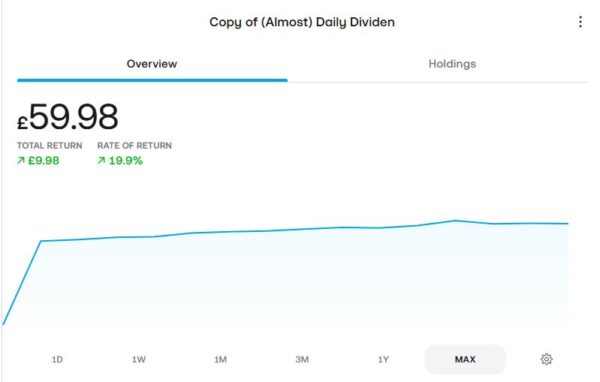
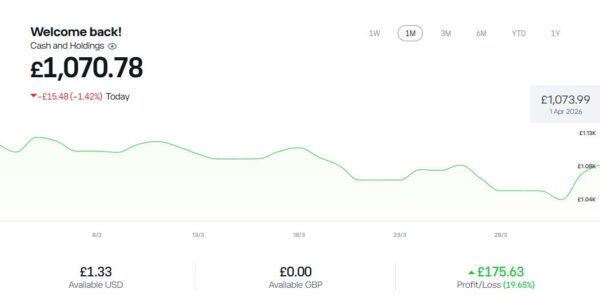
As you can see from the screen captures below, my original eToro investment (total value £888.36 in pounds sterling) is today worth £1,222.16, an overall increase of £333.80 or 37.57%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.

Etoro Home Sept 2026

Etoro port Sep 2026

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this post.

As mentioned above, my new investment in InTheGame is currently up by 5.15%. And my copy trading investment with Aukie2008 is showing an impressive overall profit of 76.64%. Of course, I have held this investment for quite a bit longer.

My Tesla shares, which I purchased as an afterthought with some spare cash I had in my account, are also up this month. They are now showing an overall profit of over 213% since I bought them. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio.

Moving on, I published several posts on Pounds and Sense in August. I have listed below those that are still relevant.
Caravan Fire Safety – How to Protect Your Holiday Home and Your Finances is a collaborative post with my friends at  Compass, a specialist provider of caravan and leisure insurance. It concerns an important subject all caravan owners need to be aware of. This post was especially relevant during the hot, dry spell we have just gone through. But even when the weather is cooler it’s still very relevant. In the article – which applies to static as well as mobile caravans – I set out a number of tips to keep your holiday home safe from fire, and also some important insurance advice for caravan owners.

In My Short Break in Portmeirion I talked about my recent short visit to this beautiful Welsh village and tourist resort (famously the location in which 1960s TV series The Prisoner was shot). It was the first time I had stayed in Portmeirion, though I had visited many times before. In my article I discuss the accommodation, the dining facilities, the costs, things to do in (and around) Portmeirion, and whom (in my view) the location is most likely to appeal to.

Finally in Pounds and Sense – A Personal Update I set out some information about my personal circumstances and (in particular) my plans for Pounds and Sense going forward. I won’t say any more about this here, but I do urge you to read it if you haven’t already.

  • One other thing is that, if you’re looking to change your energy provider as autumn approaches, you can get a £50 bonus credited to your account if you sign up with EDF Energy via my referral link. I’ve been with EDF myself for some years now. In my experience they offer a reliable service along with prices that are generally very competitive. If you do choose to do this via my link I will receive a bonus as well, which is very much appreciated 🙂

I’ll close with my customary reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as it is now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out!

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. Twitter/X remains my primary social media platform, but I also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!


If you enjoyed this post, please link to it on your own blog or social media:
My Investments Update August 2026

My Investments Update – August 2026

Here is my latest monthly update about my investments. You can read my July 2026 Investments Update here if you like.

I’ll begin as usual with my JP Morgan Personal Investing (previously Nutmeg) Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

As regular readers will know, in June last year I transferred most of the money in my former Nutmeg Fully Managed portfolio (just under £25,000) to a new Nutmeg Income Portfolio. I discussed this in detail in this post, but basically money in this port is invested to generate an income from share dividends and other sources. This is then paid monthly. Capital appreciation is targeted as well, but these portfolios are aimed primarily at older people (and others) who want/need their investment to generate a regular cash income.

In July my JPM Investing income portfolio generated £89.56 of income, which was duly paid into my bank account on 24 July 2026. That means I have now received tax-free income of £737.39 in 2026 and a total of £1,208.85 since I opened the account in June last year (just over a year ago). That’s a return on capital of a little over 4.90% to date. That is close to JPM’s original projected annual return of just under 5% per year for income ports at my chosen risk level (five).

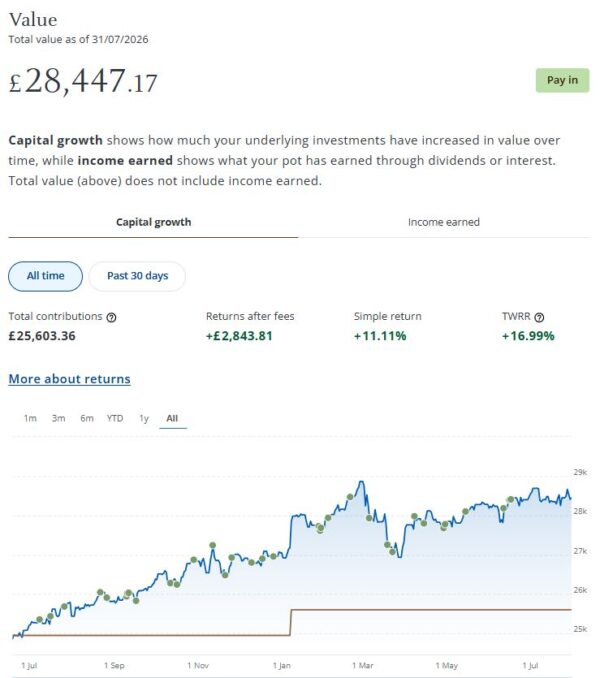
My income portfolio decreased slightly in value in July. It’s now worth £28,447 compared with £28,465 (rounded up) at the start of July, a fall of £18. As the screen capture below shows, however, my income port is still up by a respectable £2,843 (11.11%) after fees since I opened it last June.

JPM Income port August 2026

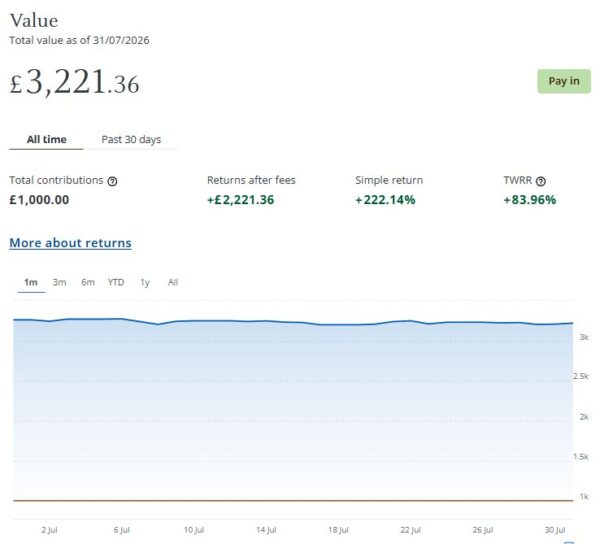
I still have a smaller, growth-oriented pot using JPM Investing’s Smart Alpha option. This is now worth £3,221 compared with £3,262 a month ago, a fall of £41. Here is a screen capture showing performance over the last month.

JPM Smart Alpha port August 2026

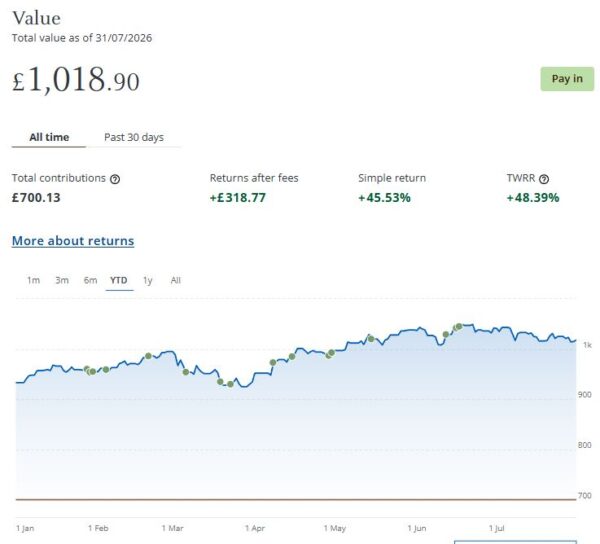
Finally, at the start of December 2023 I invested £500 in one of Nutmeg/JPM’s thematic portfolios (Resource Transformation). In March 2024 I also invested a further £200 from referral bonuses (something I no longer receive). As you can see from the YTD screen capture below, this portfolio is now worth £1,019 (rounded up) compared with £1,043 (rounded up) last month, a fall of £24.

JPM Thematic port August 26

Overall in July the value of my JPM investments fell by £83 or 0.25%. On the other hand, I did of course receive £89.56 in income from my income portfolio. In total, then, I am up by the princely sum of £6.56 for the month!

Excluding income generated (and allowing for the £2,000 I withdrew at the end of May this year) the overall value of my JPM investments has risen by £3,556 or 11.42% since the start of August 2025. If you add to this the £1,208.05 of income generated by my Income portfolio to date, that gives a total profit for the last 12 months of £4,764.05 – a pretty good return in these uncertain times.

The small drop in the value of my JPM investments in July is down mainly to the deteriorating situation in the Middle East. Obviously it’s disappointing, but some volatility is always to be expected with stock market investments. In the longer term they tend to even themselves out and typically outperform bank savings accounts (although that is never guaranteed). In general the worst thing you can do is panic and sell up when downturns occur. You are then crystallizing your losses rather than giving the markets time to recover. That is something I had cause to discuss last year in this blog post.

You can read my full original Nutmeg/JPM review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last nine years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Housemartin. As discussed in this post, the company rebranded last year from Assetz Exchange.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £334.80 in revenue from rental income. I have made a small net loss of £17.60 on property disposals. Capital growth generally has slowed, in line with UK property values generally.

At the time of writing, 23 of ‘my’ properties are showing gains, 6 are breaking even, and the remaining 18 are showing losses. My portfolio of 47 properties is currently showing a net decrease in value of £56.96. That means that overall (rental income minus capital value decrease and loss on disposal) I am up by £260.24. That’s still a respectable return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

  • A further consideration is that property investments on Housemartin are less likely to be affected by stock market downturns, as happened in March this year due to events in the Middle East. This again demonstrates the potential value of such investments for diversifying your portfolio during challenging times.

The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I usually reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my original review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].

In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

In January this year, as Oil Worldwide hadn’t exactly been setting the world alight, I decided to switch my entire investment in this to another smart portfolio, InTheGame. This port, focusing on the computer gaming industry, had been the top performer for some time in my eToro virtual portfolio.

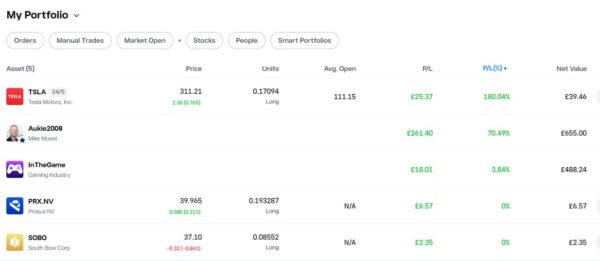
Unfortunately just as I switched away from Oil Worldwide, President Trump decided to invade Venezuela. This gave the oil industry a significant boost, which I would otherwise have benefited from. Meanwhile InTheGame went south, partly due to the war in the Middle East. At one point I was down by over 10% on this investment. Fortunately in the last four months InTheGame has made a recovery and is now in profit by 3.84%.

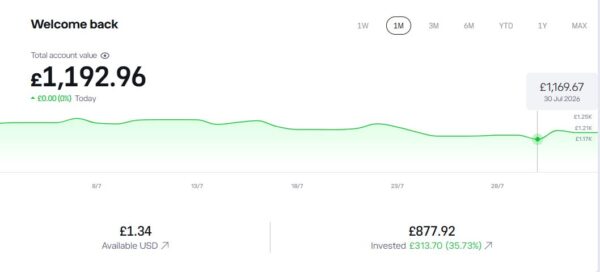
As you can see from the screen captures below, my original eToro investment (total value £888.36 in pounds sterling) is today worth £1,192.96, an overall increase of £304.60 or 34.29%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.

Etoro Main August 2026

Etoro port August 2026

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this post.

As mentioned above, my new investment in InTheGame is currently up by 3.84%. And my copy trading investment with Aukie2008 is showing an impressive overall profit of 70.49%. Of course, I have held this investment for quite a bit longer.

My Tesla shares, which I purchased as an afterthought with some spare cash I had in my account, are down a bit this month, but still showing an overall profit of over 180% since I bought them. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio.

Moving on, I published various posts on Pounds and Sense in July. I have listed below those that are still relevant.
In Small Changes That Could Save UK Households £1,000 a Year I set out some easy, everyday changes that could potentially have a big impact on your finances over the course of a year. As the article says, save a few pounds here and there, and before you know it you’ve kept an extra £1,000 in your pocket!

How to Know When Fruit and Veg Are Still Safe to Eat – And When They Should be Binned is a syndicated guest post by Primrose Freestone, whose work I have featured in Pounds and Sense before. Dr Freestone’s article concerns a subject that many older people (and others) on tight budgets may find of interest. It’s certainly something I have wondered about myself in the past.

And in Why Every Older Adult Should Consider the Shingles Vaccine (Shingrix) I look at an important subject every older adult should be aware of. Shingles is essentially a recurrence of a common childhood disease, chicken pox, but in older adults it can be a lot more serious. I recently had the new shingles vaccine (Shingrix) myself. In this article I explain why I felt it was important to do so, the side effects I experienced, and a potential beneficial side effect of the vaccine that has only quite recently come to light.

Finally, my cover image this month is a view of the lovely Welsh village/resort of Portmeirion (probably still best known as the venue for 1960s cult TV series The Prisoner starring Patrick McGoohan). I have visited Portmeirion many times before, but in July I fulfilled a long-standing ambition and actually stayed there for a few days. It wasn’t exactly a cheap break but well worth it. I may post an article/review in due course if there is sufficient interest.

I’ll close with my customary reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as it is now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out!

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. Twitter/X remains my primary social media platform, but I also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!
If you enjoyed this post, please link to it on your own blog or social media:
My Investments Update - July 2026

My Investments Update – July 2026

Here is my latest monthly update about my investments. You can read my June 2026 Investments Update here if you like.

I’ll begin as usual with my JP Morgan Personal Investing (previously Nutmeg) Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

As regular readers will know, in June last year I transferred most of the money in my former Nutmeg Fully Managed portfolio (just under £25,000) to a new Nutmeg Income Portfolio. I discussed this in detail in this post, but basically money in this port is invested to generate an income from share dividends and other sources. This is then paid monthly. Capital appreciation is targeted as well, but these portfolios are aimed primarily at older people (and others) who want/need their investment to generate a regular cash income.

In June my JPM Investing income portfolio generated a respectable £222.45 of income, which was duly paid into my bank account on 24 June 2026. That means I have now received tax-free income of £647.83 in 2026 and a total of £1,119.29 since I opened the account in June last year. That’s a return on capital of a little over 4.48% to date. That is pretty much in line with JPM’s original projected annual return of just under 5% for income ports at my chosen risk level (five).

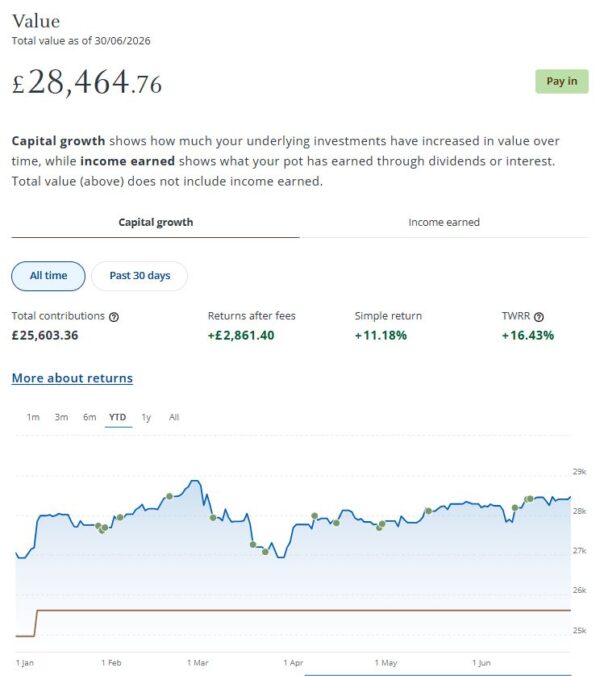
My income portfolio increased in value again in June. It’s now worth £28,465 (rounded up) compared with £28,282 at the start of June, a rise of £183. As the screen capture below shows, my income port is up by a respectable £2,861 (11.18%) after fees since I opened it last June (about a year ago).

JPM Income portfolio July 2026

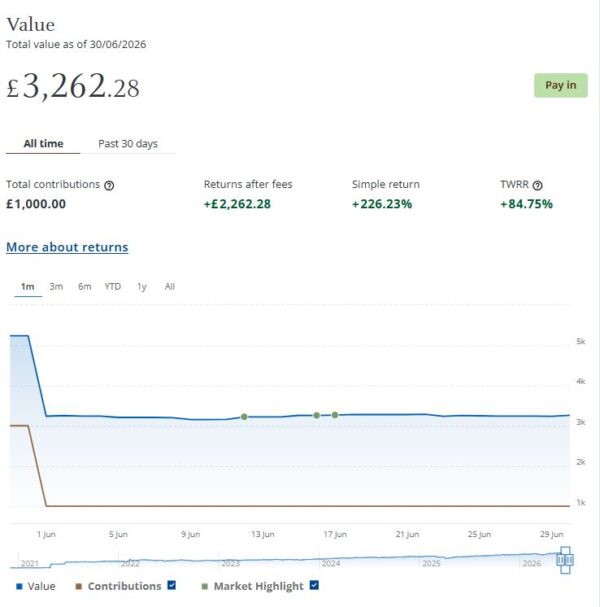
I still have a smaller, growth-oriented pot using JPM Investing’s Smart Alpha option. This is now worth £3,262 compared with £5,239 a month ago. As I mentioned last month, in early June I withdrew £2,000 from this portfolio to pay for some building work, so if you deduct this the value of the port has actually risen by £23. Here is a screen capture showing performance over the last month.

JPM Smart Alpha port July 26

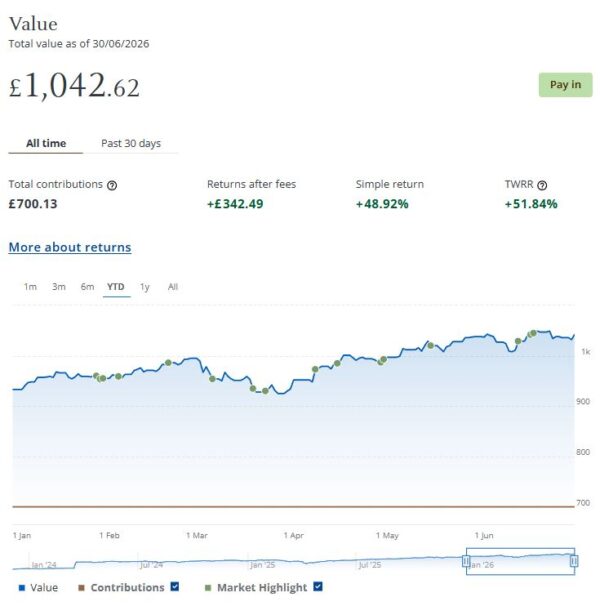
Finally, at the start of December 2023 I invested £500 in one of Nutmeg/JPM’s thematic portfolios (Resource Transformation). In March 2024 I also invested a further £200 from referral bonuses (something I no longer receive). As you can see from the YTD screen capture below, this portfolio is now worth £1,043 (rounded up) compared with £1,038 last month, a small rise of £5.

JPM thematic port July 2026

Overall in June (and allowing for the £2,000 I withdrew) the value of my JPM investments rose by £220 or 0.65%. In addition I did, of course, receive £222.45 in income from my income portfolio. In total, then, I am £442.45 up for the month.

Excluding income generated (and again allowing for the £2,000 withdrawal) the overall value of my JPM investments is up by £3,997 or 12.99% since the start of July 2025. If you add to this the £1,119.29 of income generated by my Income portfolio to date, that gives a total profit for the last 12 months of £5,272.84 – a pretty good return in these uncertain times.

Some volatility is always to be expected with stock market investments, but in the longer term they tend to even themselves out (and typically outperform bank savings accounts, although that is never guaranteed). In general the worst thing you can do is panic and sell up when downturns occur (as happened in March due to events in the Middle East). You are then crystallizing your losses rather than giving the markets time to recover. That is something I discussed last year in this blog post.

You can read my full original Nutmeg/JPM review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last nine years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Housemartin. As discussed in this post, the company rebranded last year from Assetz Exchange.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £328.30 in revenue from rental income. I have made a small net loss of £17.60 on property disposals. Capital growth generally has slowed, in line with UK property values generally.

At the time of writing, 21 of ‘my’ properties are showing gains, 5 are breaking even, and the remaining 18 are showing losses. My portfolio of 44 properties is currently showing a net decrease in value of £64.57. That means that overall (rental income minus capital value decrease and loss on disposal) I am up by £246.13. That’s still a respectable return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

  • A further consideration is that property investments on Housemartin are less likely to be affected by stock market downturns, as happened in March due to events in the Middle East. This again demonstrates the potential value of such investments for diversifying your portfolio during challenging times.

The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I usually reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my original review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].

In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

In January this year, as Oil Worldwide hadn’t exactly been setting the world alight, I decided to switch my entire investment in this to another smart portfolio, InTheGame. This port, focusing on the computer gaming industry, had been the top performer for some time in my eToro virtual portfolio.

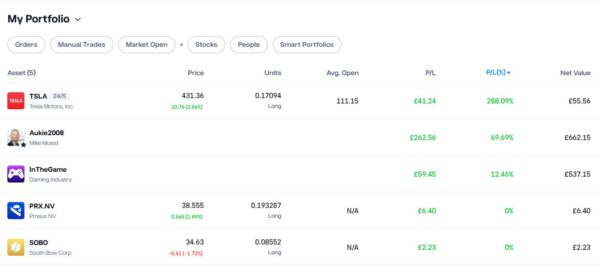
Unfortunately just as I switched away from Oil Worldwide, President Trump decided to invade Venezuela. This gave the oil industry a significant boost, which I would otherwise have benefited from. Meanwhile InTheGame went south, partly due to the war in the Middle East. At one point I was down by over 10% on this investment. Fortunately in the last three months InTheGame has made a good recovery and is now in profit by 12.45%.

As you can see from the screen captures below, my original eToro investment (total value £888.36 in pounds sterling) is today worth £1,264.92, an overall increase of £376.56 or 42.39%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.

EtoroMainJul26

EtoroPortJul26

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this post.

As mentioned above, my new investment in InTheGame is currently up by 12.45%. And my copy trading investment with Aukie2008 is showing an impressive overall profit of 69.49%. Of course, I have held this investment for quite a bit longer.

My Tesla shares, which I purchased as an afterthought with some spare cash I had in my account, are down marginally this month but still showing an overall profit of over 288% since I bought them. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio.

Moving on, I published various posts on Pounds and Sense in June. I have listed below those that are still relevant.
In Get a Free Share Worth up to £100 With Trading 212, I revealed that this promotional offer had reopened. If you haven’t done it before, you can get a free share worth up to £100 just by signing up to this popular share trading platform. My own free share in AMD is now worth £361.04! This offer closes on 9th July 2026. Learn more and sign up via my blog post.

And in The Best Realistic Side Hustles for Over-50s, I set out some easy side hustles that can work well for people in their fifties, sixties and beyond. If you’re looking for some simple, flexible ways to supplement your pension, build up a holiday fund, help cover rising household bills, or just earn some extra spending money, you’ll find a range of realistic ideas here.

Finally, I should mention that EDF Energy have enhanced their switching offer. Until 13th July 2026 you can get a FREE £75 (increased from £50) credited to your energy account when you switch to EDF via my referral link. Terms and conditions apply.

I’ll close with my customary reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as it is now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out!

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. Twitter/X remains my primary social media platform, but I also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!
If you enjoyed this post, please link to it on your own blog or social media:
Trading 212 review

Get a Free Share Worth Up To £100 With Trading 212

Offer Reopened!

Today I’m featuring a way you can get a free fractional share worth up to £100 by signing up (for the first time) with an online share trading platform called Trading 212.

Trading 212 is unusual in that it offers commission-free and fee-free share trading. As a special offer, until Tuesday 3rd November 2026 they are offering people new to the platform a free fractional share just for signing up via a referral link (such as the links in this post). The share you will get is chosen at random, but could be worth up to £100. You can either keep this share or sell it.

How to Sign Up

Signing up with Trading 212 is pretty straightforward. Just visit the Trading 212 website via any of the (referral) links in this post and follow the on-screen instructions to register. Note that you will be required to provide various items of information, including your date of birth, National Insurance number, annual income, employment status, and contact details. I understand that this is to meet their legal ‘Know Your Customer’ duty.

You will also need to indicate the type of account you want from the options available (see screen capture below).

Trading 212 accounts

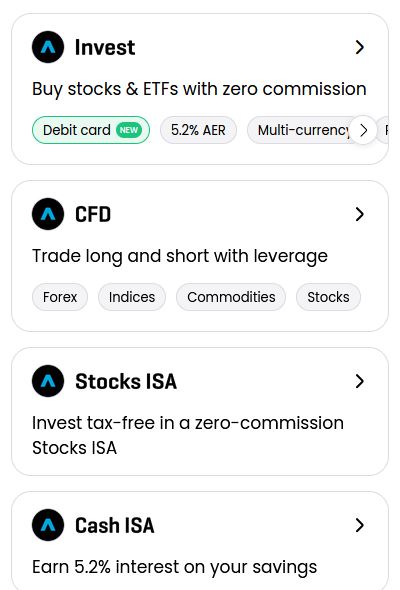
As you will see, the four account types on Trading 212 are Invest, CFD, Stocks ISA and Cash ISA. You can apply for any or all of these if you like.
CFD stands for Contract for Difference. CFDs are quite complex financial instruments and unless you know what you’re doing I recommend giving them a wide berth.

If you just want the free share my suggestion would be to tick the Stocks ISA box. An ISA is, of course, a tax-exempt Individual Savings Account. As from April 2024 you can open any number of ISA accounts in a year as long as you don’t exceed your annual £20,000 allowance.

If you have already used up your entire £20,000 this year, you should choose Invest instead to open a general investment account without any tax benefits. Obviously if you don’t want a Stocks ISA with Trading 212 for any other reason, you can choose this option as well.

  • For more information about the Trading 212 Cash ISA, see my review here. Be aware that you must open either an Invest account or a Stocks ISA account to qualify for a free share. Of course, there is nothing to stop you opening a Cash ISA account as well, but my recommendation would be to open an Invest or Stocks ISA account first.

Getting Your Free Share

There is one more step you will need to take in order to get your free share. You will need to deposit a minimum of £1 into your account. There are various ways you can do this, but i just used my debit card. There is no obligation to invest the £1 (or whatever you choose to deposit) and if you wish you can withdraw it once your free share has been credited.

The next business day you should receive an email confirming that a free fractional share has been added to your account. As mentioned above, this is allotted at random. If you’re lucky you might get one worth up to £100. Even if you get a less valuable one, though, it’s still a share for free. If you choose to keep it, it may rise in value. There may also be dividends payable in future (and credited to your account).

Selling Your Share

You can’t sell your share immediately. You have to wait three business days before doing so, but it is then just a matter of clicking the Sell button on your member’s dashboard.
The money will be credited to your Trading 212 account but you will have to wait 30 days before withdrawing it. So there may be a case for waiting to see if your share’s value goes up in that time. Of course, it could also go down!

In my case, I received a free share in the Ford Motor Company worth just under £8 at the time. Obviously this wasn’t as exciting as I might have hoped, but it was still – in effect – free money for almost no time or effort 😀

How Safe Is Trading 212?

Trading 212 is registered in England and Wales and authorized and regulated by the Financial Conduct Authority. In addition, all clients’ funds are kept separately in segregated bank accounts which are covered by the Financial Services Compensation Scheme. So even if the company itself were to go broke, any cash in your account would be protected up to a value of £120,000.
Of course, the FSCS guarantee doesn’t apply to the value of your stocks and shares, which can go down as well as up. All investments carry a risk of loss, although in the case of your free share you can never lose any more than the original cost, which was of course zero!

Referral Scheme

Any Trading 212 member can also refer new members while this offer is on. In that case, both you and the person concerned will receive one free fractional share worth up to £100. Obviously, the links in this blog post include my referral code – so if you register and get a free share, I will receive one also. Under the terms of the current offer you can get up to five free shares in this way. Five is the limit per person. Although you can still refer new members who will get a free share after this, as a referrer you won’t receive one as well. If and when the offer reopens in future, you will be able to refer more new members and get free shares again.

Final Thoughts

I first heard about Trading 212 a while ago, but wasn’t initially sure whether it was legit and here for the long term. And I thought the free share offer was, frankly, too good to be true. However, my own experiences have been entirely positive. My original free share in the Ford Motor Company was credited the next business day as promised and I received an email notifying me about it.

I can log in to my Trading 212 account any time to see how my Ford share is doing. I have also collected a few other shares from referrals. These include a share in AMD (the semiconductor company), which is currently worth an impressive £361.04, and one in Nike, which is worth £58.34. I still have my original Ford Motor Company share and it has risen in value to £11.19. I have also received several dividend payments from them. I haven’t sold any of my free shares yet but could of course do so any time I choose. I am not in any rush, as Trading 212 do not impose any platform or inactivity fees. 

Although in this post I have focused on the free share offer, Trading 212 is worth considering as a share-dealing platform too. In particular, the fact that it’s fee-free and commission-free means it is well suited for people who are dipping a toe in stocks and shares investment for the first time. By contrast, the dealing fees and commissions charged by some other share-trading platforms can make small share purchases prohibitively expensive. This review by Money Savvy Daddy looks at the pros and cons of Trading 212 as a share-dealing platform in a bit more detail.

In conclusion, I hope this post has inspired you to consider registering with Trading 212 to claim your free share. If you do, I hope you get a valuable one! Please let me know what share you receive in a comment below. And, as always, any other comments or questions are very welcome too.

  • Don’t forget, the current free share offer ends on Tuesday 3rd November 2026.

Disclosure: The links in this post include my referral code. If you click through and register as described above, I will receive a free share (as will you). Please note also that I am not a qualified financial adviser and nothing in this post should be construed as individual financial advice. Everyone should do their own ‘due diligence’ before investing and seek advice from a qualified financial adviser if in any doubt how best to proceed. All investment carries a risk of loss (although not in the case of free shares, obviously).

This is an update of my original post about this special offer.


If you enjoyed this post, please link to it on your own blog or social media:
My Investments Update - June 2026

My Investments Update – June 2026

Here is my latest monthly update about my investments. You can read my May 2026 Investments Update here if you like.

I’ll begin as usual with my JP Morgan Personal Investing (previously Nutmeg) Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

As regular readers will know, in June last year I transferred most of the money in my former Nutmeg Fully Managed portfolio (just under £25,000) to a new Nutmeg Income Portfolio. I discussed this in detail in this post, but basically money in this port is invested to generate an income from share dividends and other sources. This is then paid monthly. Capital appreciation is targeted as well, but these portfolios are aimed primarily at older people (and others) who want/need their investment to generate a regular cash income.

In May my JPM Investing income portfolio generated £85.59 of income, which was duly paid into my bank account on 24 May 2026. That means I have now received tax-free income of £425.38 in 2026 and a total of £896.84 since I opened the account in June last year. That’s a return on capital of a little over 3% to date. That is a bit less than I would have hoped based on JPM’s original projected annual return of just under 5% for income ports at my chosen risk level (five).

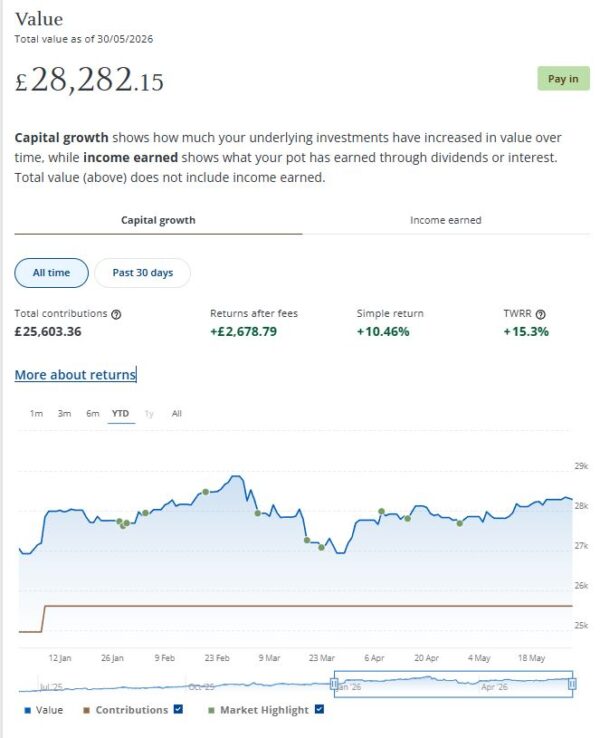
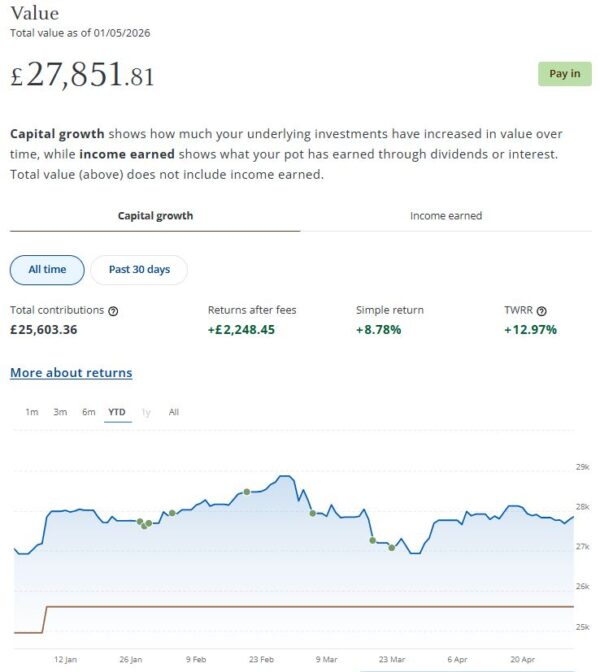
The better news is that my income portfolio increased in value again in May. It’s now worth £28,282 compared with £27,852 at the start of last month, a rise of £430. As the screen capture below shows, my income port is up by a respectable £2,679 (10.46%) after fees since I opened it last June (almost a year ago).

JPM Income port June 2026

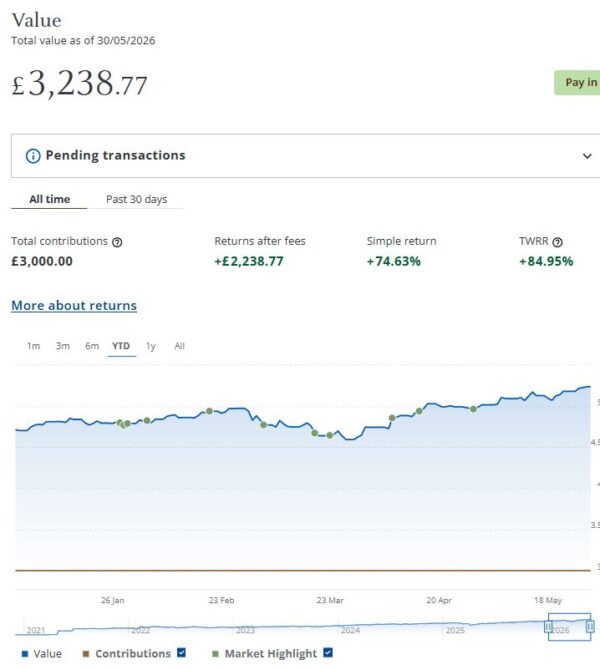
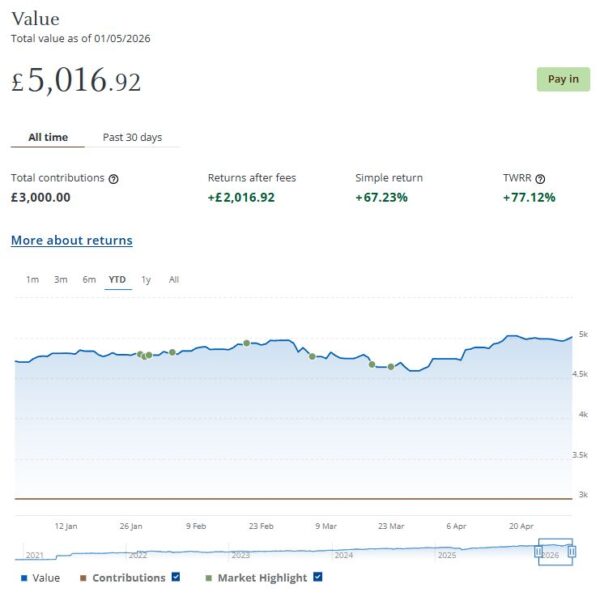
I still have a smaller, growth-oriented pot using JPM Investing’s Smart Alpha option. This is now nominally worth worth £5,239 (rounded up) compared with £5,017 a month ago, a rise of £222. I say nominally because I have just arranged to withdraw £2,000 from this pot to pay for some essential building work. The value shown in the screen capture reflects this, although the funds in question haven’t actually been sold yet. Here is a screen capture showing performance over the year to date.

JPM Smart Alpha port June 2026

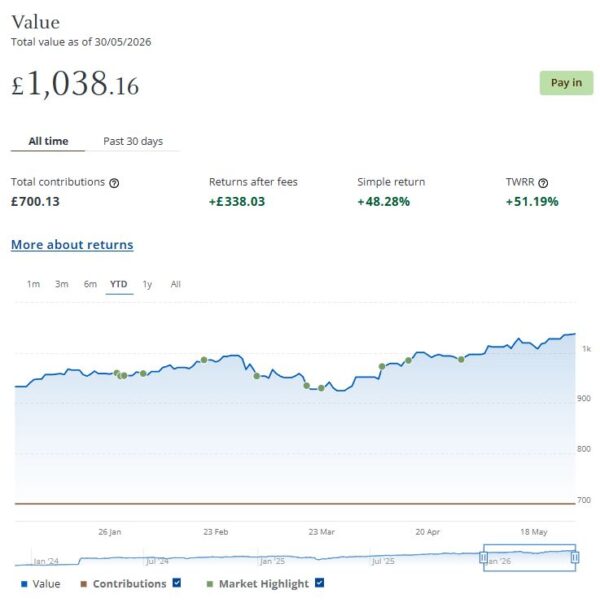
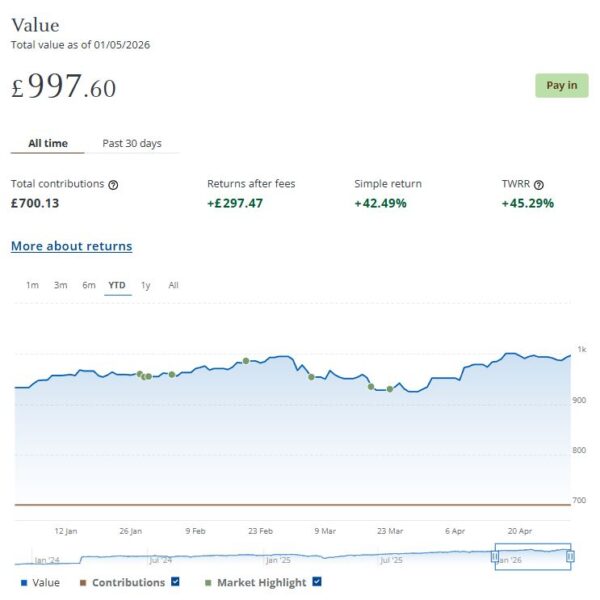
Finally, at the start of December 2023 I invested £500 in one of Nutmeg/JPM’s thematic portfolios (Resource Transformation). In March 2024 I also invested a further £200 from referral bonuses (something I no longer receive). As you can see from the YTD screen capture below, this portfolio is now worth £1,038 compared with £998 last month, a rise of £40.

JPM Thematic port June 2026

Overall in May the value of my JPM investments rose by £692 or 2.05%. In addition I did, of course, receive £85.59 in income from my income portfolio. In total, then, I am £777.59 up for the month.

Excluding income generated, the overall value of my JPM investments is up by £4,373 or 14.49% since the start of June 2025. If you add to this the £896.84 of income generated by my Income portfolio to date, that gives a total profit for the last 12 months of £5,269.84 – a pretty good return in these uncertain times.

Some volatility is always to be expected with stock market investments, but in the longer term they tend to even themselves out (and typically outperform bank savings accounts, although that is never guaranteed). In general the worst thing you can do is panic and sell up when downturns occur (as happened in March due to events in the Middle East). You are then crystallizing your losses rather than giving the markets time to recover. That is something I discussed last year in this blog post.

You can read my full original Nutmeg/JPM review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last nine years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Housemartin. As discussed in this post, the company rebranded last year from Assetz Exchange.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £320.71 in revenue from rental income. I have made a small net loss of £17.60 on property disposals. Capital growth generally has slowed, in line with UK property values generally.

At the time of writing, 18 of ‘my’ properties are showing gains, 7 are breaking even, and the remaining 21 are showing losses. My portfolio of 46 properties is currently showing a net decrease in value of £72.64. That means that overall (rental income minus capital value decrease and loss on disposal) I am up by £230.47. That’s still a respectable return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

  • A further consideration is that property investments on Housemartin are less likely to be affected by stock market downturns, as happened in March due to events in the Middle East. This again demonstrates the potential value of such investments for diversifying your portfolio during challenging times.

The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I usually reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my original review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].

In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

In January this year, as Oil Worldwide hadn’t exactly been setting the world alight, I decided to switch my entire investment in this to another smart portfolio, InTheGame. This port, focusing on the computer gaming industry, had been the top performer for some time in my eToro virtual portfolio.

Unfortunately just as I switched away from Oil Worldwide, President Trump decided to invade Venezuela. This gave the oil industry a significant boost, which I would otherwise have benefited from. Meanwhile InTheGame went south, partly due to the war in the Middle East. At one point I was down by over 10% on this investment. Fortunately in the last two months InTheGame has made an impressive recovery and is now in profit by 11.87%.

As you can see from the screen captures below, my original eToro investment (total value £888.36 in pounds sterling) is today worth £1,264.50, an overall increase of £376.14 or 42.34%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.

Etoro June 2026 main

Etoro June 2026 portfolio

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this post.

As mentioned above, my new investment in InTheGame is currently up by 11.87%. My copy trading investment with Aukie2008 also rose in value in May and is showing an impressive overall profit of 75.87%. Of course, I have held this investment for quite a bit longer.

My Tesla shares, which I purchased as an afterthought with some spare cash I had in my account, are also up this month and showing an overall profit of over 292% since I bought them. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio.

As an experiment, at the start of April 2025 I put £50 into an investment ISA with Trading 212. As mentioned in my blog post about dividend investing, I put it into the (Almost) Daily Dividends Portfolio, a ready-made portfolio or ‘pie’ on Trading 212. As you can see from the screen capture below, my portfolio is now worth £59.98. That’s a rise of £0.41 since last month and an increase of £10.39 or 20.7% since I opened it just over a year ago. It has even accrued a grand total of £1.20 in dividends, most of which has now been (automatically) reinvested.

Trading 212 Dividends ISA June 26


I am quite impressed with how this investment has been faring, despite the small amount I put in (which means I may be missing out on some smaller dividends). If I increased my investment I would almost certainly become eligible for more dividends, and even more the longer I remain invested. Of course, I do now have an income-focused portfolio with JPM Investing as well (see above), so realistically it’s unlikely I shall be investing any more in this account for the foreseeable future. I have therefore decided to stop including it in my monthly updates from now on. 


Moving on, I published various posts on Pounds and Sense in May. I have listed below those that are still relevant.

In Moneysaving Perks and Discounts for Retired People I set out a variety of perks and discounts available specifically for retired and older people in the UK. Some are well known, while others fly under the radar. Either way, taking advantage of them can make a real difference to your finances over the course of a year. Find out more in the article.

And in Here’s Why Prolific Academic Could be the Ideal Side Hustle for Seniors I discussed this online platform that connects researchers – mainly from universities and other academic institutions – with members of the public willing to take part in research studies. I explained why I think this sideline-earning opportunity is ideally suited to older people. As the article says, it’s flexible, straightforward, low-pressure and genuinely interesting. You can do as much or as little as you like, earn a bit of extra money, help academic research and keep mentally active at the same time. Prolific Academic is my personal favourite side hustle these days!

Finally, in case you’re wondering, my cover image this month shows the lovely Italianate village of Portmeirion in North Wales. It’s probably still best known as the setting for 1960s cult TV show ‘The Prisoner’. I have just booked a short break in the village for later in the summer, fulfilling a long-standing ambition not just to visit Portmeirion but actually stay there. I wonder if I will be summoned to Number 2’s house during my visit!

I’ll close with my customary reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as it is now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out!

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. Twitter/X remains my primary social media platform, but I also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!

If you enjoyed this post, please link to it on your own blog or social media:
My Investments Update May 2026

My Investments Update – May 2026

Here is my latest monthly update about my investments. You can read my April 2026 Investments Update here if you like.

I’ll begin as usual with my JP Morgan Personal Investing (previously Nutmeg) Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

As regular readers will know, in June last year I transferred most of the money in my former Nutmeg Fully Managed portfolio (just under £25,000) to a new Nutmeg Income Portfolio. I discussed this in detail in this post, but basically money in this port is invested to generate an income from share dividends and other sources. This is then paid monthly. Capital appreciation is targeted as well, but these portfolios are aimed primarily at older people (and others) who want/need their investment to generate a regular cash income.

In April my JPM Investing income portfolio generated £66.11 of income, which was duly paid into my bank account on 24 April 2026. That means I have now received tax-free income of £339.79 in 2026 and a total of £811.25 since I opened the account in June last year. That’s a return on capital of just over 3% to date. That is – to be honest – a bit less than I would have hoped based on JPM’s original projected annual return of just under 5% for income ports at my chosen risk level (five).

The better news is that my income portfolio increased in value in April (after its bigger fall in March). It’s now worth £27,852 compared with £27,320 at the start of last month, a rise of £532. You don’t need to be an investment expert to know that the volatility recently is due mainly to events in the Middle East. As I always say, you do have to expect ups and downs when investing. As the screen capture below shows, my income port is still up by a respectable £2,248 (8.78%) after fees since I opened it last June.

JPM Income Port May 26

I still have a smaller, growth-oriented pot using JPM Investing’s Smart Alpha option. This is now worth £5,017 (rounded up) compared with £4,646 a month ago, a rise of £371. Here is a screen capture showing performance over the year to date.

JPM Smart Alpha May 26

Finally, at the start of December 2023 I invested £500 in one of Nutmeg/JPM’s thematic portfolios (Resource Transformation). In March 2024 I also invested a further £200 from referral bonuses (something I no longer receive). As you can see from the YTD screen capture below, this portfolio is now worth £998 compared with £934 last month, a rise of £64.

Overall in April the value of my JPM investments rose by £967 or 3.02%. In addition I did, of course, receive £66.11 in income from my income portfolio. In total, then, I am £1,033.11 up for the month.

Excluding income generated, the overall value of my JPM investments is up by £4,630 or 15.72% since the start of May 2025. If you add to this the £811.25 of income generated by my Income portfolio to date, that gives a total profit for the last 12 months of £5,441.25 – a pretty good return in these uncertain times.

As I said above, some volatility is always to be expected with stock market investments, but in the longer term they tend to even themselves out (and typically outperform bank savings accounts, although that is never guaranteed). In general the worst thing you can do is panic and sell up when downturns occur (as happened in March). You are then crystallizing your losses rather than giving the markets time to recover. This is something I discussed last year in this blog post. Obviously nobody knows what will happen in the Middle East, but hopefully some sort of resolution will occur soon, if only because US President Trump desperately needs an exit strategy to pacify his critics back home. Once this happens, we will hopefully see world stock markets stabilize again. Though there is of course no guarantee about this.

You can read my full original Nutmeg/JPM review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last nine years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Housemartin. As discussed in this post, the company rebranded last year from Assetz Exchange.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £315.21 in revenue from rental income. I have made a small net loss of £17.60 on property disposals. Capital growth generally has slowed, in line with UK property values generally.

At the time of writing, 17 of ‘my’ properties are showing gains, 7 are breaking even, and the remaining 20 are showing losses. My portfolio of 44 properties is currently showing a net decrease in value of £71.59. That means that overall (rental income minus capital value decrease and loss on disposal) I am up by £243.62. That’s still a respectable return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

  • A further consideration is that property investments on Housemartin are less likely to be affected by stock market downturns, as happened in March due to the war in the Middle East. This again demonstrates the potential value of such investments for diversifying your portfolio during challenging times.

The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I usually reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my original review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].

In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

In January this year, as Oil Worldwide hadn’t exactly been setting the world alight, I decided to switch my entire investment in this to another smart portfolio, InTheGame. This port, focusing on the computer gaming industry, has been the top performer for some time in my eToro virtual portfolio.

Unfortunately just as I switched away from Oil Worldwide, President Trump decided to invade Venezuela. This gave the oil industry a significant boost, which I would otherwise have benefited from. Meanwhile InTheGame went south, partly due to the war in the Middle East. At one point I was down by over 10% on this investment. Fortunately in the last few weeks InTheGame has made an impressive recovery and is now in profit by 7.91%.

As you can see from the screen captures below, my original eToro investment (total value £888.36 in pounds sterling) is today worth £1,177.13, an overall increase of £288.77 or 25.77%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.

Etoro Home May 2026

Etoro port May 2026

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this post.

As mentioned above, my new investment in InTheGame is currently up by 7.91%. My copy trading investment with Aukie2008 also rose in value in April and is showing an impressive overall profit of 69.10%. Of course, I have held this investment for quite a bit longer.

My Tesla shares, which I purchased as an afterthought with some spare cash I had in my account, are also up this month and showing an overall profit of over 251% since I bought them. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio.

As an experiment, at the start of April 2025 I put £50 into an investment ISA with Trading 212. As mentioned in my blog post about dividend investing, I put it into the (Almost) Daily Dividends Portfolio, a ready-made portfolio or ‘pie’ on Trading 212. As you can see from the screen capture below, my portfolio is now worth £59.98. That’s a small rise of £0.12 since last month and an increase of £9.98 or 19.9% since I opened it just over a year ago. It has even accrued a grand total of £1.16 in dividends, most of which has now been (automatically) reinvested.

Trading 212 Dividends port May 26


I am quite impressed with how this investment has been faring, despite the small amount I put in (which means I may be missing out on some smaller dividends). If I increased my investment I would almost certainly become eligible for more dividends, and even more the longer I remain invested. If I had any spare money at the moment, I would consider doing this. Of course, I do now have an income-focused portfolio with JPM Investing as well (see above).


Moving on, I published various posts on Pounds and Sense in April. I have listed below those that are still relevant.

In What is the Blue Light Card – And How Can It Help You Save Money? I discussed this discount scheme for people working in the emergency services and various other public services. For a modest fee (under £2.50 a year) you can access discounts on everything from restaurants to holidays, concerts and sporting events to insurance. You may also be eligible if you are retired from a qualifying occupation. Find out more in this article.

I also posted Pound-Cost Averaging – A Smart Strategy for Investing in Turbulent Times. In this article I explained how this simple investing strategy works and why it may be particularly relevant in these turbulent times.

Finally in April I published Why Now Could Be the Ideal time to Take Advantage of Your New Tax-Free ISA Allowance. From the start of the new tax year on 6 April 2026, everyone has a new £20,000 tax-free ISA allowance. In this article I revealed why you might want to take advantage of at least some of this allowance sooner rather than later.

I’ll close with my customary reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as it is now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out!

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. Twitter/X remains my primary social media platform, but I also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!

If you enjoyed this post, please link to it on your own blog or social media:
Use Your New ISA Allowance

Why Now Could Be the Ideal Time to Take Advantage of Your New Tax-Free ISA Allowance

As of 6 April 2026, UK investors have a fresh chance to supercharge their savings and investments with a new £20,000 Individual Savings Account (ISA) allowance.

ISAs represent a golden opportunity for investors to make their money work harder while shielding their returns from the taxman. With tax-free allowances for income frozen until April 2028 and tax-free thresholds for dividend tax and capital gains tax being slashed in the last few years, it’s more important than ever to protect your hard-earned savings and investments within an ISA wrapper.

To maximize the benefits of the new 2026/27 allowance, there’s a strong case for acting swiftly and using at least part of your £20,000 ISA allowance sooner rather than later. This is due to the power of compounding. By investing early, you give your money more time to grow, benefiting from the potential snowball effect of returns generating further returns. So the sooner you invest that £20,000 (assuming you are fortunate enough to have it) the more opportunity it has to multiply over time.

In addition to the tax-free ISA allowance remaining at a relatively generous £20,000 (for now – see below), the rules surrounding ISAs have undergone a welcome relaxation in recent years. One of the most significant changes is the ability to open more than one ISA of the same type (e.g. a stocks and shares ISA) with different providers in the same tax year. This means investors are no longer limited to a single provider for each type of ISA, giving them greater flexibility and choice in managing their investments.

Previously, investors were restricted to opening one cash ISA, one stocks and shares ISA and one innovative finance ISA (IFISA) per tax year. This restriction could prove frustrating for those seeking to diversify their investments or take advantage of new opportunities as the tax year progressed. Now, with the freedom to open multiple ISAs of the same type, investors can shop around for the best rates, terms and investment options without being limited to a single provider for each ISA type. They can also move some or all of their money from one provider to another without jeopardizing its tax-free status.

It’s important to remember, however, that while the rules have been relaxed, the overall annual ISA allowance remains fixed at £20,000. This means that any contributions made across multiple ISAs of any type will count towards your total allowance for the tax year. You should still therefore take care not to exceed the annual limit, to avoid any potential tax charges.

  • Note that from April 2027 the Cash ISA allowance has been reduced from £20,000 to £12,000 per year for savers under the age of 65. Until then it remains at £20,000 a year for all savers, though. 

Cash ISAs offer a secure and accessible way to save, providing a tax-free environment for your savings with the added benefit of easy access to your funds when needed. Meanwhile, stocks and shares ISAs open the door to potential higher returns by investing in a wide range of assets such as equities, bonds, and funds, albeit with a higher level of risk. With a stocks and shares ISA you will never incur any liability for dividend tax, capital gains tax or income tax, even if your investments perform exceptionally well. Of course, there is no guarantee this will happen, but over a longer period stock market investments have typically outperformed cash savings, often by a substantial margin. IFISAs (e.g. from Housemartin, with whom I invest myself) allow you to invest is property crowdfunding and other forms of peer-to-peer finance. They are more specialized, but may appeal to some investors looking to further diversify their portfolios.

  • In recent years I have invested much of my own annual ISA allowance in a stocks and shares ISA with JP Morgan Personal Investing (previously Nutmeg), a robo-manager platform that has produced good returns for me. You can read how my Housemartin and JPM investments (and others) are faring in my monthly investment updates such as this one.


Closing Thoughts

The start of a new financial year is a good time for UK investors to review their savings and investment strategies. Whether you’re looking to start a new ISA or maximize your contributions to existing accounts, taking action early can set you on the path to optimizing your returns from this important tax-saving opportunity.

By investing sooner rather than later and taking advantage of the increased flexibility in ISA provider options, savers and investors can make the most of their money while minimizing their tax liabilities. So grasp this opportunity to build your wealth and protect it from the taxman today!

As always, if you have any comments or questions about this post, please do leave them below.

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss.


If you enjoyed this post, please link to it on your own blog or social media:
My Investments Update - April 2026

My Investments Update – April 2026

Here is my latest monthly update about my investments. You can read my March 2026 Investments Update here if you like.

I’ll begin as usual with my JP Morgan Personal Investing (previously Nutmeg) Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

As regular readers will know, in June last year I transferred most of the money in my former Nutmeg Fully Managed portfolio (just under £25,000) to a new Nutmeg Income Portfolio. I discussed this in detail in this post, but basically money in this port is invested to generate an income from share dividends and other sources. This is then paid monthly. Capital appreciation is targeted as well, but these portfolios are aimed primarily at older people (and others) who want/need their investment to generate a regular cash income.

In January my JPM Investing income portfolio generated £75.54 of income, which was duly paid in to my bank account on 24 March 2026. That means I have now received tax-free income of £273.68 in 2026 and a total of £745.14 since I opened the account in June last year. That’s about what I would have expected based on JPM’s projected annual return of just under 5% for income ports at my chosen risk level (five).

The less good news is that my income portfolio declined in value in March. It’s now worth £27,320 compared with £28,866 at the start of last month, a fall of £1,546. You don’t need to be an investment expert to know that this is mainly due to events in the Middle East. Nearly all of my share-based investments have been affected by this. Clearly it is disappointing, but as I always say, you do have to expect ups and downs when investing. As the screen capture below shows, my income port is still up by a respectable £1,716.97 (6.71%) after fees since I opened it last June.

JPM Income Portfolio April 2026

I still have a smaller, growth-oriented pot using JPM Investing’s Smart Alpha option. This is now worth £4,606 compared with £4,974 (rounded up) a month ago, a fall of £368. Here is a screen capture showing performance over the last year.

Nutmeg Smart Alpha port April 2026

Finally, at the start of December 2023 I invested £500 in one of Nutmeg/JPM’s thematic portfolios (Resource Transformation). In March 2024 I also invested a further £200 from referral bonuses (something I no longer receive). As you can see from the one-year screen capture below, this portfolio is now worth £934 compared with £996 (rounded up) last month, a decrease of £62.

Nutmeg THematic port April 2026

Overall in March the value of my JPM investments fell by £1,976 or 5.55%. Against that I did, of course, receive £75.54 in income from my income portfolio. In total, then, I am £1900.46 down for the month.

On a more positive note, excluding income generated, the overall value of my JPM investments is still up by £3,385 or 11.47% since the start of April 2025. If you add to this figure the £745.14 of income generated by my Income portfolio to date, that gives a total profit for the last 12 months of £4,130.14 – still not a bad return in these uncertain times.

As I said above, some volatility is always to be expected with stock market investments, but in the longer term they tend to even themselves out (and typically outperform bank savings accounts, although that is never guaranteed). In general the worst thing you can do is panic and sell up when downturns occur (as happened last month). You are then crystallizing your losses rather than giving the markets time to recover. This is something I discussed last year in this blog post. Obviously nobody knows what will happen in the Middle East, but hopefully some sort of resolution will occur soon, if only because President Trump desperately needs an exit strategy to pacify his critics back home. Once a bit more stability returns to the region, we will hopefully see world stock markets rise again. Though of course there is no guarantee about this.

You can read my full original Nutmeg/JPM review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last nine years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Housemartin. As discussed in this post, the company rebranded last year from Assetz Exchange.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £309.64 in revenue from rental income. I have made a small net loss of £20.25 on property disposals. Capital growth generally has slowed, in line with UK property values generally.

At the time of writing, 17 of ‘my’ properties are showing gains, 3 are breaking even, and the remaining 24 are showing losses. My portfolio of 44 properties is currently showing a net decrease in value of £76.05. That means that overall (rental income minus capital value decrease and loss on disposal) I am up by £213.34. That’s still a respectable return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

  • A further consideration is that property investments on Housemartin are less likely to be affected by stock market downturns, as happened in March due to the war in the Middle East. This again demonstrates the potential value of such investments for diversifying your portfolio during challenging times.

The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I usually reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my original review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].

In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

In January this year, as Oil Worldwide hadn’t exactly been setting the world alight, I decided to switch my entire investment in this to another smart portfolio, InTheGame. This port, focusing on the computer gaming industry, has been the top performer for some time in my eToro virtual portfolio.

Unfortunately just as I switched away from Oil Worldwide, President Trump decided to invade Venezuela. This gave the oil industry a significant boost, which I would otherwise have benefited from. Meanwhile InTheGame has gone south, partly due to the recent fall in AI stocks along with the war in the Middle East. At the time of writing the value of my investment in this has fallen by nearly 17%. Hey ho! This does of course demonstrate that there are never any guarantees when investing and unexpected events can thwart the best-laid plans…

As you can see from the screen captures below, my original eToro investment (total value £888.36 in pounds sterling) is today worth £1,070.78, an overall increase of £182.42 or 20.53%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.

Etoro Home April 2026

Etoro port April 26

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this post.

As mentioned above, my new investment in InTheGame is currently down by nearly 17%. My copy trading investment with Aukie2008 also fell in value in March, but it’s still showing an impressive overall profit of 56.36%. Of course, I have held this investment for quite a bit longer.

My Tesla shares, which I purchased as an afterthought with some spare cash I had in my account, are also down this month, but still showing an overall profit of over 234% since I bought them. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio.

As an experiment, at the start of April last year I put £50 into an investment ISA with Trading 212. As mentioned in my blog post about dividend investing, I put it into the (Almost) Daily Dividends Portfolio, a ready-made portfolio or ‘pie’ on Trading 212. As you can see from the screen capture below, my portfolio is now worth £59.87. That’s a decrease of £1.97 since last month but an increase of £9.87 or 19.7% over the eleven-month period since I opened it. It has even accrued a grand total of £1.08 in dividends, most of which has now been (automatically) reinvested.

Trading 212 Dividends ISA April 26

I am quite impressed with how this investment has been faring, despite the small amount I put in (which means I may be missing out on some smaller dividends). If I increased my investment I would almost certainly become eligible for more dividends, and even more the longer I remain invested. If I had any spare money at the moment, I would consider doing this. Of course, I do now have an income-focused portfolio with JPM Investing as well (see above).


Moving on, I published various posts on Pounds and Sense in March. I have listed below those that are still relevant.

In Beat the Postage Stamp Price Rise, I pointed out that the cost of stamps is rising (again) on Tuesday 7 April 2026. That will be the SEVENTH rise in the price of first class stamps in just four years! Standard and large-letter stamps don’t have values printed on them and will still be valid after the April price rise comes in, so my top tip is to stock up now while stamps are still at the old price.

I also posted an updated version of Get a Free Share Worth up to £100 with Trading 212. Anyone who hasn’t done this before can get a free share worth up to £100 just by signing up for a new Trading 212 investment account via my link. The current offer closes on Tuesday 28th April 2026.

Also in March I published Are River Cruises Suitable for Solo Travellers. This was a follow-up to my earlier posts about how to save money on cruise holidays and the pros and cons of river cruises (for older travellers in particular). In this post I addressed a question asked by several readers as to whether river cruises are a good choice for solo travellers. The article sets out the pros and cons as I see them. My view, as expressed in the article, is that they can be, but it does depend on your travel style and budget.

What Is An Annuity – And Who Should Consider Buying One? discusses a subject that confuses many people. In simple terms, an annuity is a financial product that converts a lump sum of money – typically from your pension pot – into a guaranteed regular income for life (or for a fixed period). You buy an annuity from an insurance company. In return for handing over some or all of your pension savings, they promise to pay you a regular income, usually monthly, for the rest of your life. In the article I look at the pros and cons of annuities, and whom they are (and aren’t) likely to be suitable for.

How to Save Money on Travel Insurance covers a subject on many people’s minds at this time of year. Travel insurance is one of those expenses that can feel like a grudge purchase – until you need it. For UK travellers, especially older holidaymakers, having adequate cover is essential. In this article I set out some ways you may be able to save on travel insurance without compromising your safety or security. I also discuss saving money on travel insurance as an older person, and the issues that can be caused by war and civil unrest (especially relevant for destinations in or near the Middle East at the moment).

Finally, in March I published Don’t Miss Out – Use Your £20,000 ISA Allowance Before It’s Too Late! As I say in the article, the end of the tax year on 5 April 2026 is fast approaching and so is the deadline to utilize the annual tax-free Individual Savings Account (ISA) allowance. Unless you take action in the next few days, this opportunity to maximize your tax-free savings for the 2025/26 financial year will be gone for ever.

  • And speaking of deadlines, time is also running out to take advantage of EDF Energy‘s enhanced switching offer. Until 6 April 2026 you can get a FREE £75 (increased from £50) credited to your energy account when you switch to EDF via my link at https://edfenergy.com/quote/refer-a-friend/sunny-koala-9462. Terms and conditions apply.

I’ll close with my customary reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as it is now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out!

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. Twitter/X remains my primary social media platform, but I also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!

If you enjoyed this post, please link to it on your own blog or social media: