My Investments Update – October 2026
Here is my latest monthly update about my investments. You can read my September 2026 Investments Update here if you like.
I’ll begin as usual with my JP Morgan Personal Investing (previously Nutmeg) Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).
As regular readers will know, in June last year I transferred most of the money in my former Nutmeg Fully Managed portfolio (just under £25,000) to a new Nutmeg Income Portfolio. I discussed this in detail in this post, but basically money in this port is invested to generate an income from share dividends and other sources. This is then paid monthly. Capital appreciation is targeted as well, but these portfolios are aimed primarily at older people (and others) who want/need their investment to generate a regular cash income.
In September my JPM income portfolio generated £60.45 of income, which was duly paid into my bank account on 24 September 2026. That means I have now received (tax-free) income of £954.86 in 2026 and a total of £1,426.32 since I opened the account in June last year. That’s a return on capital of nearly 5% a year to date. That is in line with JPM’s original projected annual return for income ports at my chosen risk level (five).
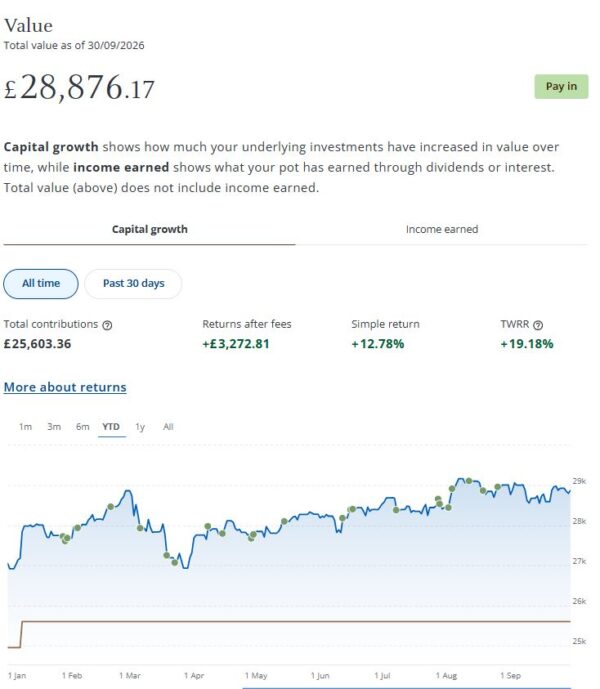
My income portfolio fell slightly in value in September. It’s now worth £28,876 compared with £29,010 at the end of August, a drop of £134. As the screen capture below shows, my income port is still up by a respectable £3,272.81 (12.78%) after fees since I opened it in June 2025.
- As a matter of interest, I recently received an email from JPM saying they are making some adjustments to income portfolios with the aim of increasing monthly payments. They say the trade-off may be that if there is a fall in the markets, the value of these portfolios may fall a bit further and faster than it would have before. I don’t really have a problem with this, as my priority with this port is income generation rather than capital growth. But obviously I will continue to monitor it carefully.
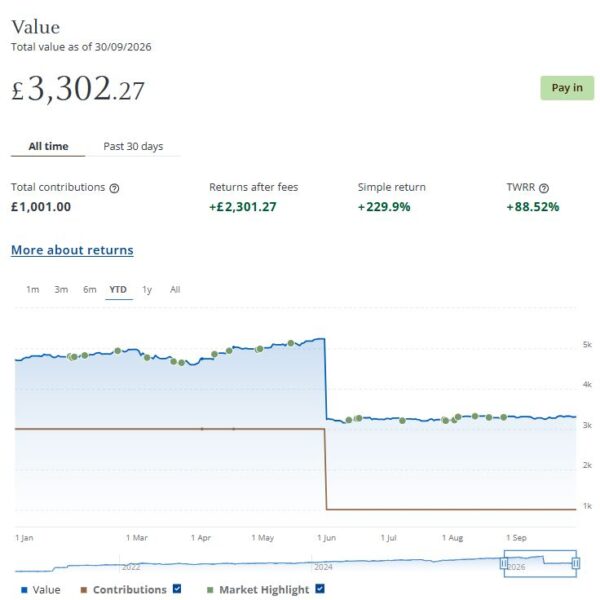
I still have a smaller, growth-oriented pot using JPM Investing’s Smart Alpha option. This is now worth £3,302 compared with £3,313 a month ago, a fall of £11. Here is a screen capture showing performance over the year to date. As you may recall, I sold £2,000 worth of this portfolio in May this year to pay for some building work.
Finally, at the start of December 2023 I invested £500 in one of Nutmeg/JPM’s thematic portfolios (Resource Transformation). In March 2024 I also invested a further £200 from referral bonuses (something I no longer receive). As you can see from the YTD screen capture below, this portfolio is now worth £1,048 (rounded up) compared with £1,055 last month, a fall of £7.
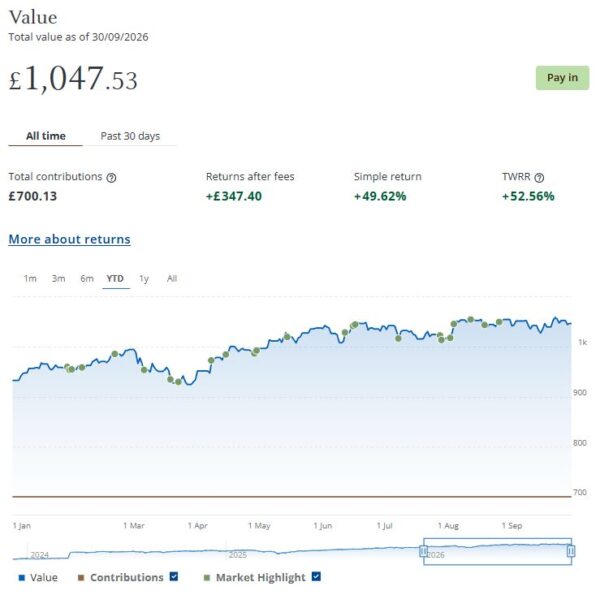
Overall in September the value of my JPM investments fell by £152 or 0.46%. In addition, I did of course receive £60.45 in income from my income portfolio. In total, then, I was down by £106 for the month.
Excluding income generated (and allowing for the £2,000 I withdrew in May this year) the overall value of my JPM investments has risen by £2,803 since the start of October 2025. If you add to this the £1,352.74 of income generated by my Income portfolio since then, that gives a total profit for the last 12 months of £4,155.74 – a pretty good return in these uncertain times. Another way of looking at this (which I like!) is that the £2,000 I withdrew in May this year has been comfortably covered by the growth in value of my JPM investments (and income generated) over the last year.
Obviously it’s important not to read too much into a single month’s performance. Ups and downs are very much to be expected with stock market investments. In the longer term they tend to even themselves out and typically outperform bank savings accounts (though that’s never guaranteed). In general the worst thing you can do is panic and sell up when downturns occur. You are then crystallizing your losses rather than giving the markets time to recover. That is something I had cause to discuss last year in this blog post.
You can read my full original Nutmeg/JPM review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last nine years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.
- As mentioned, Nutmeg have rebranded as J.P. Morgan Personal Investing and their website is now at www.personalinvesting.
jpmorgan.com.
Moving on, I also have investments with P2P property investment platform Housemartin. As discussed in this post, the company rebranded last year from Assetz Exchange.
My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.
Since I opened my account, my HM portfolio has generated a respectable £346.48 in revenue from rental income. I have made a small net loss of £17.60 on property disposals. Capital growth generally has slowed, in line with UK property values generally.
At the time of writing, 24 of ‘my’ properties are showing gains, 5 are breaking even, and the remaining 19 are showing losses. My portfolio of 48 properties is currently showing a net decrease in value of £59.54. That means that overall (rental income minus capital value decrease and loss on disposal) I am up by £269.34. That’s still a respectable return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.
- A further consideration is that property investments on Housemartin are less likely to be affected by stock market downturns, as happened in March this year due to events in the Middle East. This again demonstrates the potential value of such investments for diversifying your portfolio during challenging times.
The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).
To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.
- As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I usually reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.
My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my original review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].
In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).
In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.
In January this year, as Oil Worldwide hadn’t exactly been setting the world alight, I decided to switch my entire investment in this to another smart portfolio, InTheGame. This port, focusing on the computer gaming industry, had been the top performer for some time in my eToro virtual portfolio.
Unfortunately just as I switched away from Oil Worldwide, President Trump decided to invade Venezuela. This gave the oil industry a significant boost, which I would otherwise have benefited from. Meanwhile InTheGame went south, partly due to the war in the Middle East. At one point I was down by over 10% on this investment. Fortunately in the last few months InTheGame has made a good recovery and is now in profit by 12.55%.
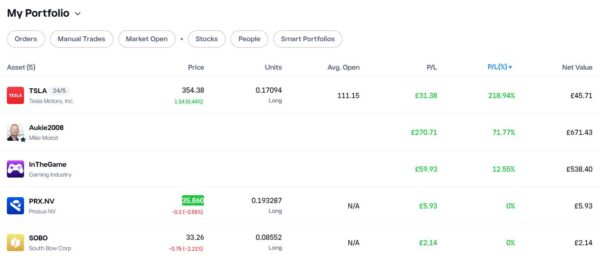
As you can see from the screen captures below, my original eToro investment (total value £888.36 in pounds sterling) is today worth £1,264.96, an overall increase of £376.60 or 42.39%.
- Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.
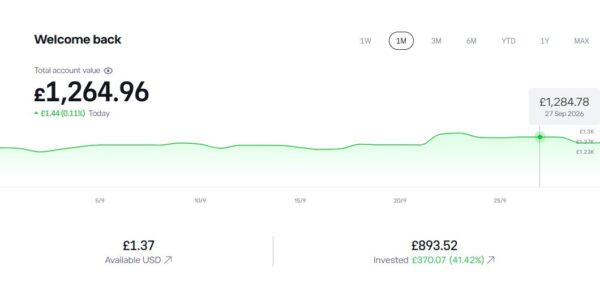
You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this post.
As mentioned above, my new investment in InTheGame is currently up by 12.55%. And my copy trading investment with Aukie2008 is showing an impressive overall profit of 71.77%. Of course, I have held this investment for quite a bit longer.
My Tesla shares, which I purchased as an afterthought with some spare cash I had in my account, are also up this month. They are now showing an overall profit of over 219% since I bought them. If only I had put a bit more money into this!
You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio.
- If you would like more information about setting up an eToro account, please click on this no-obligation website link [refer-a-friend]. Don’t forget that you also get a free $100,000 virtual portfolio, which you can use to experiment with trading and investing strategies. I have certainly earned a lot from mine.
Moving on, 
How Eating a Handful of Nuts Each Day May Help Lower Your Blood Pressure is a syndicated guest post from Shireen Kassam, University of Winchester and Dagfinn Aune, Imperial College London. It’s on a subject I believe many older readers (in particular) may find of interest. High blood pressure is the single biggest metabolic risk factor for early death, driving diseases such as heart attacks, strokes, kidney failure and dementia. This article reveals how adding just one serving of nuts into your daily diet may lower your risk.
In Get Your Will Written Free of Charge in October I discussed Free Wills Month. This brings together a group of well-respected charities to offer members of the public aged 55 and over the opportunity to have their wills written or updated free using participating solicitors across the UK. Appointments are limited and on a first come, first served basis, so it’s best to apply as soon as possible to avoid disappointment. Read my post for more info.
In UK Government Bonds – Are Gilts Worth Considering Now? I looked at why gilts have been attracting renewed attention from investors recently. In recent months gilt yields have risen substantially. In September 2026, the yield on 10-year UK government bonds climbed above 5.3%, its highest level since 2007. Even more strikingly, yields on 20- and 30-year gilts have reached their highest levels since 1998. In this in-depth article I explained what gilts are and the pros and cons of investing in them. I also discussed a number of different ways you can add gilts to your portfolio.
Finally in The £12,000 Cash ISA LImit – What Will Change in 2027? I discussed this important change to savings rules coming next year. It concerns the Government’s decision to reduce the annual Cash ISA allowance from £20,000 to £12,000 from April 2027. There is one very important caveat, which is that the new £12,000 limit will only apply to people under the age of 65. If you’re 65 or over, you will still be able to put up to £20,000 a year into a Cash ISA. This post explains everything we know so far.
One other thing is that, if you’re looking to change your energy provider as winter approaches, EDF Energy have enhanced their usual bonus offer. Instead of £50 you can now get a £75 bonus credited to your account if you sign up with EDF via my referral link. This offer closes on 6 October 2026, so you will need to move smartly now. I’ve been with EDF myself for several years. In my experience they offer a reliable service along with prices that are generally very competitive. If you do choose to do this via my link I will receive a bonus as well, which is very much appreciated 
Also, the Trading 212 welcome offer has reopened. If you haven’t done this before, you can get a free share worth up to £100 just for signing up to this investment platform using my referral link, You can also see my blog post about this at https://www.poundsandsense.com/get-a-free-share-worth-up-to-100-with-trading-212. The current offer closes on 3rd November 2026.
I’ll close with my customary reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as it is now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out!
- I am also on the BlueSky social media network under the username poundsandsense.bsky.social. Twitter/X remains my primary social media platform, but I also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.
As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 
Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss.
Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!