My Investments Update September 2026

My Investments Update – September 26

Here is my latest monthly update about my investments. You can read my August 2026 Investments Update here if you like.

I’ll begin as usual with my JP Morgan Personal Investing (previously Nutmeg) Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

As regular readers will know, in June last year I transferred most of the money in my former Nutmeg Fully Managed portfolio (just under £25,000) to a new Nutmeg Income Portfolio. I discussed this in detail in this post, but basically money in this port is invested to generate an income from share dividends and other sources. This is then paid monthly. Capital appreciation is targeted as well, but these portfolios are aimed primarily at older people (and others) who want/need their investment to generate a regular cash income.

In August my JPM Investing income portfolio generated £157.02 of income, which was duly paid into my bank account on 24 August 2026. That means I have now received (tax-free) income of £894.41 in 2026 and a total of £1,365.87 since I opened the account in June last year. That’s a return on capital of around 5% to date. That is in line with JPM’s original projected annual return for income ports at my chosen risk level (five).

My income portfolio also increased in value in August. It’s now worth £29,010 compared with £28,447 at the start of August, a rise of £563. As the screen capture below shows, my income port is up by a respectable £3,406.67 (13.31%) after fees since I opened it in June 2025.
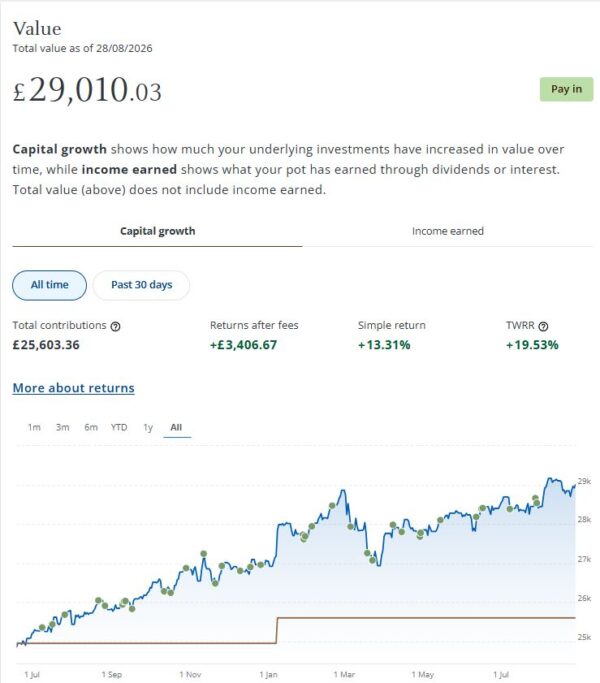
JPM Income port Sept 2026

I still have a smaller, growth-oriented pot using JPM Investing’s Smart Alpha option. This is now worth £3,313 compared with £3,221 a month ago, a rise of £92. Here is a screen capture showing performance since I opened it in December 2020. As you may recall, I sold £2,000 worth of this portfolio in May this year to pay for some building work.
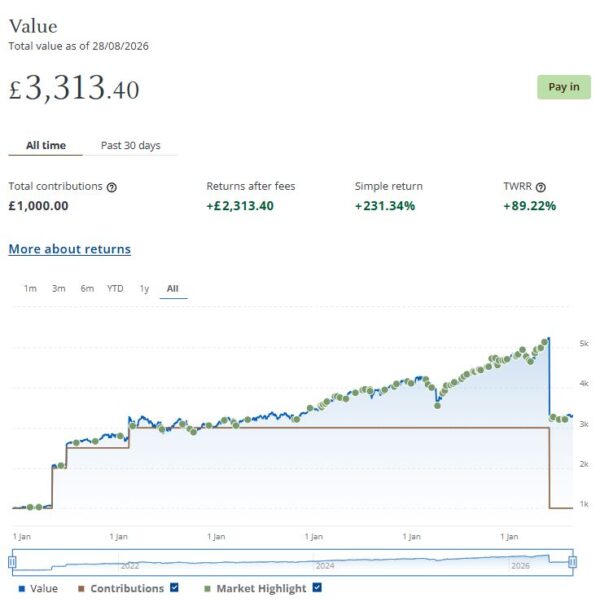
JPM Smart Alpha port Sep 2026

Finally, at the start of December 2023 I invested £500 in one of Nutmeg/JPM’s thematic portfolios (Resource Transformation). In March 2024 I also invested a further £200 from referral bonuses (something I no longer receive). As you can see from the YTD screen capture below, this portfolio is now worth £1,055 compared with £1,019 (rounded up) last month, a rise of £36.
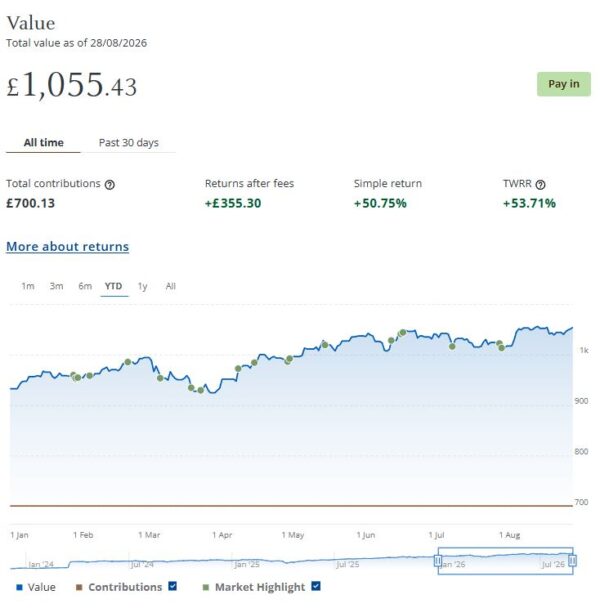
JPM Thematic port Sep 2026

Overall in August the value of my JPM investments rose by £691 or 2.12%. In addition, I did of course receive £157.02 in income from my income portfolio. In total, then, I am up by a respectable £848.02 for the month.

Excluding income generated (and allowing for the £2,000 I withdrew in May this year) the overall value of my JPM investments has risen by £3,716 since the start of September 2025. If you add to this the £1,365.87 of income generated by my Income portfolio since August 2025, that gives a total profit for the last 12 months of £5,081.87 – a pretty good return in these uncertain times. Another way of looking at this (which I like!) is that the £2,000 I withdrew in May this year has been comfortably covered by the growth in value of my JPM investments over the last year.

Obviously it’s important not to read too much into a single month’s performance. Ups and downs are very much to be expected with stock market investments. In the longer term they tend to even themselves out and typically outperform bank savings accounts (though that’s never guaranteed). In general the worst thing you can do is panic and sell up when downturns occur. You are then crystallizing your losses rather than giving the markets time to recover. That is something I had cause to discuss last year in this blog post.

You can read my full original Nutmeg/JPM review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last nine years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Housemartin. As discussed in this post, the company rebranded last year from Assetz Exchange.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £339.75 in revenue from rental income. I have made a small net loss of £17.60 on property disposals. Capital growth generally has slowed, in line with UK property values generally.

At the time of writing, 25 of ‘my’ properties are showing gains, 4 are breaking even, and the remaining 18 are showing losses. My portfolio of 47 properties is currently showing a net decrease in value of £56.92. That means that overall (rental income minus capital value decrease and loss on disposal) I am up by £265.23. That’s still a respectable return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

  • A further consideration is that property investments on Housemartin are less likely to be affected by stock market downturns, as happened in March this year due to events in the Middle East. This again demonstrates the potential value of such investments for diversifying your portfolio during challenging times.

The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I usually reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my original review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].

In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

In January this year, as Oil Worldwide hadn’t exactly been setting the world alight, I decided to switch my entire investment in this to another smart portfolio, InTheGame. This port, focusing on the computer gaming industry, had been the top performer for some time in my eToro virtual portfolio.

Unfortunately just as I switched away from Oil Worldwide, President Trump decided to invade Venezuela. This gave the oil industry a significant boost, which I would otherwise have benefited from. Meanwhile InTheGame went south, partly due to the war in the Middle East. At one point I was down by over 10% on this investment. Fortunately in the last few months InTheGame has made a recovery and is now in profit by 5.15%.

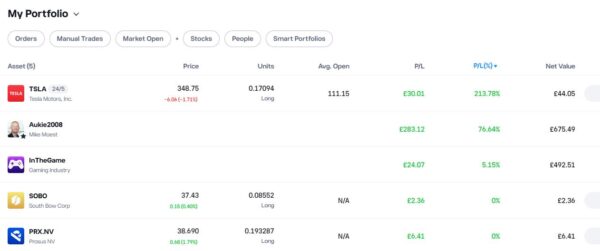
As you can see from the screen captures below, my original eToro investment (total value £888.36 in pounds sterling) is today worth £1,222.16, an overall increase of £333.80 or 37.57%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.
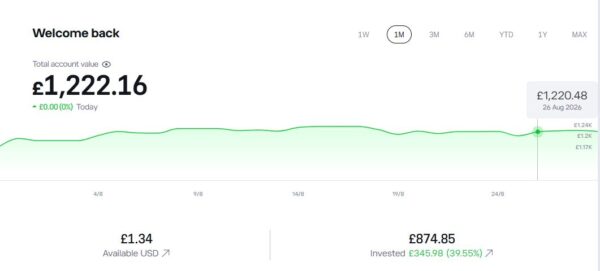
Etoro Home Sept 2026

Etoro port Sep 2026

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this post.

As mentioned above, my new investment in InTheGame is currently up by 5.15%. And my copy trading investment with Aukie2008 is showing an impressive overall profit of 76.64%. Of course, I have held this investment for quite a bit longer.

My Tesla shares, which I purchased as an afterthought with some spare cash I had in my account, are also up this month. They are now showing an overall profit of over 213% since I bought them. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio.

Moving on, I published several posts on Pounds and Sense in August. I have listed below those that are still relevant.

Caravan Fire Safety – How to Protect Your Holiday Home and Your Finances is a collaborative post with my friends at  Compass, a specialist provider of caravan and leisure insurance. It concerns an important subject all caravan owners need to be aware of. This post was especially relevant during the hot, dry spell we have just gone through. But even when the weather is cooler it’s still very relevant. In the article – which applies to static as well as mobile caravans – I set out a number of tips to keep your holiday home safe from fire, and also some important insurance advice for caravan owners.

In My Short Break in Portmeirion I talked about my recent short visit to this beautiful Welsh village and tourist resort (famously the location in which 1960s TV series The Prisoner was shot). It was the first time I had stayed in Portmeirion, though I had visited many times before. In my article I discuss the accommodation, the dining facilities, the costs, things to do in (and around) Portmeirion, and whom (in my view) the location is most likely to appeal to.

Finally in Pounds and Sense – A Personal Update I set out some information about my personal circumstances and (in particular) my plans for Pounds and Sense going forward. I won’t say any more about this here, but I do urge you to read it if you haven’t already.

  • One other thing is that, if you’re looking to change your energy provider as autumn approaches, you can get a £50 bonus credited to your account if you sign up with EDF Energy via my referral link. I’ve been with EDF myself for some years now. In my experience they offer a reliable service along with prices that are generally very competitive. If you do choose to do this via my link I will receive a bonus as well, which is very much appreciated 🙂

I’ll close with my customary reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as it is now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out!

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. Twitter/X remains my primary social media platform, but I also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!


If you enjoyed this post, please link to it on your own blog or social media:
My short break in Portmeirion

My Short Break in Portmeirion

I recently enjoyed a three-night break in the lovely Welsh village/resort of Portmeirion. This is about two miles from Porthmadog in NW Wales. It was the first time I had stayed in Portmeirion, though I have visited many times before. Here’s a map from Google Maps.

Portmeirion is a beautiful Italianate village created by the architect Clough Williams Ellis. These days it’s probably best known as the location for the 1960s cult TV series The Prisoner, starring Patrick McGoohan.

Portmeirion is privately owned and you have to pay a fee to enter during the day. Of course, if you are staying there, as I was, this is included in the price you pay.

  • You can also get free admission (in the afternoon) by booking a minimum two-course lunch at Castell Deudraeth; this is part of the Portmeirion estate, a short walk from the village itself. Free admission to the village is also available if you book a spa treatment or afternoon cream tea there.

Accommodation

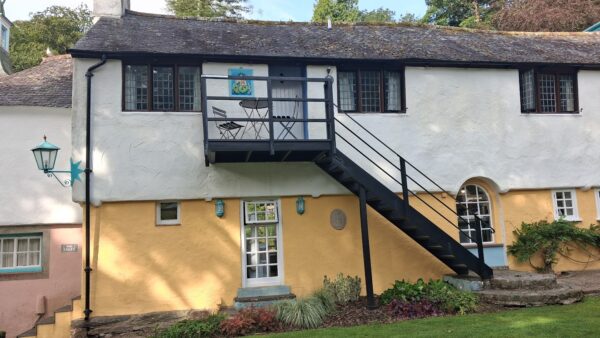
There are various accommodation options in Portmeirion. You can stay in the main hotel in the village or at Castell Deudraeth. You can also stay in one of the many self-contained cottages and apartments in the village itself. I did the latter, staying in one called The Neptune Suite. This is in the heart of the village, directly over the ice cream parlour. Here’s a photo…

Neptune Suite Portmeirion

I was quite surprised how spacious The Neptune Suite was. The front door opened into a good-sized lounge with comfortable chairs and sofas and (of course) a TV. There was also a sink in the corner with an electric kettle, coffee and teabags, mugs and glasses, and so forth. There were no cooking facilities but there was a small fridge with complimentary bottled water and a bottle of champagne (definitely not complimentary). The fridge came in very useful for storing milk and snacks for the evening (see below).

Next to the lounge was a double bedroom, with a large bathroom off it. The latter had a separate bath and shower, which felt quite a luxury. A good selection of freebies such as bath/shower gel, shampoo and conditioner, soap, shower caps and even miniature shoeshines were provided.

I stayed on a bed-and-breakfast basis. Breakfast was provided in the hotel, which was about five minutes’ walk away. The hotel breakfasts were excellent, with a self-service buffet and a choice of cooked breakfasts, which were brought to you. During the day I ate at one of the cafes and restaurants in the village (I particularly recommend the Italian-themed Caffi Glas).

There are fewer options for eating in Portmeirion in the evening. Basically you can book a table at the hotel or Castell Deudraeth. These both have highly rated restaurants, with prices to match! They would be good if you were celebrating a special occasion, but a bit pricey to eat at every day. Personally, after a big hotel breakfast and lunch in the village (or out exploring) all I wanted in the evening was a light meal anyway. So I brought my own bread and cheese, fruit, biscuits and so on. Along with a cold drink or a pot of tea, that was fine for me! But otherwise you could always take a short drive into Porthmadog, which has plenty of shops and eateries.

The apartment had free wifi which worked perfectly during my stay (not always the case in my experience). The location was quiet and peaceful (there was a low-key buzz from the ice cream parlour during the day but that closed at 4 pm) and I slept very well during my stay.

Financials

As Pounds and Sense is primarily a money blog, I should say a word about this.

Portmeirion is a bit more expensive than most places I visit on short breaks. For my three-night stay with breakfast, I paid £640, which works out at around £213 per day. I thought that was actually quite reasonable bearing in mind the standard of the accommodation and the other amenities on offer. I got a 10% ‘Genius Discount’ from Booking.com, which may have reduced the cost a bit.

I did notice as well that prices vary somewhat from week to week, I assume due to supply and demand. A bit of trial and error here may pay dividends!

One other thing I should say is that I opted for a ‘Village Double Room’ and didn’t know exactly what accommodation I would get. I guess that’s like staying in a hotel, when you aren’t normally told your room number beforehand. If you have a particular preference you can always try asking, but there’s no guarantee you will receive it. I did email a few days before to ask where I would be staying and discovered then that it would be The Neptune Suite.

Things to Do

There are various things you can do in or around Portmeirion. On my first full day I stayed in the village itself. I enjoyed walking the coastal path from the village and back through the woodlands behind. I also spent some time enjoying the heated outdoor pool. This is available to residents only (not day visitors). I was lucky with the weather and made the most of this facility. The changing rooms are pretty basic, but as my accommodation was just a couple of minutes’ walk away that really wasn’t an issue for me.

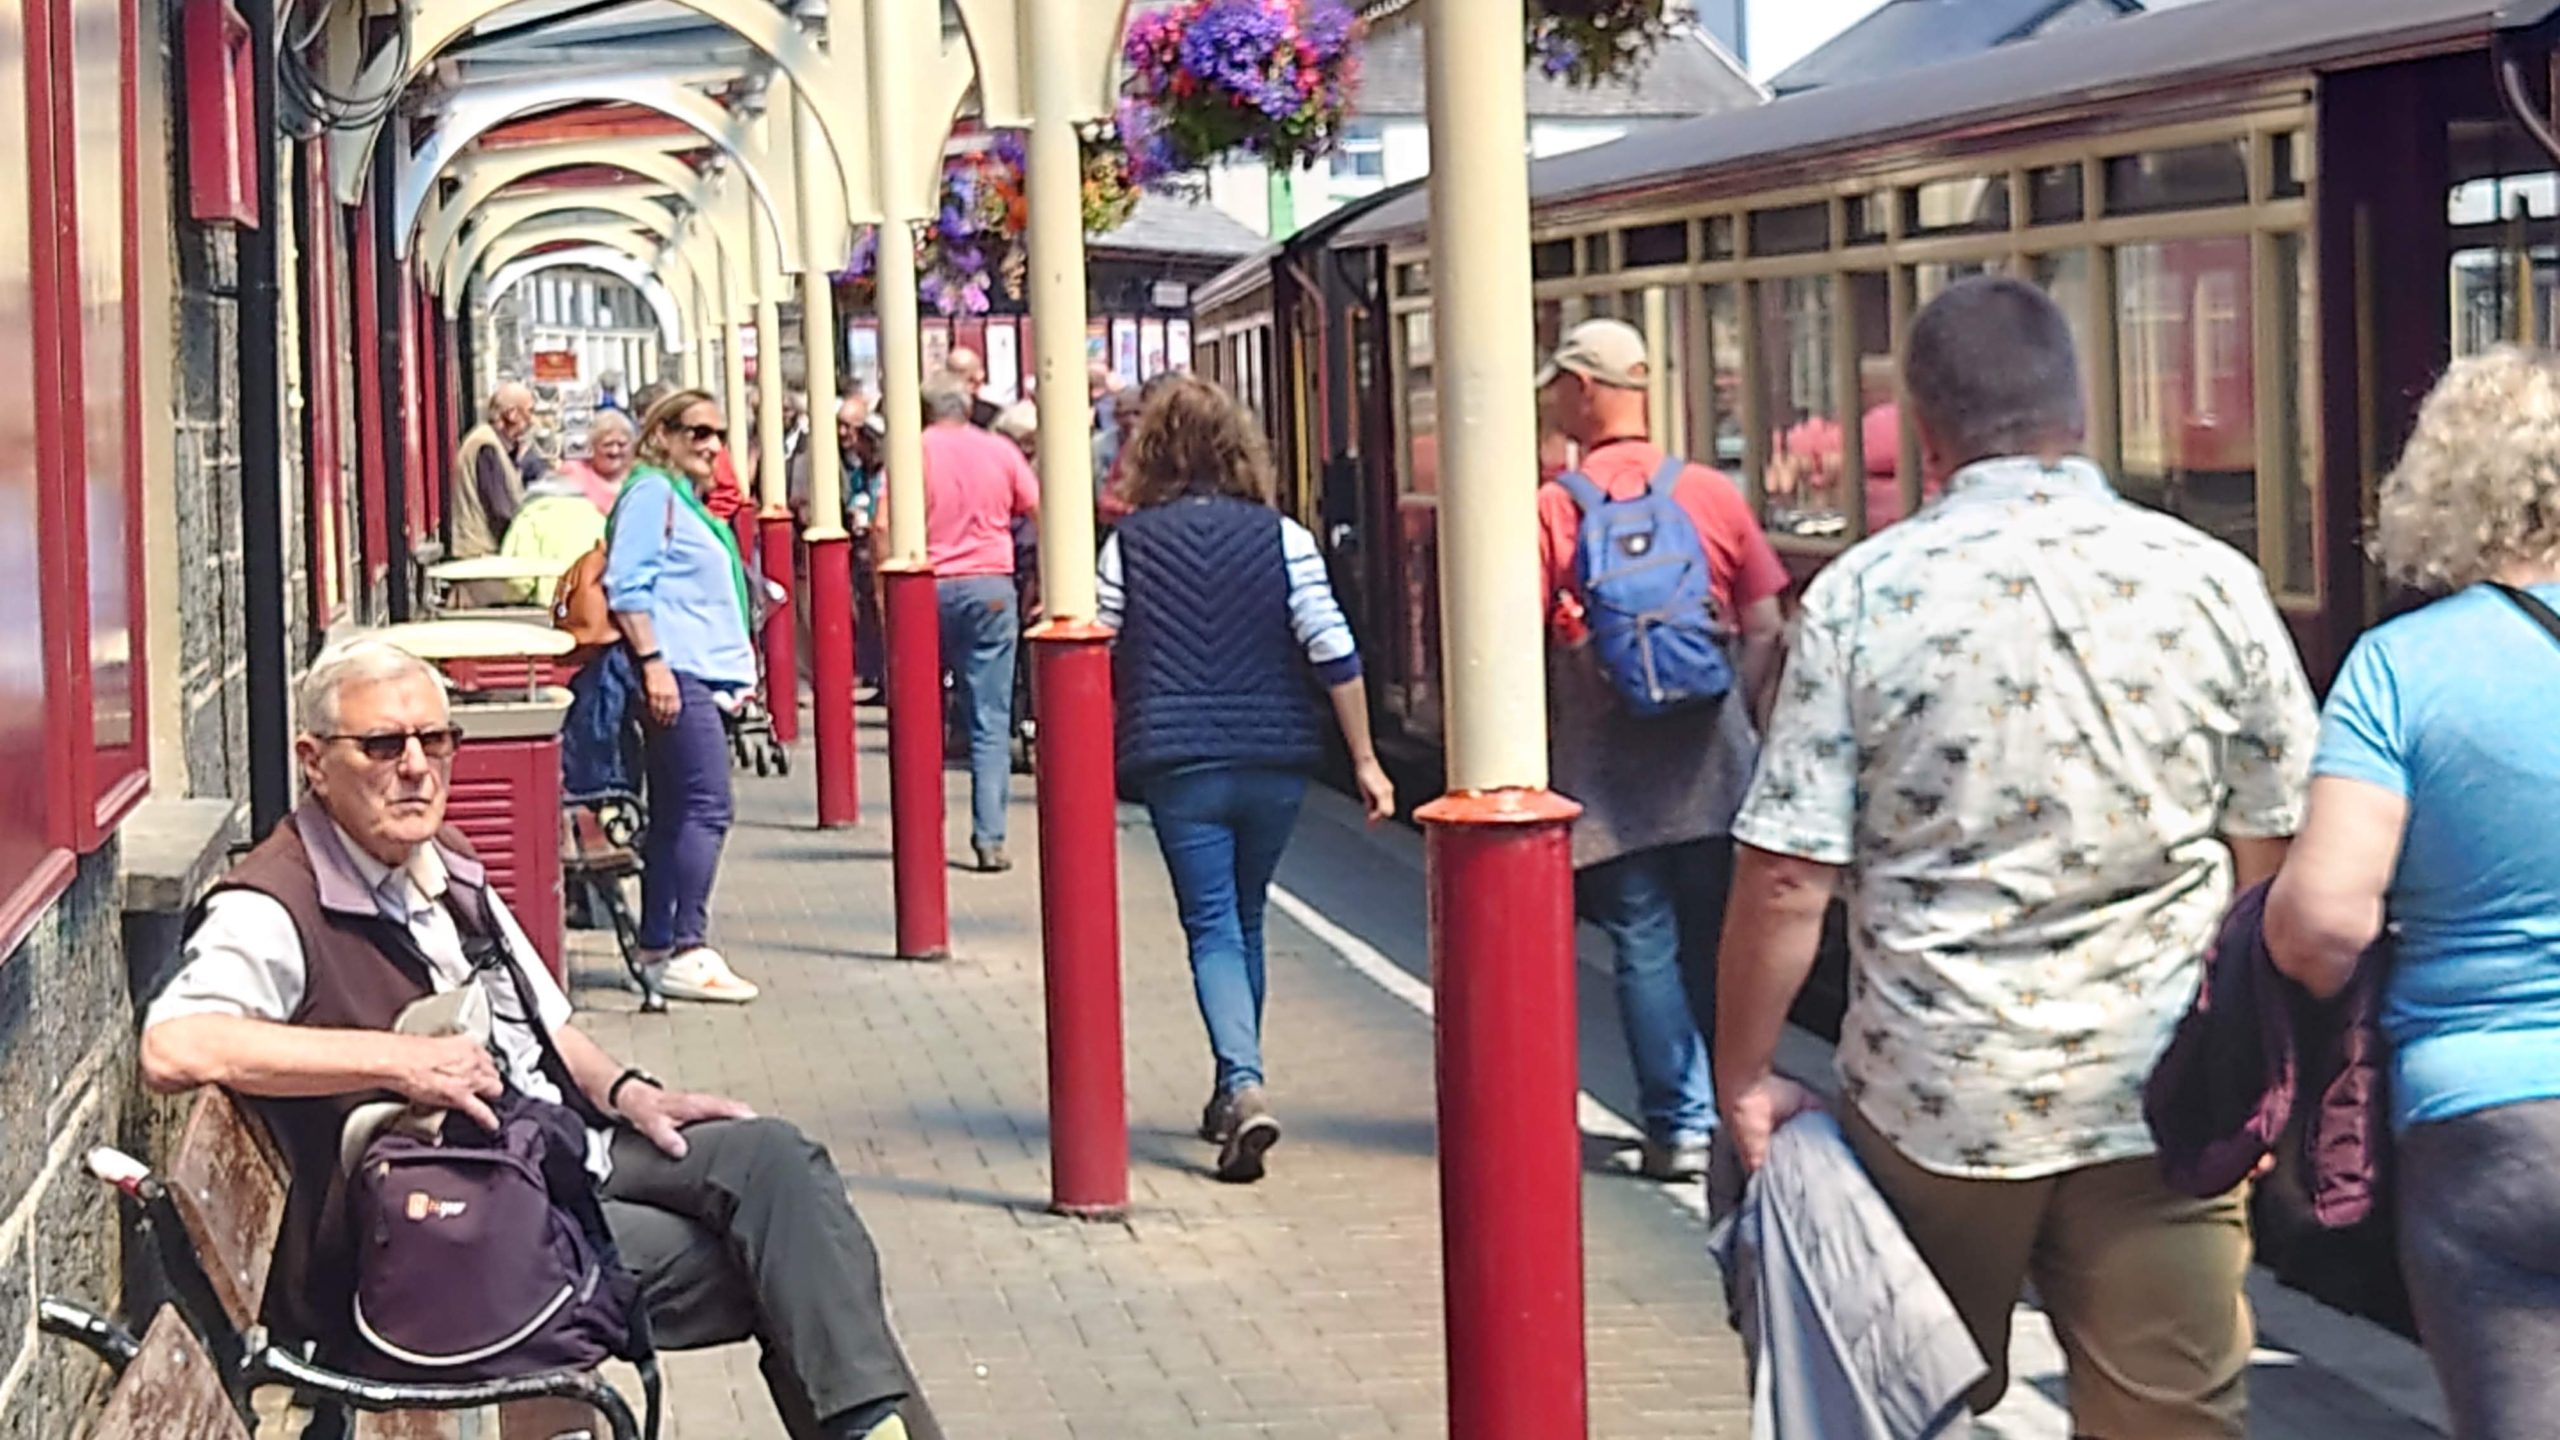
On my other full day I took a five-minute drive to Porthmadog and enjoyed a trip on the Ffestiniog Railway.

Ffestiniog Railway

This heritage steam railway has two separate lines, both of which run from Porthmadog. The Welsh Highland Railway takes you on a scenic two-and-a-quarter hour trip through the heart of Snowdonia to Caernarfon, while the original Ffestiniog Railway takes you on a one-hour trip to Blaenau Ffestiniog. On this occasion I took the shorter journey, but I have done the Welsh Highland Railway trip before and recommend it as well. You can get more info on both (and book in advance) via the Ffestiniog Railway website.

The harbour station in Porthmadog has a small car park for people with disabilities only, but there is a free car park for people travelling on the railway at the back of the public car park opposite (Llyn Bach). I used that myself on this occasion. There were plenty of spaces when I arrived at around 9.30 a.m. but I noticed it was full later. So my top tip if going by car is to book a ticket on a morning train rather than leaving it until the afternoon!

Final Thoughts

As you may gather, I enjoyed my short break in Portmeirion and am happy to recommend it for a relaxing short break (though not an especially cheap one!).

Portmeirion is a great place to kick back and chill out. It has good road and rail connections, and there are also other high-quality tourist attractions nearby, including the Ffestiniog Railway, Harlech and Criccieth Castles, and so on.

Portmeirion itself isn’t somewhere to go if you want to be ‘entertained’. The gardens and buildings are beautiful and highly photogenic, and there are some lovely little shops and cafes. You can also enjoy scenic walks alongside the estuary and through the woodlands. And, as mentioned above, there is an outdoor pool you can use (or sunbathe beside, weather permitting!).

To be honest, Portmeirion isn’t going to suit everyone. If you want a holiday with lots of activities and entertainment laid on, it won’t fit the bill. And children and teenagers (especially) might find it a bit limited. For older people and couples looking to relax and recharge their batteries, though, it might be just the thing. There are also some special events (e.g. The Prisoner Weekend) held there throughout the year.

One other point to note is that dogs (apart from guide dogs) are not allowed anywhere in the village. So if you normally take a canine companion on holiday with you, Portmeirion may not be the place for you.

As always, if you have any comments or questions about this post, please do leave them below.

Be Seeing You


If you enjoyed this post, please link to it on your own blog or social media:
Pounds and Sense - Personal Update

Pounds and Sense – A Personal Update

Today I wanted to share some information about my personal circumstances and my plans for Pounds and Sense (in particular) going forward.

As you may know, I’ve been running PAS for nearly 10 years now and during that time have published over 560 blog posts. Most of these are still available to view via the sidebar on the right (or below if you’re reading this on a mobile). They cover the entire period during Covid, and some in particular make quite poignant reading now.

Nothing is forever, though, and as I’m now 70 I’ve decided the time has come to wind down the blog. My health remains reasonable (touch wood) but I have other interests I want to devote more time and energy to.

In addition, I am now officially retired and no longer registered as self-employed. In fact, Pounds and Sense hasn’t made a profit for some time. As other bloggers will testify, it has become much harder to make money this way in recent years – especially if (like me) you’re a one-man – or one-woman – band.

A major cause of this – in my view anyway – is the rise of AI in online search. In the past you could attract traffic by targeting certain keywords and phrases and hoping Google (or whoever) would rank your article high in search results for the keyword/s in question. With most people nowadays going no further than the AI answers at the top, that method of attracting readers no longer works nearly as well as it used to.

For this and (no doubt) other reasons, the last few years have seen a big fall in the number of other UK personal finance blogs. The ones left are mainly those run as a full-time business, often with a team of staff. Really these are personal finance websites rather than blogs in the traditional sense. There are still a few brave solo bloggers left, and more power to them. But from comments I have seen, I know many of them are struggling as well.

Meanwhile, the costs keep on rising. Pounds and Sense is a self-hosted WordPress website, so I have to pay annual fees for the domain name and (in particular) the hosting service. In total I am now paying over £200 a year for this, which in the last year or two is more money than I have made (directly) from the blog itself. There are other costs  as well such as accountancy services and even electricity bills. I also have to pay for the graphics service I use (PicMonkey) to create the cover images for my blog posts.

For all these reasons, then, I am winding down Pounds and Sense. I won’t stop immediately, but my posts will likely be less frequent in the coming months. In April next year my hosting service (the largest expense I have to pay) comes up for renewal, and at that point I plan to allow it to lapse. So after that date, all past and current content will cease to be available here. If there are any articles you particularly want to save for future reference, therefore, I recommend that you copy them sooner rather than later.

I should also say that as I will be closing PAS, I won’t be taking on any further sponsored posts or other commercial partnerships or arrangements. I don’t think it would be fair to take on such projects knowing that the blog will in all likelihood cease to exist a few months later. I am still happy to consider guest posts but on the understanding that they may not be up here very long.

With all that said and done, I do enjoy blogging, and it’s possible I might continue Pounds and Sense in some shape or form using a free or low-cost hosting service such as Blogger or WordPress.com. I might also copy over some content to this. Using this type of service has its drawbacks, but of course it has the big attraction of being cheap or free! Obviously I will let PAS readers know nearer the time if I decide to proceed with this.

In closing, thank you for reading this far; and particular thanks to my regular readers, some of whom have been with me for many years. I wish you all a happy and prosperous future in these increasingly uncertain times.

As always, you are very welcome to leave a comment below if you wish.


If you enjoyed this post, please link to it on your own blog or social media:
Caravan Fire Safety

Caravan Fire Safety: How to Protect Your Holiday Home and Your Finances

My post today is brought to you in association with Compass, a specialist provider of caravan and leisure insurance. It concerns an important subject all caravan owners need to be aware of.

With the UK experiencing a prolonged period of hot and dry weather this summer, and drought now declared across large parts of England for the third time in five years, it’s vital that all caravan owners take extra precautions to reduce the risk of fire.

Static caravans are particularly susceptible to fire damage. Their fixed position, close proximity to neighbouring units, and structural materials – often made of plastic and thin cladding – mean that a fire can spread rapidly and with devastating effect. The use of LPG gas cylinders adds further risk if they are not stored and handled correctly.

In August 2025, a wildfire on the North York Moors came within a few hundred metres of a holiday park near Dalby Forest before a shift in wind and swift action from North Yorkshire Fire and Rescue Service prevented what could have been a catastrophic loss.

Less than a year later, in late July 2026, a major wildfire broke out at Dunwich Heath on the Suffolk coast, forcing more than 200 caravans to be evacuated from the nearby Cliff House Holiday Park as flames spread across over 150 hectares of heathland. More than 100 firefighters battled the blaze over several days after a major incident was declared, a stark illustration of how quickly fire can threaten caravan parks during sustained hot, dry conditions.

Nationally, the trend is stark: the UK recorded 117 wildfires in 2025, more than double the total seen in 2023 and a 32% increase on 2024, second only to the record 207 wildfires recorded during the 40°C heat of 2022.

2025 was officially recorded as the hottest UK summer to date, and 2026 has already brought comparably extreme conditions, meaning the risk of fire-related incidents in caravans remains high. This is reflected in Compass’s fire claims data, which peaked between January 2024 and December 2025 at £881,982 – more than five times the total from the previous year.

With this summer already matching the extremes of 2025, and incidents like Dunwich Heath showing how fast a wildfire can take hold, taking proactive fire safety precautions in caravans is more critical than ever.

Common causes of static caravan fires include:

  • Careless use of barbecues near units

  • Improper disposal of cigarettes

  • Unattended cooking

  • Faulty gas appliances or heating systems

  • Electrical overloads and damaged wiring

According to fire safety data, a fire in a mobile home or caravan is significantly more likely to result in death or serious injury compared to conventional housing.

Kevin Minnear, Head of Underwriting at Compass, explains: “Caravans are fantastic for enjoying the outdoors, but they come with serious fire risks, especially in dry conditions. What we saw as a near-miss on the North York Moors last summer, and now a major incident at Dunwich Heath this year, tells us this isn’t a one-off. It’s a pattern, and with the UK in the grip of a prolonged drought, the risk of fire has never been greater.

“As insurers, we see the aftermath of caravan fires all too often, with families losing not only their cherished holiday homes but valuable personal belongings as well. We’re reminding everyone to stay vigilant, follow basic safety practices, and help prevent fires before they start.”

Top Tips to Stay Safe in Your Caravan This Summer

  • Always use barbecues well away from caravans, awnings and dry grass. Never use them inside or on decking, and ensure coals are fully extinguished before disposal., and always follow your park’s barbecue rules and designated areas.

  • Do not smoke inside caravans. Always use a proper ashtray and ensure cigarettes are completely stubbed out and disposed of properly.

  • Store gas bottles outside in a secure, upright position and never in direct sunlight. Turn them off properly after use and have them checked regularly.

  • Every caravan should have at least one working smoke alarm fitted. Test it weekly and change batteries regularly.

  • Avoid open flames indoors; candles and gas lanterns can ignite furnishings or nearby materials in seconds. Use battery-powered alternatives instead.

  • Fit a fire blanket inside your caravan and make sure you have a fire extinguisher, so you are prepared should the worst happen.

  • Avoid overloading plug sockets and have electrical systems checked regularly.

  • Ensure all escape routes are accessible and exits are not blocked.

Insurance Advice for Static Caravan Owners

In the unfortunate event of a fire, adequate insurance cover can be the difference between financial recovery and long-term loss. Caravan owners are advised to:

  • Review your policy to ensure it covers fire damage comprehensively.

  • Keep an up-to-date inventory of contents.

  • Notify your insurer immediately in the event of a fire-related claim.

  • Check whether your cover includes temporary accommodation or replacement of personal effects.

Fire spreads extremely quickly in caravans – even a small spark can have devastating consequences, especially during dry spells.

Kevin Minnear adds: “Prevention is always better than cure. We’re encouraging all caravan owners to make safety a top priority this summer. Fire can devastate a caravan in minutes, but by being proactive and following these simple steps, you can help safeguard your property.”

Many thanks to my friends at Compass for their assistance with this article. For more info on specialist caravan and leisure insurance, please visit compass.co.uk

As always, if you have any comments on this article, please do post them below.


If you enjoyed this post, please link to it on your own blog or social media:
My Investments Update August 2026

My Investments Update – August 2026

Here is my latest monthly update about my investments. You can read my July 2026 Investments Update here if you like.

I’ll begin as usual with my JP Morgan Personal Investing (previously Nutmeg) Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

As regular readers will know, in June last year I transferred most of the money in my former Nutmeg Fully Managed portfolio (just under £25,000) to a new Nutmeg Income Portfolio. I discussed this in detail in this post, but basically money in this port is invested to generate an income from share dividends and other sources. This is then paid monthly. Capital appreciation is targeted as well, but these portfolios are aimed primarily at older people (and others) who want/need their investment to generate a regular cash income.

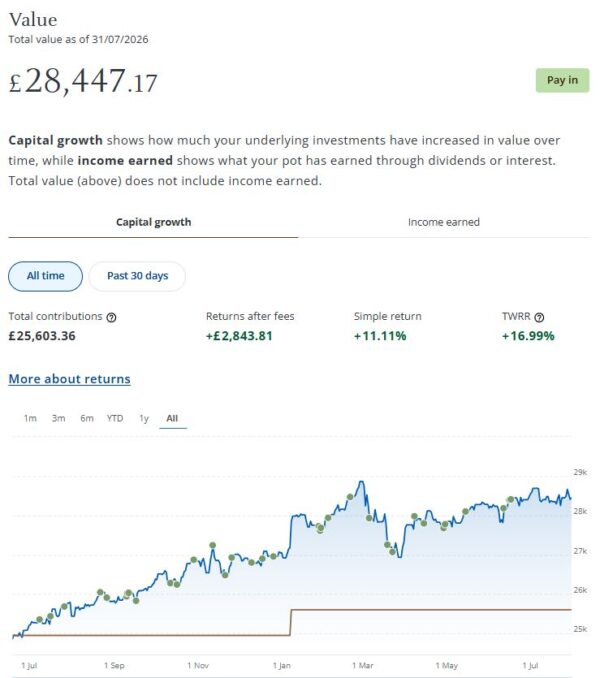
In July my JPM Investing income portfolio generated £89.56 of income, which was duly paid into my bank account on 24 July 2026. That means I have now received tax-free income of £737.39 in 2026 and a total of £1,208.85 since I opened the account in June last year (just over a year ago). That’s a return on capital of a little over 4.90% to date. That is close to JPM’s original projected annual return of just under 5% per year for income ports at my chosen risk level (five).

My income portfolio decreased slightly in value in July. It’s now worth £28,447 compared with £28,465 (rounded up) at the start of July, a fall of £18. As the screen capture below shows, however, my income port is still up by a respectable £2,843 (11.11%) after fees since I opened it last June.

JPM Income port August 2026

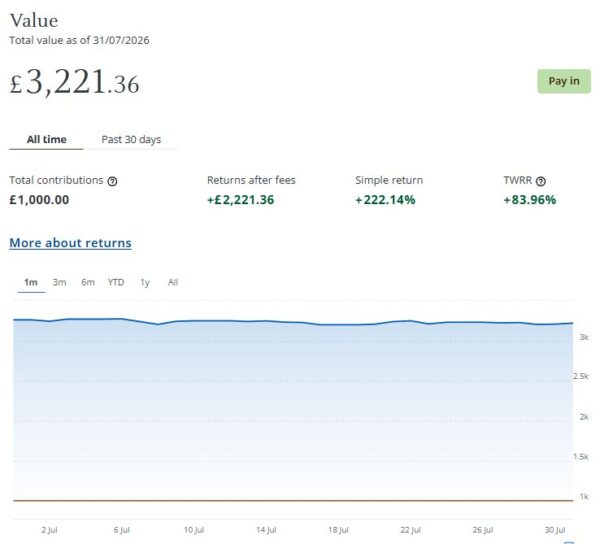
I still have a smaller, growth-oriented pot using JPM Investing’s Smart Alpha option. This is now worth £3,221 compared with £3,262 a month ago, a fall of £41. Here is a screen capture showing performance over the last month.

JPM Smart Alpha port August 2026

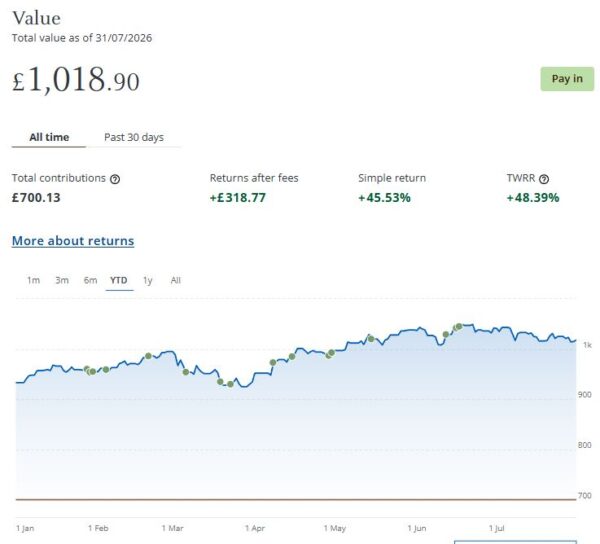
Finally, at the start of December 2023 I invested £500 in one of Nutmeg/JPM’s thematic portfolios (Resource Transformation). In March 2024 I also invested a further £200 from referral bonuses (something I no longer receive). As you can see from the YTD screen capture below, this portfolio is now worth £1,019 (rounded up) compared with £1,043 (rounded up) last month, a fall of £24.

JPM Thematic port August 26

Overall in July the value of my JPM investments fell by £83 or 0.25%. On the other hand, I did of course receive £89.56 in income from my income portfolio. In total, then, I am up by the princely sum of £6.56 for the month!

Excluding income generated (and allowing for the £2,000 I withdrew at the end of May this year) the overall value of my JPM investments has risen by £3,556 or 11.42% since the start of August 2025. If you add to this the £1,208.05 of income generated by my Income portfolio to date, that gives a total profit for the last 12 months of £4,764.05 – a pretty good return in these uncertain times.

The small drop in the value of my JPM investments in July is down mainly to the deteriorating situation in the Middle East. Obviously it’s disappointing, but some volatility is always to be expected with stock market investments. In the longer term they tend to even themselves out and typically outperform bank savings accounts (although that is never guaranteed). In general the worst thing you can do is panic and sell up when downturns occur. You are then crystallizing your losses rather than giving the markets time to recover. That is something I had cause to discuss last year in this blog post.

You can read my full original Nutmeg/JPM review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last nine years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Housemartin. As discussed in this post, the company rebranded last year from Assetz Exchange.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £334.80 in revenue from rental income. I have made a small net loss of £17.60 on property disposals. Capital growth generally has slowed, in line with UK property values generally.

At the time of writing, 23 of ‘my’ properties are showing gains, 6 are breaking even, and the remaining 18 are showing losses. My portfolio of 47 properties is currently showing a net decrease in value of £56.96. That means that overall (rental income minus capital value decrease and loss on disposal) I am up by £260.24. That’s still a respectable return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

  • A further consideration is that property investments on Housemartin are less likely to be affected by stock market downturns, as happened in March this year due to events in the Middle East. This again demonstrates the potential value of such investments for diversifying your portfolio during challenging times.

The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I usually reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my original review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].

In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

In January this year, as Oil Worldwide hadn’t exactly been setting the world alight, I decided to switch my entire investment in this to another smart portfolio, InTheGame. This port, focusing on the computer gaming industry, had been the top performer for some time in my eToro virtual portfolio.

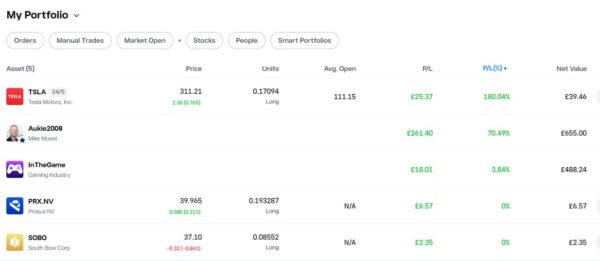
Unfortunately just as I switched away from Oil Worldwide, President Trump decided to invade Venezuela. This gave the oil industry a significant boost, which I would otherwise have benefited from. Meanwhile InTheGame went south, partly due to the war in the Middle East. At one point I was down by over 10% on this investment. Fortunately in the last four months InTheGame has made a recovery and is now in profit by 3.84%.

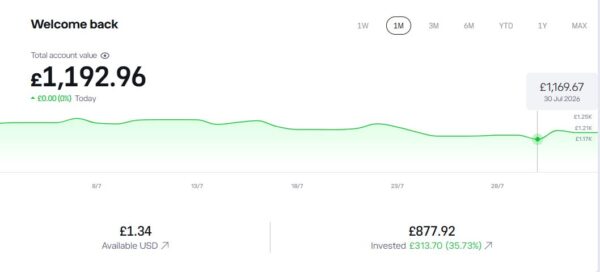
As you can see from the screen captures below, my original eToro investment (total value £888.36 in pounds sterling) is today worth £1,192.96, an overall increase of £304.60 or 34.29%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.

Etoro Main August 2026

Etoro port August 2026

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this post.

As mentioned above, my new investment in InTheGame is currently up by 3.84%. And my copy trading investment with Aukie2008 is showing an impressive overall profit of 70.49%. Of course, I have held this investment for quite a bit longer.

My Tesla shares, which I purchased as an afterthought with some spare cash I had in my account, are down a bit this month, but still showing an overall profit of over 180% since I bought them. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio.

Moving on, I published various posts on Pounds and Sense in July. I have listed below those that are still relevant.

In Small Changes That Could Save UK Households £1,000 a Year I set out some easy, everyday changes that could potentially have a big impact on your finances over the course of a year. As the article says, save a few pounds here and there, and before you know it you’ve kept an extra £1,000 in your pocket!

How to Know When Fruit and Veg Are Still Safe to Eat – And When They Should be Binned is a syndicated guest post by Primrose Freestone, whose work I have featured in Pounds and Sense before. Dr Freestone’s article concerns a subject that many older people (and others) on tight budgets may find of interest. It’s certainly something I have wondered about myself in the past.

And in Why Every Older Adult Should Consider the Shingles Vaccine (Shingrix) I look at an important subject every older adult should be aware of. Shingles is essentially a recurrence of a common childhood disease, chicken pox, but in older adults it can be a lot more serious. I recently had the new shingles vaccine (Shingrix) myself. In this article I explain why I felt it was important to do so, the side effects I experienced, and a potential beneficial side effect of the vaccine that has only quite recently come to light.

Finally, my cover image this month is a view of the lovely Welsh village/resort of Portmeirion (probably still best known as the venue for 1960s cult TV series The Prisoner starring Patrick McGoohan). I have visited Portmeirion many times before, but in July I fulfilled a long-standing ambition and actually stayed there for a few days. It wasn’t exactly a cheap break but well worth it. I may post an article/review in due course if there is sufficient interest.

I’ll close with my customary reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as it is now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out!

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. Twitter/X remains my primary social media platform, but I also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂
Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!
If you enjoyed this post, please link to it on your own blog or social media: