In Britain we’re lucky to have high-quality running water on tap whenever we need it. LIke everything else in life it costs money, however. And in these times of rising prices and squeezed incomes, those costs can be a growing burden. So in this article I’ll be setting out some ways you may be able to reduce your water bills.
The first thing to say is that water pricing varies across the nations of the UK. In England and Wales, unless you have a water meter, the price you pay will depend on the rateable value of your home.
In Scotland, again unless you have a meter, you will pay a standard water charge with your council tax.
Domestic customers in Northern Ireland are fortunate in that they aren’t required to pay a water bill at all, though it is possible this may change in future.
Should You Get a Water Meter?
The average water bill for unmetered customers is currently around £470 a year.
If you’re on a low income, that can represent a significant chunk of your money. And unlike gas and electricity, you can’t just shop around for a better deal with a different supplier. You may, though, be able to make significant savings by having a water meter installed.
With a meter, you are of course charged according to how much water you use. A good rule of thumb here is that if your house has more bedrooms than occupants or the same number, it is definitely worth looking into getting a meter installed.
Of course, people vary considerably in how much water they use. So you can use this free online calculator from the Consumer Council for Water to check whether you are likely to save money with a meter. It asks a series of questions about your home and your water usage and reveals the estimated cost you would pay if you had a meter. You can then compare this with what you are paying currently.
The good news is that in England and Wales (though not Scotland) water companies will normally install a water meter free of charge if requested. Even better, they will usually let you switch back to unmetered within 12 or even 24 months if you find you are paying more with a meter than you were before. You should check with your water company to find out their policy about this.
If your water company can’t fit a meter for some reason, you can ask for an ‘assessed charge bill’. This is calculated based on the size of your home and how many people live there. If it comes to more than you’re currently paying you can stick with your present billing method, so there is nothing to lose by requesting this.
Saving Money With a Water Meter
Once you have a meter installed, there are lots of ways you can reduce your water usage and save yourself money (and benefit the environment as well!). Here are just a few suggestions…
Only ever use the washing machine with a full load.
Have showers rather than baths and keep them reasonably short.
Do all the washing-up in one go.
Use a dishwasher, or at least a washing-up bowl.
Turn off the tap while brushing your teeth.
Don’t use the toilet as a waste bin for paper tissues, etc.
Fix dripping taps and any other leaks as soon as possible.
Finally, most water companies have a range of gadgets to help save water they will send you for free. Give them a call or check on their website to find out what’s available.
Other Ways to Cut Your Water Bills
If you are on a low income, all the water companies have schemes and discounted tariffs to help you. These vary a lot and you will need to check with your water company what they offer.
Severn Trent, for example, has the Big Difference Scheme, which offers significant discounts (up to £390 a year) on water bills for eligible households, based on income.
My Experience
As a customer of South Staffs Water, I recently applied successfully for a discount on grounds of low household income (under £22,011) under their Assure scheme.
Under this rather odd (in my opinion!) scheme I will be getting 60% off my bills in the first year, 40% in the second year, and 20% in the third. I have no idea if I will then be able to reapply and start the process again. Even so, it will certainly help my finances in these challenging times. Under Assure (and similar schemes) it is only your household income taken into account, not any savings or investments.
Closing Thoughts
Water bills have risen rapidly in recent years, partly due to the major investment required in Britain’s creaking water-supply and sewerage infrastructure, along with a rising population.
From being at one time a relatively minor expense, water bills are now (if you’ll pardon the pun) a significant drain on many people’s household income.
With other bills rising fast as well, it’s therefore vital to grasp any opportunity to keep your water costs as low as possible.
As always, if you have any comments or questions about this post, please do leave them below.
This is a revised and fully updated version of my original post.
If you enjoyed this post, please link to it on your own blog or social media:
When people think about investing, their minds often jump to stocks and shares. But bonds – a less glamorous but more stable option – can play a key role in a well-rounded investment portfolio, especially for those seeking predictable, regular income and/or lower risk.
In this article, I’ll reveal what bonds are, how to invest in them, and the main pros and cons to consider.
What Are Bonds?
A bond is essentially a loan from you to a government or company. In return, they pay you interest (known as the “coupon”) over a set period (typically annually or semi-annually). When the bond reaches the end of its term (maturity), you get your original investment back.
There are several types of bonds, including:
Government bonds (gilts) – issued by the UK government
Corporate bonds – issued by companies
Inflation-linked bonds – designed to rise with inflation
Foreign bonds – issued by overseas governments or companies
How to Invest in Bonds
There are a few ways you can invest in bonds:
1. Buy Individual Bonds
You can buy gilts or corporate bonds directly through:
The London Stock Exchange
Brokers such as Hargreaves Lansdown or AJ Bell
The UK Debt Management Office for new gilt issues
Buying individual bonds gives you control, but requires a higher initial investment and comes with more risk if the issuer defaults.
2. Bond Funds
Instead of picking individual bonds, you can invest in a fund that holds a basket of bonds:
Bond Unit Trusts and OEICs (Open-Ended Investment Companies)
Bond ETFs (Exchange Traded Funds) – such as iShares UK Gilts or Vanguard Global Bond ETF
These offer instant diversification and lower entry costs, and can be held in tax-efficient wrappers like Stocks & Shares ISAs or Self-Invested Personal Pensions (SIPPs).
WiseAlpha is a UK fractional bond platform that allows retail investors to buy fractional corporate bonds – essentially, small slices of high-yield bonds that are normally only accessible to institutional investors. This opens up access to a wide range of corporate bonds from major companies (e.g. Travelodge, HSBC and Asda) without the need for thousands of pounds to get started. This can be a good middle ground if you want more control over your bond investments than is offered by a fund but don’t have the capital required to buy full bonds.
See also the comparison table of UK bond platforms at the end of this article. This also reveals which platforms allow you to buy bonds within a tax-efficient ISA
Pros of Investing in Bonds
1. Reliable Income
Most bonds pay regular interest, making them a good source of steady income, especially for retirees.
2. Lower Risk Than Shares
Bonds are generally less volatile than stocks, so they can act as a buffer during market downturns.
3. Capital Preservation
If held to maturity and the issuer doesn’t default, you’ll get your money back.
4. Tax Efficiency
UK government gilts are free from Capital Gains Tax, and interest from bonds can be tax-free if held within an ISA or pension.
Cons of Investing in Bonds
1. Inflation Risk
Fixed bond payments may lose value in real terms if inflation rises sharply.
2. Interest Rate Risk
When interest rates go up, bond prices usually go down. If you need to sell before maturity, you could get back less than you paid.
3. Credit Risk
With corporate bonds, there’s always a risk the company could default on payments.
4. Lower Returns Compared to Stocks
Over the long term, bonds typically offer lower returns than equities.
Who Are Bonds Suitable For?
Bonds can be a great choice if:
You’re approaching or in retirement and want regular income
You want to reduce your overall portfolio risk
You’re saving for the medium term and prefer more stability
Younger investors, or those with a higher risk appetite, may prefer a smaller bond allocation in favour of higher-growth assets like equities.
Bonds vs Dividend Investing: Which is Better?
Both bonds and dividend-paying shares (as discussed in this recent blog post) can provide regular income. But they do so in different ways, and each has its own risks and benefits.
Here’s how they compare:
Feature
Bonds
Dividend Stocks
Income Type
Fixed interest (coupon)
Variable dividend payments
Predictability
High – payments are usually fixed
Medium – dividends can fluctuate or be cut
Capital Risk
Lower if held to maturity
Higher – share prices can be volatile
Inflation Protection
Limited (unless using inflation-linked bonds)
Better – companies may increase dividends over time
Tax Treatment
Interest taxable outside ISA/SIPP
Subject to dividend tax outside ISA/SIPP*
Growth Potential
Very limited
Potential for capital gains and increasing income
Ease of Access
Widely accessible via funds or platforms
Also widely accessible via funds or direct shares
Note: *There is a tax-free personal allowance for dividend income of £500 a year (2025/26)
Which One Should You Choose?
Choose bonds if your priority is stability, capital preservation, and predictable income, especially in the short to medium term.
Choose dividend stocks if you’re comfortable with a bit more risk and want potential for both income and long-term growth.
Many investors choose to hold both as part of a diversified portfolio, using bonds for stability and equities for growth and rising income.
Final Thoughts
Investing in bonds can bring balance to your portfolio, reduce volatility and provide income. Whether you go for government gilts, corporate bonds, or a diversified bond fund, it’s important to understand the risks and benefits and how bonds fit with your investment goals.
And as always – consider holding your bonds in an ISA or pension for maximum tax efficiency.
Comparison Table: UK Bond Investment Platforms
Platform
Bond Types Available
Minimum Investment
Suitable For
ISA Available
Notes
Hargreaves Lansdown
Gilts, Corporate Bonds, Bond Funds, ETFs
£100+
Beginners to experienced investors
✅ Yes
Well-established platform with wide fund and bond choice
Unique access to high-yield bonds from major companies
Note: *As of now, WiseAlpha does not offer an ISA wrapper, so income and gains may be taxable depending on your personal circumstances.
Please bear in mind as always that I am not a registered financial adviser and cannot offer personal financial advice. You should always do your own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss.
If you enjoyed this post, please link to it on your own blog or social media:
I’m slightly off topic today, but it’s a subject I hope will resonate with many readers of this blog (which is, of course, aimed primarily at over-50s).
Have you ever dreamed of strumming a guitar, tickling the ivories or even giving the ukulele a go, but assumed it was too late to start? Think again. Learning to play a musical instrument offers a wide range of benefits at any age, but for older adults it can be especially rewarding.
Whether you’re newly retired with time on your hands or simply looking for a fulfilling hobby, picking up an instrument could be one of the best decisions you make. Here are just some reasons…
1. Boosts Brain Power
One of the most compelling reasons to learn an instrument later in life is the impact it can have on your brain. Playing music engages both hemispheres of the brain, stimulating areas linked to memory, attention, co-ordination and problem-solving.
Research suggests that music can help delay cognitive decline and even reduce the risk of conditions such as dementia. In other words, it’s not just fun – it’s a workout for your brain as well.
2. Improves Mental Well-being
Making music is a proven stress-buster. It encourages mindfulness, takes your mind off worries, and creates a sense of achievement. For many older adults, especially those navigating major life changes like retirement or bereavement, playing an instrument can offer comfort, purpose and emotional expression.
Even just twenty minutes of playing a day can lower levels of cortisol (the stress hormone) and lift your mood.
3. Enhances Social Connections
Music has a magical way of bringing people together. Joining a local choir, ensemble or jam session can help reduce feelings of isolation and forge new friendships. Many communities across the UK offer beginner music groups for adults – often with a focus on having fun rather than achieving perfection.
And in this digital age, it’s easier than ever to connect with fellow learners online or via apps such as YouTube, Yousician or Simply Piano.
4. It’s Never Been Easier (or Cheaper) to Get Started
You don’t need a Steinway or a Fender to begin. Many beginner-friendly instruments – like the ukulele, recorder, harmonica or keyboard – are available from under £30. Online tutorials abound, and you’ll find countless free or low-cost courses through adult education providers, community centres or your local U3A (University of the Third Age).
Libraries and music shops may also offer affordable rental options if you’re not ready to commit to buying. And community groups often have spare instruments they may be willing to lend to newbies who aren’t yet sure if this will suit them or not.
5. Physical Benefits Too
Certain instruments improve hand-eye coordination, finger strength and dexterity. Wind instruments like the clarinet or flute can also help with breath control, posture and lung function – especially beneficial for older adults.
Even setting aside time to practise regularly adds structure and movement to your daily routine, and can provide a subtle yet valuable boost to your physical activity level.
6. A Hobby That Grows With You
Unlike some pastimes, music evolves with you. Whether you’re playing nursery rhymes for your grandchildren or tackling a Chopin prelude, there’s always something new to learn. And because you can practise solo, with a partner or in a group, it’s an incredibly flexible and life-long hobby.
Five Easy Instruments to Start With
If you’re unsure where to begin, here are some popular beginner-friendly options that are perfect for older adults:
🎸 Ukulele – Lightweight, inexpensive, and easy on the fingers. Great for singalongs.
🎹 Keyboard – Perfect for learning piano basics with built-in rhythms and tutorials.
🎼 Recorder – A simple wind instrument ideal for learning to read music and control breath.
🪗 Harmonica – Pocket-sized and portable with bluesy charm.
🪕 Digital drum pad – A fun way to explore rhythm without needing a full drum kit.
Click through any of the links above [sponsored] for searches on Amazon UK for the instrument in question.
My Experience
As regular PAS readers will know, I have been a member of my local U3A for a couple of years now. When I saw they were starting a ukulele group for beginners, I decided to give it a try.
I approached the first session with considerable trepidation. I’ve always enjoyed listening to music but don’t come from a musical family. The last time I had attempted to play any instrument was the recorder at school, and it’s safe to say I didn’t display any natural aptitude for it. Initially, then, I felt well out of my comfort zone.
Very soon, however, I started to enjoy some of the benefits mentioned above. My U3A group is friendly and supportive, and we are fortunate to have an excellent (volunteer) tutor to guide us. One advantage of the ukulele is that it is actually quite easy to learn a few basic chords, and once you can do that there are literally hundreds of songs you can play. Of course, getting good on the ukulele (or any instrument) takes time and practice. But you can still have a lot of fun even if you’re not quite ready for Britain’s Got Talent!
As someone living on their own, I have also very much appreciated the social element of my ukulele group. We meet one morning a week, and I have to say it’s a highlight of my weekly schedule. As well as playing and tuition (last week we had a workshop on how to change the strings of a ukulele), there’s always time for a chat over coffee and biscuits at our mid-session break. I count several members of the group as good personal friends now.
As mentioned above, there are lots of online videos and other resources you can use to help learn an instrument. But I do highly recommend joining a group as well (or at least working with a teacher or partner). This makes learning more enjoyable and can help maintain your enthusiasm and motivation. Tutors or more experienced members may also be able to answer any questions you have and provide feedback on your playing, including any mistakes you are making. It is certainly possible to learn an instrument on your own, but in my opinion it is significantly harder and requires a lot of self-discipline.
Final Thoughts
Age should never be a barrier to creativity. In fact, many older adults find that with less time pressure and a more relaxed mindset, learning an instrument becomes a very enjoyable aspect of their lives.
So if you’ve ever fancied yourself as a secret rock star, jazz pianist or classical flautist – it’s time to stop dreaming and start playing.
The only question is: what instrument will you choose?
Have you taken up an instrument later in life? Let me know in the comments below and/or share any of your own tips for beginners!
If you enjoyed this post, please link to it on your own blog or social media:
Today I have a guest post for you from my friend Carla on behalf of the FreeStuffSpot website.
If you like getting freebies delivered regularly, as Carla explains below, this is a site you definitely need to check out!
Imagine this: You’re sitting comfortably at home, watching a movie in your pyjamas, getting cosy with a nice cuppa, when the postman suddenly brings free beauty products to your home. Sounds wonderful, doesn’t it? It might even seem unreal. But I’m here to tell you that I’ve lived the dream. Let me help you learn about freebies.
I’m a huge fan when it comes to makeup. That’s been true as far back as I can remember, and it’s not likely to ever change. I could empty an endless bank account on makeup shopping, but sadly I don’t seem to have one of those. To keep my infinite appetite for makeup satiated, I always keep my eyes and ears open for ways to save money on the best beauty products. When I discovered that I could start getting free makeup sent straight to my home, I was more than a little interested. I was exhilarated.
You might not know this now, but there are many different makeup and beauty products sent to UK homes all the time, including free hair products, toiletries, perfume samples, and cosmetics. Think about it. You can try a current or new brand, all without spending any cash, or even leaving your home! Can it get better than that? Here are my insights about using FreeStuffSpot to get free makeup and beauty products on top of other freebies I already enjoy.
Why Are Beauty Brands Giving Free Stuff Away?
Businesses are always trying to get prospective customers to try out their products or brands in exchange for some feedback. These arrangements bypass the middlemen that normally do market research. Given how many businesses are moving towards the social media giants, namely Facebook and Twitter/X at least, they now can speak directly to consumers while listening to their concerns.
They can also reach out to many new customers at the same time.
So How Do You Get Free Beauty Products Of Your Own?
It’s not hard. I just registered for a newsletter from FreeStuffSpot, guaranteed to have nine brand-new freebies every single day. This newsletter covers things from free samples, competitions, and just generally free stuff. The day after I signed up for the newsletter, I got an email with giveaways, offers, and even restaurant vouchers.
What Other Kinds Of Freebies Are Available?
The website has more categories than just the beauty products I love and adore. You can find food and beverage, kids and baby stuff, free pet things, and freebies for just about anyone in your home. You don’t want to keep such a great thing to yourself, right?
FreeStuffSpot doesn’t just do freebies. They also have tricks to save money, advice on how to make money, and tips about getting more savvy in terms of money overall. The next time I plan to eat out, I’ll be using the page for restaurant vouchers for sure. The free days out category is great for us as a family, since we have young ones that love being out where it’s open. We can have a fun family day outside our home without emptying our bank account.
I’ve also joined the fan group for FreeStuffSpot enthusiasts. This perky community is a place where members post pics of the freebies they get. Sure, some of it is bragging, but it’s also about letting everyone else know about freebies and offers they don’t yet know about.
Just How Easy Is It To Use FreeStuffSpot?
If you want to start enjoying freebies, it’s very simple:
Visit the website at FreeStuffSpot and register to receive their daily newsletter full of freebies.
Browse the website and then apply for freebies you like the sound of.
Then just wait for the freebies to show up at your home!
My Verdict Is In…
I’ve really enjoyed looking through FreeStuffSpot since I started writing online. I’ve already got a perfume sample that I fell in love with, to the point of buying the actual full-size product. I’ve also got a tea towel, face wipes, and even teabags!
Many thanks to Carla for her enthusiastic endorsement of FreeStuffSpot. If you’re a freebies fan I hope you will take a moment to check out the site for yourself.
As always, if you have any comments or questions about this article, please do post them below.
This is a sponsored guest post.
If you enjoyed this post, please link to it on your own blog or social media:
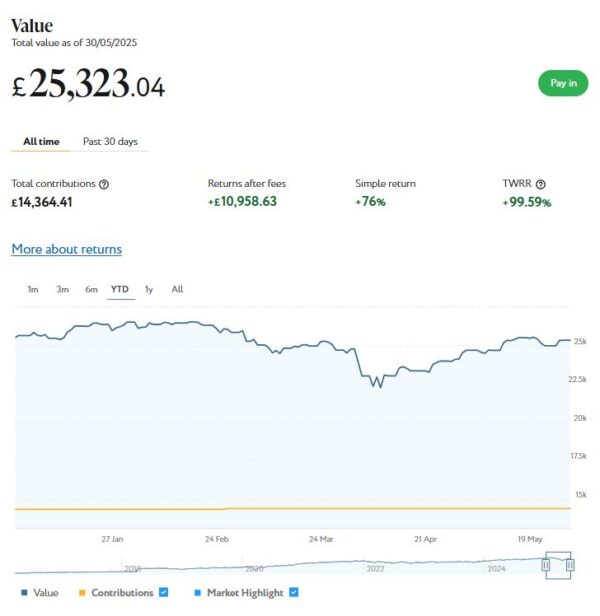
I’ll begin as usual with my Nutmeg Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).
As the screenshot below for the year to date shows, my main Nutmeg portfolio is currently valued at £25,323. Last month it stood at £24,532, so that is a rise of £791.
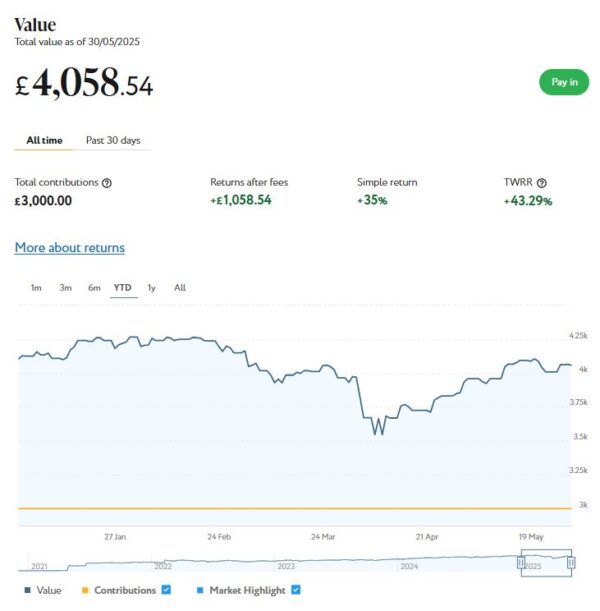
Apart from my main portfolio, I also have a second, smaller pot using Nutmeg’s Smart Alpha option. This is now worth £4,059 (rounded up) compared with £3,934 a month ago, a rise of £125. Here is a screen capture showing performance for the year to date.
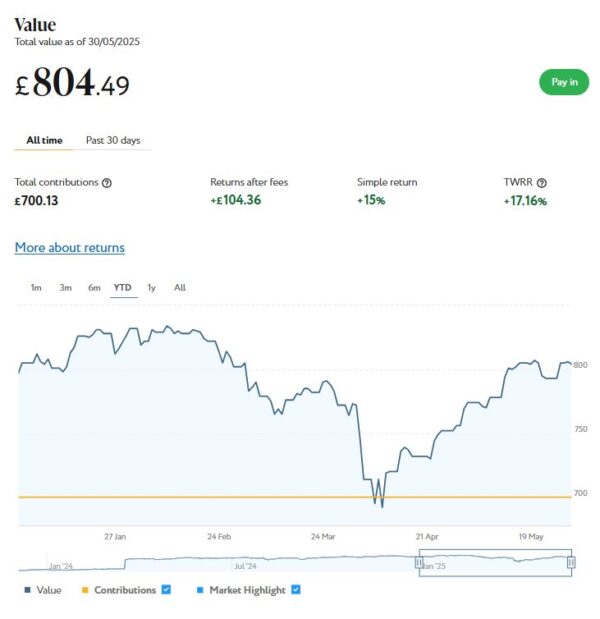
Finally, at the start of December 2023 I invested £500 in one of Nutmeg’s new thematic portfolios (Resource Transformation). In March 2024 I also invested a further £200 from referral bonuses. As you can see from the YTD screen capture below, this portfolio is now worth £804 compared with £770 last month, a rise of £34.
As you can see, May was a good month for my Nutmeg investments. Overall I was up by £950 or 3.25%.
I am still down slightly since the start of 2025, with the value of my investments decreasing by £242 or 0.08% since 1st January. On the other hand, their value has grown by £1,813 or 6.39% since the end of May last year. So, as I always say, the recent ups and downs do need to be taken in context. Some volatility is always to be expected with stock market investments, and over time they tend to even out. In general the worst thing you can do is panic and sell up when downturns occur (as happened in early April). You are then crystallizing your losses rather than giving the markets time to recover. This is something I had cause to discuss recently in this blog post.
You can read my full Nutmeg review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last eight years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.
Moving on, I also have investments with P2P property investment platform Assetz Exchange. As discussed in this recent post, the company recently rebranded as Housemartin.
My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.
Since I opened my account, my HM portfolio has generated a respectable £251.16 in revenue from rental income. I have also made a net profit of £0.57 on property disposals. Capital growth has slowed, though, in line with UK property values generally.
At the time of writing, 16 of ‘my’ properties are showing gains, 3 are breaking even, and the remaining 18 are showing losses. My portfolio of 37 properties is currently showing a net decrease in value of £47.34. That means that overall (rental income and profit on disposal minus capital value decrease) I am up by £204.39. That’s still a decent return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.
The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).
To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.
As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.
In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).
In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.
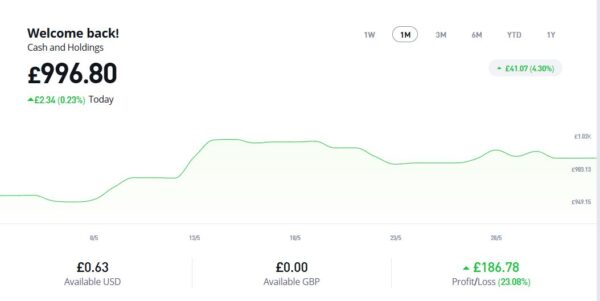
As you can see from the screen captures below, my original investment (total value £888.36 in pounds sterling) is today worth £996.80, an overall increase of £108.44 or 12.21%.
Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.
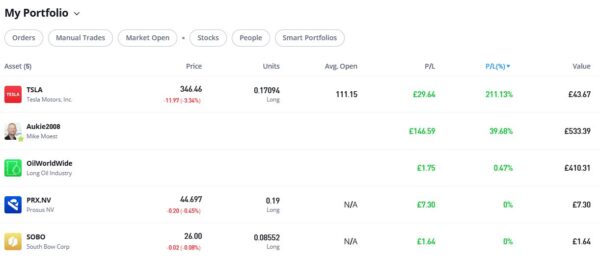
As you can see, my Oil WorldWide investment has recovered a bit since last time and is at least back in profit now, although it’s not exactly setting the world on fire (excuse the bad joke).
Thankfully my copy trading investment with Aukie2008 has been doing better, with an overall 39.64% profit. To be fair, I have held this investment a little longer.
My Tesla shares, which I bought as an afterthought with a bit of spare cash I had in my account, have done particularly well since I bought them, with an overall profit of 211.13%. If only I had put a bit more money into this! As a matter of interest, I do find it quite strange that my Tesla shares keep going up in value, despite all the stories in the press and social media about consumers boycotting Tesla. Go figure.
You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio!
eToro also offer the free eToro Money app. This allows you to deposit money to your eToro account without paying any currency conversion fees, saving you up to £5 for every £1,000 you deposit. You can also use the app to withdraw funds from your eToro account instantly to your bank account. I tried this myself and was impressed with how quickly and seamlessly it worked. You can read my blog post about eToro Money here. Note that it can also serve as a cryptocurrency wallet, allowing you to send and receive crypto from any other wallet address in the world.
If you would like more information about setting up an eToro account, please click on this no-obligation website link [affiliate]. Don’t forget that you also get a free $100,000 virtual portfolio, which you can use to experiment with trading and investing strategies. I have certainly earned a lot from mine.
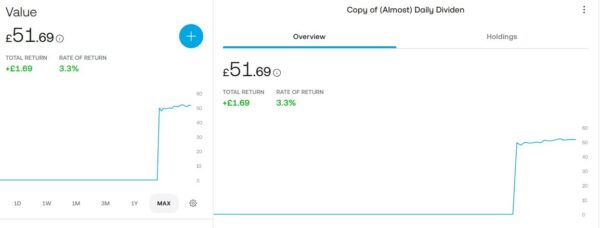
As a bit of an experiment, I recently put £50 into an investment ISA with Trading 212. As mentioned in my recent blog post about dividend investing, I put it into the (Almost) Daily Dividends Portfolio, a ready-made portfolio or ‘pie’ on Trading 212. As you can see from the screen capture below, my portfolio is now worth £51.69, an increase of 3.3% over the two-month period. It has even accrued a grand total of 9p in dividends!
I am quite impressed with how this investment has been faring, despite the small amount I put in (which means I may be missing out on some smaller dividends) and also because you need to have held shares for a certain period to qualify for dividend payments. If I increased my investment I would almost certainly become eligible for more dividends, and would qualify for more the longer I remain invested. If I had any spare money at the moment, I would certainly consider doing this!
Moving on, I published various posts on Pounds and Sense in May. I have listed below those that are still relevant
Why a Financial Remedy Order is Essential on Your Divorce is another guest post from my friends at HCR Law. If you are unfortunate enough to be in this position, this article contains important advice and information on how to ensure your personal financial security going forward.
Where to Get Pension Advice contains important information for anyone who may be coming up to retirement age, which of course includes many Pounds and Sense readers. This collaborative article includes details of six potential sources of pension advice, including the pros and cons of each.
Could You Benefit From Help to Save spotlights a lesser-known government scheme which, if you’re eligible, can give your finances a valuable boost. It’s an initiative aimed at helping people on low incomes (typically those receiving Universal Credit) build up their savings. Offering generous tax-free bonuses, this scheme can provide significant benefits for qualifying individuals.
How to Save Money on Rail Fares With Split Ticketing discusses a money-saving hack that savvy travellers can use to reduce their rail-fare costs – often by a substantial margin. Split ticketing involves breaking a journey into two or more smaller segments, purchasing separate tickets for each segment rather than one through-ticket. With the help of apps such as those discussed in the article, the process becomes simple and automated.
Finally, in What Are ETFs And How Can You Invest in Them? I shine a spotlight on these increasingly popular investment vehicles, explaining what they are, how you can invest in them, and how you can maximize the benefit by investing via tax-free ISAs.
I’ll close with a reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as we have to call it now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out.
I am also on the BlueSky social media network under the username poundsandsense.bsky.social. Twitter/X remains my primary social media platform, but I will also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.
As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers
Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss.
Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!
If you enjoyed this post, please link to it on your own blog or social media:
Today I am focusing on Exchange Traded Funds, or ETFs for short. These have become increasingly popular among investors seeking a simple, low-cost way to build diversified portfolios. But what exactly are ETFs, and how can you invest in them, especially in a tax-efficient way?
What Is an ETF?
An ETF is a type of investment fund that holds a collection of assets – such as stocks, bonds, or commodities – and trades on stock exchanges much like individual shares.
Most ETFs are designed to track the performance of a specific index, such as the FTSE 100, S&P 500, or MSCI World Index.
Because they bundle together a broad range of assets, ETFs offer instant diversification. If you buy an ETF tracking the FTSE 100, for example, you’re essentially investing in the 100 largest companies listed on the London Stock Exchange.
Why Choose ETFs?
Low cost: ETFs usually have lower management fees than actively managed funds, because they typically follow a passive investment strategy.
Diversification: A single ETF can give you exposure to hundreds or even thousands of securities across sectors or regions.
Liquidity: As ETFs are traded on stock exchanges, they can be bought or sold during market hours just like individual shares.
Potential for dividends as well as capital appreciation: If the value of shares in an ETF goes up, so does the value of your holding. Likewise, if the underlying shares pay dividends, these are either distributed to ETF investors as cash or reinvested to boost the value of your holding.
Transparency: Most ETFs publish their holdings daily, so you always know what you’re investing in.
Are There Any Drawbacks to ETFs?
While ETFs offer many benefits, they’re not without potential downsides:
Market Risk: Like all investments, ETFs can go down in value. If the underlying assets perform poorly, so will the ETF.
Tracking Error: Some ETFs may not perfectly replicate the performance of their target index due to fees or imperfect replication strategies.
Liquidity Issues: While most ETFs are highly liquid, some niche or low-volume ETFs can have wider bid-ask spreads, making it more expensive to trade them.
Over-Diversification: While diversification is usually a strength, owning too many overlapping ETFs can lead to a diluted portfolio that mirrors the overall market without any clear investment direction.
Currency Risk: If you invest in ETFs that hold assets in foreign currencies, exchange rate fluctuations can impact your returns. Of course, this applies equally to other types of investment as well.
Understanding the risks and how they relate to your investment goals is key to making informed decisions.
How to Invest in ETFs
Choose a Platform: First, you’ll need to open an account with a brokerage or investment platform that offers access to ETFs. Popular UK platforms include Hargreaves Lansdown, AJ Bell and Interactive Investor. InvestEngine specializes in ETFs and offers commission-free trading in a wide range. Trading 212 and eToro are other popular platforms that offer commission-free ETF trading.
Select Your ETFs: Decide on the asset classes and regions you want exposure to. For example, you could choose a global equity ETF, a UK government bond ETF, or a sector-specific ETF (such as technology, healthcare or renewables).
Place Your Order: ETFs can be bought and sold like shares. You can place a market order (buy at the current price) or a limit order (buy only at a specific price).
Monitor and Rebalance: Over time, you may need to adjust your portfolio to maintain your desired level of risk and diversification.
Consider Automated Services: If you don’t want to pick your own ETFs, many platforms offer ready-made portfolios (though these may entail extra fees and charges). Robo-adviser platforms such as Nutmeg – which I use myself – invest your money in ETFs and offer fully managed and fixed allocation portfolios.
Using an ISA for Tax Efficiency
One of the most tax-effective ways to invest in ETFs in the UK is through a Stocks and Shares ISA.
An ISA (Individual Savings Account) allows you to invest up to £20,000 per tax year (as of 2025/26) without paying any tax on your investment returns. The benefits of investing in ETFs via an ISA include:
No Capital Gains Tax: Any profit you make from selling ETFs within an ISA is tax-free.
No Dividend Tax: Any dividends paid by ETFs held in an ISA are also tax-free.
No Income Tax: Likewise, no Income Tax is due on returns from your investments.
Simplicity: There is no need to declare ISA investments on your tax return.
Final Thoughts
ETFs are a powerful tool for building a diversified, cost-effective investment portfolio. Whether you’re a beginner or an experienced investor, they offer flexibility and efficiency. And by investing through an ISA, UK investors can enjoy significant tax advantages, maximizing their returns and helping their money go further
Always take into account your investment goals and tolerance for risk. And do your own ‘due diligence’ – or consult a financial adviser – before investing. All investments carry a risk of loss.
As ever, if you have any comments or questions about this article, please do post them below. Bear in mind that I am not a qualified financial adviser and cannot provide personalized financial advice.
If you enjoyed this post, please link to it on your own blog or social media:
Rail travel is generally a comfortable, environmentally-friendly way of getting from A to B. But it can also be expensive, especially for longer journeys.
However, there’s a money-saving hack called ‘split ticketing’ that savvy travellers can use to reduce their fare costs – often by a substantial amount.
What is Split Ticketing?
Split ticketing involves breaking a journey into two or more smaller segments, purchasing separate tickets for each segment rather than one through-ticket. With the help of apps like Trainsplit, this process becomes simple and automated.
With split ticketing you still travel on the same train and follow your intended route. But instead of buying a single ticket from your starting point to your destination, you buy multiple tickets to and from stops along the route. This can result in significant savings without any need to change trains.
For example, say you’re travelling from London to Edinburgh. Instead of buying a direct ticket, you could split the journey into sections like London to York and York to Edinburgh. The train stops at York anyway, so you’re not inconvenienced, but the price could work out considerably cheaper.
Note that split ticketing only works if the train you’re on stops at the intermediate destination/s on your tickets. If it merely goes through them without stopping, this won’t be allowed.
Why Does Split Ticketing Work?
The UK rail fares system is complicated and confusing, with different pricing structures and promotional fares on offer for different parts of the same journey.
These pricing inconsistencies mean that splitting a trip into smaller segments can bypass some of the more expensive through-ticket fares. It’s a loophole in the system, but one that is perfectly legal. I have even had ticket inspectors comment approvingly when they see I am doing this!
How Do Apps Like Trainsplit Help?
Apps like Trainsplit do all the hard work for you. They automatically search for the best combination of tickets to get you to your destination at the lowest price.
You enter your starting point, destination and travel time, and the app generates options showing where you can split the journey and how much you will save.
If you have a Railcard that offers a discount (see below) this can be incorporated by the app as well. Just ensure you have the Railcard with you when you travel.
Example Savings
Let’s take a few real-world examples to illustrate just how much you can save with split ticketing.
London to Manchester
Standard fare: £90 (for a direct ticket)
Split ticketed fare: £65 (splitting at Milton Keynes and Stoke-on-Trent)
Savings: £25 (about 28%)
Edinburgh to Birmingham
Standard fare: £80
Split ticketed fare: £55 (splitting at Newcastle and York)
Savings: £25 (around 31%)
Bristol to Leeds
Standard fare: £85
Split ticketed fare: £58 (splitting at Birmingham New Street)
Savings: £27 (about 32%)
In each case, the split-ticketing options allow you to stay on the same train, without changing platforms or worrying about missed connections, while saving a significant percentage on your fare.
The app will show you the best split-ticket options, along with the potential savings.
Purchase the split tickets directly through the app.
The app even takes care of booking all the individual tickets at once, so you don’t have to make multiple transactions.
Other similar apps, like Trainline and RailEurope, also offer split ticketing features, though Trainsplit is especially focused on this. In my experience it typically offers the best savings, though you can of course try other apps as well to see if you can find a better option.
More Tips for Saving Money on Rail Fares
While split ticketing can make a significant difference, there are other ways as well to reduce the cost of rail travel:
Book in advance: Advance tickets are usually released 12 weeks before travel and are often much cheaper than buying on the day.
Travel at off-peak times: Fares are usually lower during off-peak hours (generally outside morning and evening rush hours).
Use a Railcard: If you’re eligible, a Railcard (such as the 16-25 Railcard, Two Together Railcard, or Senior Railcard) can save you up to a third on fares.
Check GroupSave offers: Some routes offer GroupSave discounts for groups of three or more travelling together.
Save on days out: Certain tourist attractions offer reduced-price admission (or two-for-one) if you go by train. For example, visitors to Madame Tussauds in London can get a third off the admission price if they travel by train. Check out the National Rail website for this and other offers.
Closing Thoughts
Travelling by train doesn’t need to break the bank, especially when using smart strategies like split ticketing.
With apps like Trainsplit, the process of finding the best deals is automated, making it easier than ever to save. By investing a few minutes in checking split-ticket options, you could potentially save a significant amount on your next journey, leaving more money in your pocket to spend at your destination!
Another approach to saving money on rail tickets is offered by a new website called Save My Fare. This is a platform that lets you buy or sell unwanted rail tickets. If your plans have changed, you can offer your unwanted ticket and receive up to 80% of the face value. You may also be able to buy tickets for your next journey at a discounted rate.
As ever, if you have any comments about this post, please do share them below.
This is a revised and updated version of an article first published on Mouthy Money.
If you enjoyed this post, please link to it on your own blog or social media:
Today I’m spotlighting a lesser-known government scheme which, if you’re eligible, can give your finances a valuable boost.
Help to Save is an initiative aimed at helping people on low incomes build up their savings. Offering generous tax-free bonuses, this scheme can provide significant benefits for qualifying individuals.
Here’s everything you need to know.
What is Help to Save?
Help to Save is a government savings scheme designed for people on Universal Credit.
For every £1 you save into your account, the government adds a 50p bonus, effectively giving you a 50% return. You can save up to £50 a month, with bonuses paid out at two key points over the four-year scheme.
How do the Bonuses Work?
Year 2 Bonus: After the first two years, you’ll receive a bonus worth 50% of your highest balance during that period.
Year 4 Bonus: At the end of the four years, you’ll receive a second 50% bonus based on the difference between your highest balance in years 3-4 and years 1-2.
So if, for example, you save the maximum £50 a month for two years, you’ll have £1,200 in your account. The government will then pay you a 50% bonus of £600.
If you continue saving £50 a month for the next two years, your balance excluding bonuses will be £2,400. You will then receive another £600, bringing your total bonuses to £1,200.
Putting it another way, in four years your investment of £2,400 will have accrued £1,200 in tax-free bonuses, giving you a total savings pot of £3,600. No bank savings account will offer you a guaranteed return anywhere near that!
Key Benefits of Help to Save
High returns: As mentioned above, a 50% bonus is significantly higher than any bank savings account interest rate
Flexibility: You can save as little or as much (up to £50 a month) as you like.
No risk: The scheme is government-backed, so there’s no chance of it going bust.
Tax-free: The bonuses are tax-free, and they aren’t treated as income for benefits purposes.
Easy withdrawals: You can withdraw savings any time if you need them (though frequent withdrawals may reduce your future bonuses).
No strings: The scheme is completely free and won’t affect your credit score. In addition, once you have been accepted on Help to Save, it doesn’t matter if your circumstances change.
Who is Eligible?
Recent changes have expanded eligibility for Help to Save to include all working Universal Credit claimants who earned £1 or more in their previous assessment period. The former minimum earnings threshold of £793 per month has been removed.
You must also live in the UK (or meet specific conditions if you live abroad as a Crown servant or member of the armed forces). You must also have a UK bank account.
The Help to Save scheme deadline has also been extended. You can now open an account until April 2027.
Are There Any Age Limits?
There are no specific age restrictions for opening a Help to Save account provided you meet the criteria above. Once you have qualified for the state pension, however, you will not be eligible to receive Universal Credit. That means if you’re coming up to retirement age (currently 66, gradually rising to 67 from 6 May 2026), it’s important to apply for the scheme before you reach that age.
How to Apply
Opening a Help to Save account is straightforward. You can apply online via the official government website or using the HMRC app.
Note that you will need a Government Gateway User ID and password. If you don’t have one of these already, you can create one during the application process.
Closing Thoughts
For those eligible Help to Save offers a valuable opportunity to build a savings pot, with the added advantage of tax-free government bonuses.
The scheme is designed to be simple and flexible, making it easy for individuals to develop a habit of saving and improve their financial security. If you qualify, it’s well worth considering as a step towards achieving a more stable financial future.
For more information and to apply, visit the government website. Don’t miss this chance to turn small, regular savings into a significant financial boost, before the scheme closes to new applicants in April 2027.
As always, if you have any comments or questions about this article, please do leave them below.
If you enjoyed this post, please link to it on your own blog or social media:
Whether you’re just starting, mid-career, or approaching retirement age, getting the right pension advice is crucial to ensure a secure and comfortable future.
Fortunately, there are many places in the UK (both free and paid) that offer pension guidance and tailored advice. In this blog post, we’ll explore reasons why you need pension advice, the best places to get help, and answer some frequently asked questions about pension advisers.
Why Would You Need Pension Advice?
Pensions are a vital part of your financial future, yet many people don’t fully understand how to approach pension problems or what investment options are available. Before we look at where you can find pension advice, here are a few common situations where seeking advice might be a smart move:
Near Retirement – As you approach retirement age, you’ll have to make important decisions such as when to access your pension, how to take your benefits, and how to minimise tax. Professional advice can help you make the most of your savings.
Multiple Pension Pots – If you have changed jobs frequently in the past, you might have multiple pension pots. Getting expert advice can help you trace and consolidate them efficiently, ensuring you don’t lose track of valuable funds.
Pension Transfers – Transferring pensions, especially from defined benefit (DB) schemes, can be risky if not handled carefully. Expert advice is essential to assess the risks and avoid losing valuable benefits.
Investment Choices – If you have a defined contribution (DC) pension, you can choose where your pension contributions are invested. Advice can help match your investment risk profile with your long-term goals.
Places To Get Pension Advice in the UK
Many organisations and platforms in the UK offer pension guidance and advice. Some are free and impartial, while others are professional financial advice services that may charge a fee.
Here’s a breakdown of some places where you can get pension advice:
1. Pension Wise
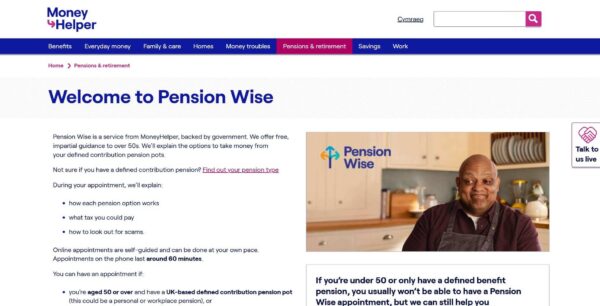
Pension Wise is a government-backed service offered through MoneyHelper. It offers free and impartial guidance to people aged 50 or over with a defined contribution pension. If you’re unsure about what type of pension pot you have, they have a service that helps determine whether or not you have a defined contribution pension. You can book a free appointment online or over the phone with a pension specialist who will explain how each pension option works, what tax you could pay, and how to identify scams. It also offers a helpline and webchat open Monday to Friday from 9 am to 5 pm.
Pros
Government-backed service
Free online and phone appointments
Suitable for people aged 50 or over with a defined contribution pension pot
Cons
You may not be able to get an appointment if you are under 50 or only have a defined benefit pension
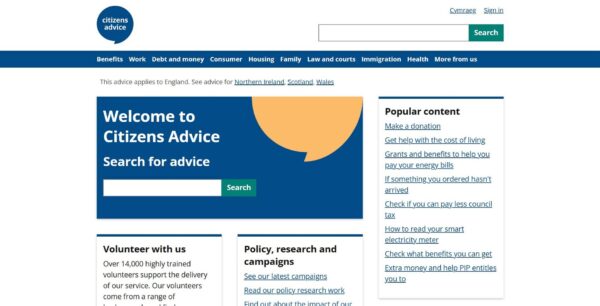
Citizens Advice is an independent organisation in the UK that provides free and confidential guidance on a wide range of financial issues, including pensions. They have a network of local charities in around 1,600 locations across England and Wales with 14,000 volunteers and 8,843 staff. You can contact a guidance specialist online, on the phone, or by visiting your local Citizens Advice branch. Their website is also a helpful resource for general information about state pensions, workplace pensions, personal pensions, and more.
Pros
Around 1,600 locations across the UK
Free face-to-face and phone appointments
A great resource for general pension information
Cons
You may not be able to get an appointment if you are under 50 or only have a defined benefit pension
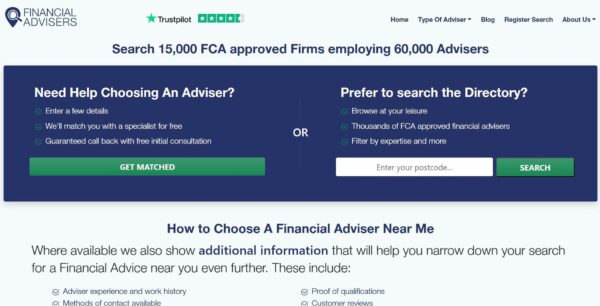
FinancialAdvisers.co.uk is an online platform with a database of over 60,000 FCA-approved financial advisers and 15,000 firms across the UK. It works by connecting people with a range of financial advisers based on their postcode. Users can enter their postcode in the directory and filter the results by pension and retirement advice to find a list of pension advisers nearby.
In addition, they also offer a ‘Get Matched’ service that matches you with a suitable adviser. By answering a few questions and entering your personal details, it allows you to find an FCA-regulated adviser in your local area and request a guaranteed call back.
Pros
Free directory to find pension advisers near you
Free ‘Get Matched’ service
Most pension advisers listed offer a free initial consultation
Cons
You have to make contact with advisers unless you get matched
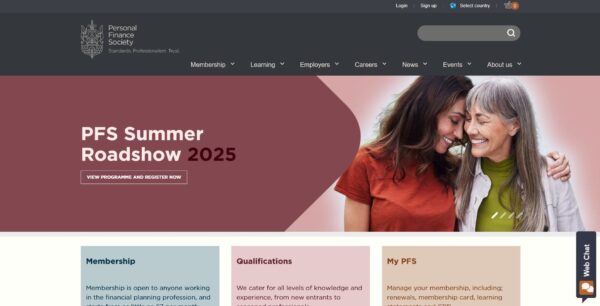
As a part of the Chartered Insurance Institute group, the Personal Finance Society (PFS) serves as the UK’s professional body dedicated to the financial planning sector. This organisation is committed to elevating standards and fostering professionalism across the sector, primarily aiming to enhance public trust and confidence.
The Personal Finance Society provides a free search tool on their website, enabling individuals to locate qualified advisers nearby. By inputting their location, users can refine their search based on their specialty, such as retirement pensions and annuities. The tool also allows for filtering options to show only chartered financial planners, specialists in later life and retirement planning, or advisers who can be contacted by email or telephone.
Pros
Free search tool to find advisers in your local area
All listed advisers are qualified and members of the PFS
Most advisers listed offer a free initial consultation
Age UK is a leading charity federation designed to provide support and guidance to older people on a wide range of topics, including pensions. They offer a free and confidential helpline and have specialist advisers at over 120 locations across the UK. The Age UK website provides general information on pension pots, state pensions, workplace pensions, finding old pensions, annuities, how to spot pension scams, and more.
Pros
Free and impartial guidance
Free helpline open 8 am to 7 pm, 365 days a year
Specialist advisers in over 120 locations across the UK
NEST (National Employment Savings Trust) is a popular workplace pension scheme in the UK designed to make automatic enrolment as easy as possible. The scheme was set up by the government and introduced by the Pensions Act 2008. Under the act, all employers in the UK are legally required to put eligible staff into a pension scheme and contribute towards the pension pot. This is to help staff save as much as possible for retirement.
Whatever pension provider you are with, it is worth seeking advice from them. If you’ve been auto-enrolled into a NEST pension scheme, they offer guidance and support on their website in a range of areas, such as how to grow your pension, transfers, contributions, pension tax, and more.
What is the Difference Between Pension Guidance and Advice?
Pension guidance helps you understand your options and make informed decisions, but it doesn’t recommend specific financial products or tell you what to do. It’s usually free and impartial and offered by services like Pension Wise and Citizens Advice. Pension advice, on the other hand, is provided by regulated financial advisers. They assess your financial situation and recommend specific actions or products for a fee.
Is It Worth Paying a Pension Adviser?
It depends on your circumstances. If you’re close to retirement or have multiple pension pots, paying for tailored advice can be a smart investment. A good adviser can help you avoid costly mistakes, optimise your tax position, and choose suitable investments.
How Much Does a Pension Adviser Charge?
Most pension advisers offer a free initial consultation and charge a fee for their services. These fees vary depending on the complexity of your situation and how the adviser charges. Typical fee structures include fixed, percentage-based (0.5% to 2% of the pension value managed), or hourly. Before working with an adviser, it is recommended that you ask about fee disclosure to avoid hidden costs.
Where to Go From Here for Pension Advice
Getting the right pension advice can mean the difference between a comfortable retirement and financial uncertainty. Whether you’re just starting to save, consolidating old pension pots, or deciding how to access your pension funds, it pays to seek help.
Start with free, impartial guidance services to understand your options. If your situation is more complex or you want advice tailored to your retirement goals, consider hiring a regulated financial adviser. With a wealth of resources available, planning for retirement doesn’t have to be daunting.
This is a collaborative post.
If you enjoyed this post, please link to it on your own blog or social media:
Today I’m sharing a guest article on a subject nobody likes to think about, but one that could be crucial to ensuring your financial security in later life..
Sadly, growing numbers of older people are seeing their marriages break down and having to undergo the painful process of divorce. Even if relatively amicable, this is likely to be stressful and emotionally exhausting. And – even worse – any mistakes you make now can have serious consequences for your finances, both now and into the future.
My guest today, Victoria Fellows, a partner and head of family at the Birmingham office of HCR Law, knows this very well. And she has some important advice for anyone who may find themselves in this situation.
Over to Victoria then…
Divorce rates among individuals aged 50 and over – often referred to as ‘silver splitters’ – have been on the rise in the UK over recent decades, with the number of over-60s legally separating doubling since the 1990’s. This trend contrasts with the decline in divorce rates across younger age groups. It can be put down to various factors, such as longer life expectancy, empty nest syndrome and the increasing numbers of financially independent women who are able to support themselves outside marriage.
At the end of 2024, the Law Commission published a scoping report on financial remedies on divorce. This indicated that 60% of the couples who divorced in 2023 had not properly dealt with their finances upon divorce, sometimes thinking it was not worth obtaining an order from the court as they believed they had no assets justifying the expense of formally separating their finances.
So while these couples are now divorced, both parties remain vulnerable to a financial claim application from their former spouse at any point until they remarry or die. The case of Vince v Wyatt illustrated why this was a mistake. The parties had nothing when they divorced and did not bother to get a clean break order. Post separation, Mr Vince became a multi-millionaire through his own business activities. Mrs Wyatt was allowed to bring financial claims against him 20 years after the divorce, resulting in a significant financial award being made in her favour.
Resolving financial issues during a divorce is therefore crucial for both immediate stability and long-term security. This is especially true for silver splitters undergoing ‘grey divorce’ – another term referring to divorces in later life. Unlike their younger counterparts, they will not have years of working life ahead of them to build up savings or pensions. It is therefore crucial that the marital assets are divided fairly to help ensure that both spouses have financial security during their retirement. There is also the possibility that in their fifties or sixties, one spouse will come into a substantial inheritance post-divorce which, without a financial remedy order, the former spouse could make a claim on in the future.
So What Do Financial Agreements Look Like?
As a result of being married, both parties have a number of financial claims that they can make against each other. The orders that a court can make are as follows:
Orders for maintenance pending suit (‘interim’ spousal maintenance)
Periodical payments orders (spousal maintenance for joint lives, specific term and/or a nominal amount)
Lump sum orders
Property adjustment orders
Pension sharing orders
In deciding whether to make any of the above orders, the court must consider all the circumstances. These will include:
a) The income, earning capacity, property and other financial resources of each party or what they are likely to have in the foreseeable future, including any increase in that earning capacity.
b) The financial needs, obligations and responsibilities which each of the parties to the marriage has or is likely to have in the foreseeable future.
c) The standard of living enjoyed by the parties before the breakdown of the marriage.
d) The age of each party to the marriage and duration of the marriage.
e) Any physical or mental disability of either party to the marriage.
f) The contributions which either of the parties have made or are likely to make in the foreseeable future to the welfare of the family, including any contribution by looking after the home or caring for the family.
In every case the court also has to consider whether a ‘clean break’ is appropriate. A clean break is where the parties’ finances are arranged to allow them to separate without any further financial responsibility for each other. While the court must give consideration to this, it does not mean that there can or should be a clean break in every case. This will necessarily depend upon the other factors involved.
How Are Agreements Reached?
There are a number of ways in which financial matters can be resolved:
Discussions directly between the parties if they are able to discuss and agree a financial settlement that both of them are comfortable with.
Mediation where both parties try to reach agreement between themselves with the assistance of a trained mediator.
Negotiation through solicitors. Each party can appoint a solicitor to negotiate on their behalf. This approach is suitable for complex financial situations or when mediation isn’t appropriate.
Other forms of dispute resolution. Arbitration and collaborative law are further alternatives. Arbitration is effectively a ‘private’ process that largely mirrors court proceedings but where the parties have more control in particular in respect of timescales. Collaborative law is a separate process which may only be suitable in certain circumstances. Each person appoints their own collaboratively trained lawyer and both parties and their lawyers meet together to work things out face to face.
Financial remedy proceedings. If all other options fail, it may be necessary for formal court proceedings to be issued to resolve financial matters. An application for financial remedy can only be commenced after a Divorce Petition has been filed with the court. The proceedings usually involve attending court on three occasions. If financial settlement is not agreed at either of the initial two hearings, or in between them, then a final hearing will be listed at which the Judge after hearing evidence makes a decision that is binding on the parties. This would be the most cost-prohibitive option and can end with resolution of financial matters being taken entirely out of the parties’ hands.
Top Tips to Make the Process Easier
Seek professional advice as soon as possible. Consult with financial advisors and solicitors who are experienced in later-life divorce and can help navigate complex financial issues and ensure a fair settlement is not only reached but also incorporated into an order to be approved by the court.
Enter into full financial disclosure to ensure that all assets are disclosed and taken into consideration when looking at overall settlements that plan for short- and long-term financial security. This will take time, so start sorting out your paperwork early. This is likely to include bank statements, pension records and documents relating to any other investments you might have, e.g. premium bonds, stocks and shares, rental income, and so on.
Remember to consider wills and estate planning as divorce does not automatically revoke a will. It’s crucial to update wills to reflect new circumstances and ensure assets are distributed according to current wishes.
Divorcing later in life presents unique challenges, but with careful planning and professional guidance, it is possible to navigate the process and achieve a fair and secure financial settlement.
Victoria Fellows (pictured, below) is a partner and the head of the family team of the Birmingham office of HCR Law.
Many thanks to Victoria and her colleagues at HCR Law for an eye-opening article on this important topic. If you are unfortunate enough to find yourself in this situation, devoting some attention to financial planning now can potentially save you and your family a lot of grief in the future.
As always, if you have any comments or queries about this article, please do leave them below.
If you enjoyed this post, please link to it on your own blog or social media: