My Investments Update - May 2025

My Investments Update – May 2025

Here is my latest monthly update about my investments. You can read my April 2025 Investments Update here if you like.

I’ll begin as usual with my Nutmeg Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

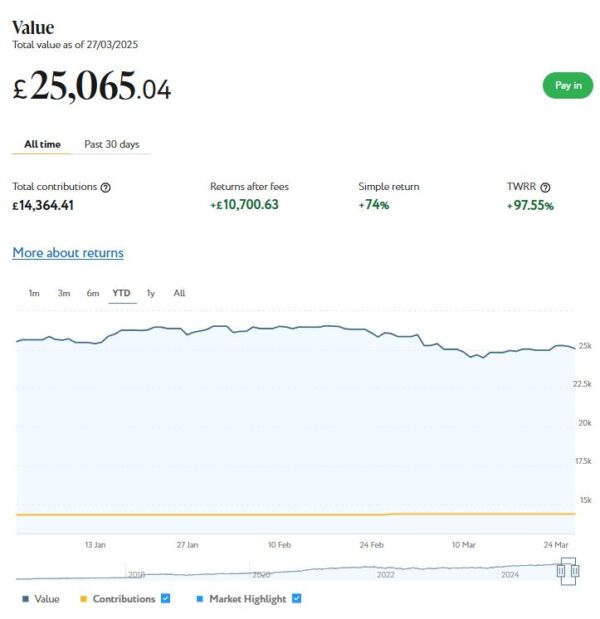
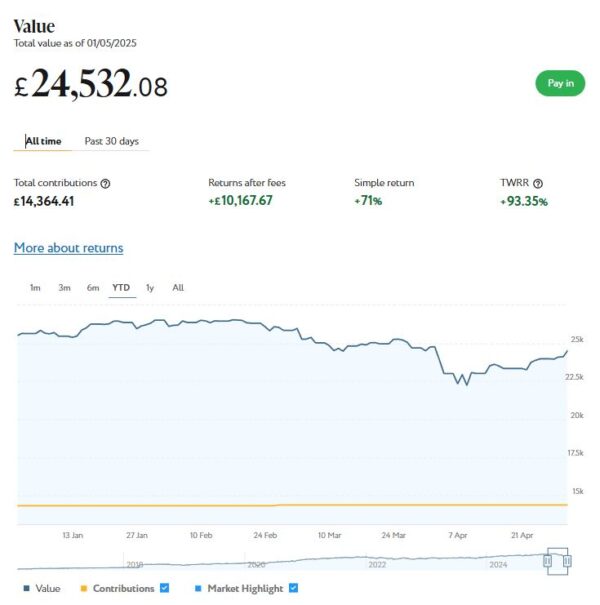
As the screenshot below for the year to date shows, my main Nutmeg portfolio is currently valued at £24,532. Last month it stood at £25,065, so that is a fall of £533.
Nutmeg main port May 2025

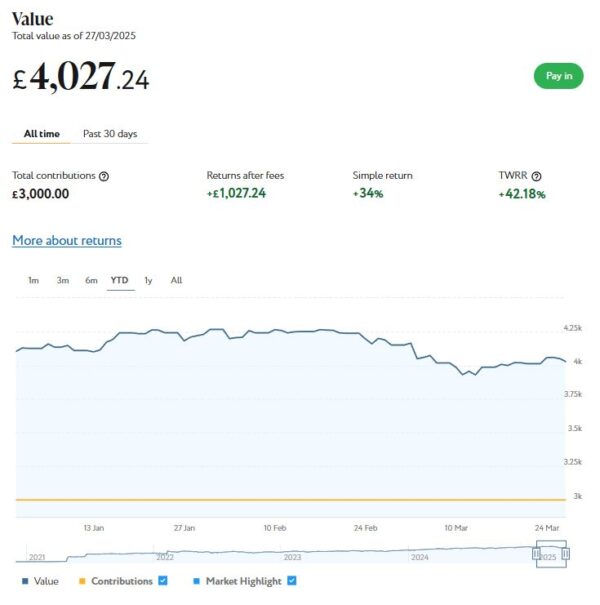
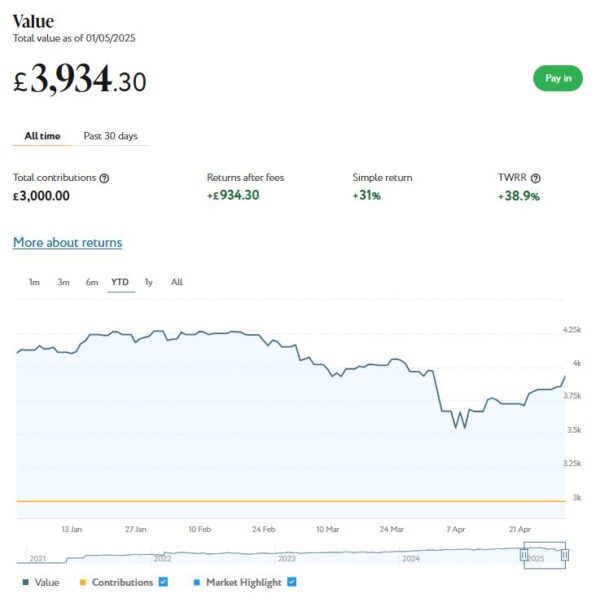
Apart from my main portfolio, I also have a second, smaller pot using Nutmeg’s Smart Alpha option. This is now worth £3,934 compared with £4,027 a month ago, a fall of £93. Here is a screen capture showing performance for the year to date.
Nutmeg Smart Alpha May 2025

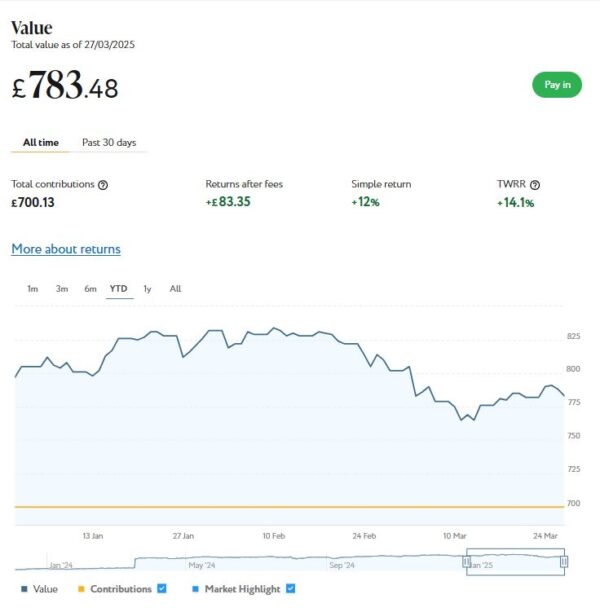
Finally, at the start of December 2023 I invested £500 in one of Nutmeg’s new thematic portfolios (Resource Transformation). In March I also invested a further £200 from referral bonuses. As you can see from the YTD screen capture below, this portfolio is now worth £770 compared with £783 last month, a fall of £13.
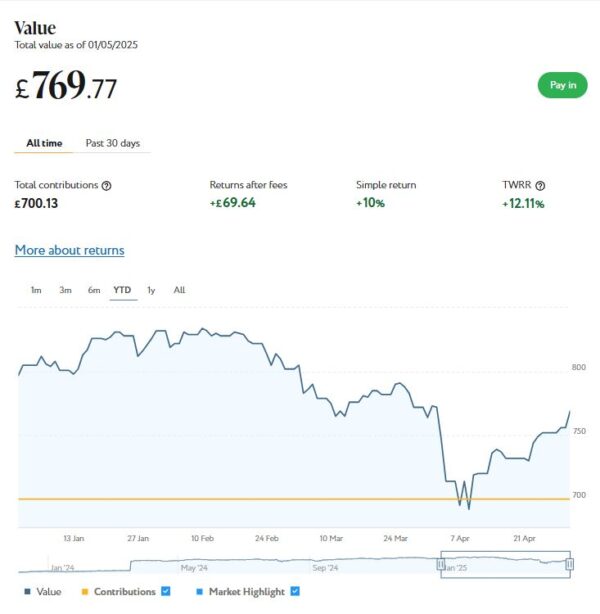
Nutmeg Thematic May 2025

As you can see, April was a roller-coaster month for my Nutmeg investments. There were some big dips in the early part of the month, followed by a partial but nonetheless welcome recovery. Overall I am down by £639 over the month. This is mostly due to the continuing instability in world markets, caused by the trade tariffs imposed by US President Donald Trump and other economic factors.

Nonetheless, the value of my Nutmeg investments is still up £838 in the last twelve months. And their value has increased by £2,920 or 11.10% since the start of January 2024. So the recent falls do need to be taken in context. Ups and downs are always to be expected with stock market investments, and over time they tend to even themselves out. In general the worst thing you can do is panic and sell up when downturns occur, as you are then crystallizing your losses. This is something I had cause to discuss recently in this blog post.

You can read my full Nutmeg review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last eight years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Assetz Exchange. As discussed in this recent post, the company recently rebranded as Housemartin.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £245.97 in revenue from rental income. I have also made a profit of £4.78 on property disposals. Capital growth has slowed, though, in line with UK property values generally.

At the time of writing, 18 of ‘my’ properties are showing gains, 1 is breaking even, and the remaining 18 are showing losses. My portfolio of 37 properties is currently showing a net decrease in value of £54.67. That means that overall (rental income and profit on disposal minus capital value decrease) I am up by £196.08. That’s still a decent return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

The net fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my full review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].

In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

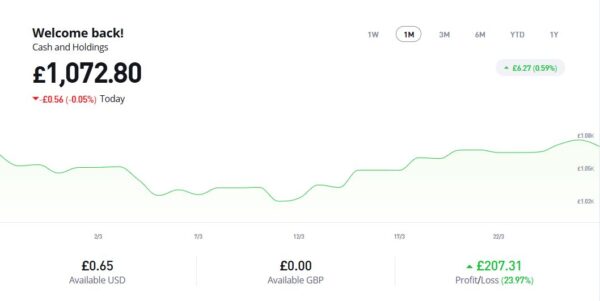
As you can see from the screen captures below, my original investment (total value £888.36 in pounds sterling) is today worth £975.36, an overall increase of £87 or 9.79%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.
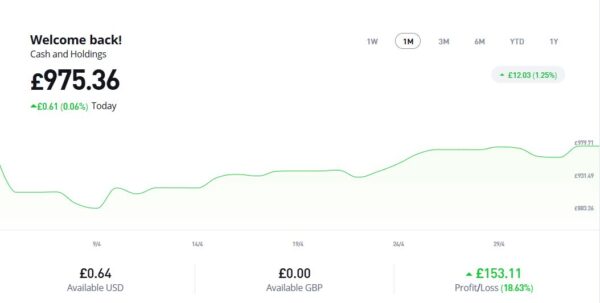
eToro main May 2025

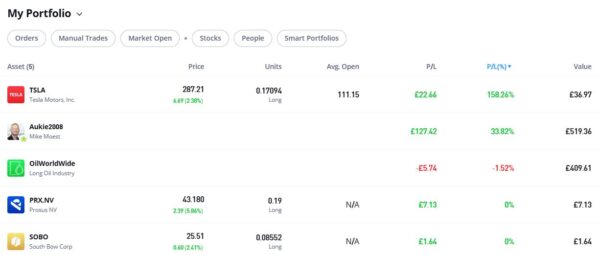
eToro port May 2025

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this recent post. The latter also reveals why I took the somewhat contrarian step of choosing the oil industry for my first thematic investment with them.

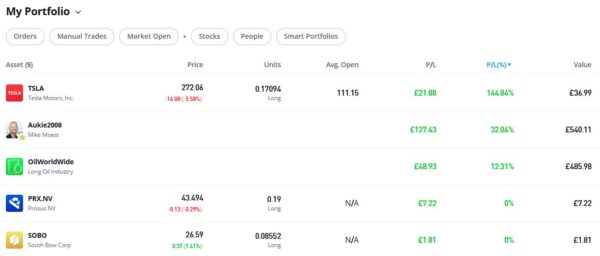
As you can see, my Oil WorldWide investment has seen a downturn in April and is actually worth marginally less than when I invested. That’s clearly disappointing after last month’s improvement, but reflects the global economic turmoil caused largely by US President Trump’s tariffs.

Thankfully my copy trading investment with Aukie2008 has been doing better, with an overall 33.82% profit. To be fair, I have held this investment a little longer.

My Tesla shares, which I bought as an afterthought with a bit of spare cash I had in my account, have done particularly well since I bought them, with an overall profit of 158.24%. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio!

  • eToro also offer the free eToro Money app. This allows you to deposit money to your eToro account without paying any currency conversion fees, saving you up to £5 for every £1,000 you deposit. You can also use the app to withdraw funds from your eToro account instantly to your bank account. I tried this myself and was impressed with how quickly and seamlessly it worked. You can read my blog post about eToro Money here. Note that it can also serve as a cryptocurrency wallet, allowing you to send and receive crypto from any other wallet address in the world.

If you would like more information about setting up an eToro account, please click on this no-obligation website link [affiliate]. Don’t forget that you also get a free $100,000 virtual portfolio, which you can use to experiment with trading and investing strategies. I have certainly earned a lot from mine.

Finally, just for fun I put £50 into an investment ISA with Trading 212. As mentioned in my recent blog post about dividend investing, I put it into the (Almost) Daily Dividends Portfolio, a ready-made portfolio or ‘pie’ on Trading 212. As you can see from the screen capture below, my account is already in profit, and has even accrued 2p in dividends!
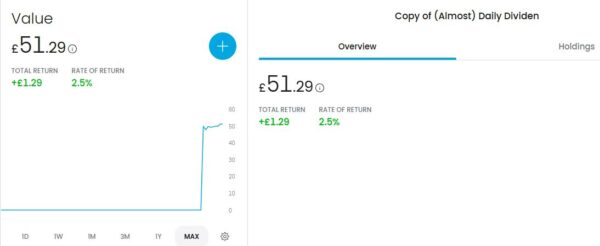
Trading 212 dividend pie May 2025

Moving on, as I said last time, I am no longer writing for the Mouthy Money website, as they have decided to take their content creation in-house. From a personal perspective I am obviously disappointed about this, but I had a good run with them and wish them every success going forward. You can still read all the articles I contributed to Mouthy Money over the years by visiting my profile page on the website. How long they will keep this in place I really can’t say!

In April I did have a guest post on my friend Sally Jenkins’ writing blog. Sally asked me some questions about my writing career for a regular feature she runs on her blog. I enjoyed answering the questions, which included “What are the most important qualities required by a writer?” and “What writing resources have you found most useful?” If you have any interest in writing, hopefully you may find this of interest.

I also published several posts on Pounds and Sense in April. I have listed below those that are still relevant

In Why Now Could Be the Ideal Time to Take Advantage of Your New Tax-Free ISA Allowance, I pointed out that everyone received a new £20,000 ISA allowance from the start of the new tax year on 6 April 2025. My article sets out some good reasons for taking advantage of the new allowance sooner rather than later, especially in light of persistent rumours that the government plans to restrict the allowance (for cash ISAs at any rate) in the autumn budget.

Why Has My Bank Abandoned Me? is an opinion piece by a writer friend who has asked to be known at SD. In it she laments the changes at UK banks in recent years that have hit older customers (in particular) hard. I could certainly relate to some of the experiences she describes in her article. Take a look and see if you agree.

I’ve already mentioned my post about Why UK Retirees Shouldn’t Panic Over Trump’s Tariffs and Market Wobbles. In this I pointed out that whilst the recent downturn is disappointing for investors, the worst thing you can do is panic and sell up, as this will crystallize your losses. In this post I draw a parallel with the Covid crash and point out that this was followed by a sustained rise in stock market values. Of course, nobody knows how current events will play out, but hopefully the upward trend seen over the last couple of weeks will continue. In any event, historically stocks and shares have delivered better returns than savings accounts over most periods of five years or longer.

Tow Like a Pro – Caravan Safety Tips From the Experts was a guest post from my friends at Compass, who are specialist leisure and caravan insurers. The post reveals the most common causes of accidents with caravans and sets out some top tips for staying safe when towing one.

Finally, How to Publish Your Book (and Earn Royalties) was a guest post from my writing friend Sally Jenkins (as mentioned earlier I had a guest post published myself on Sally’s blog in April). In her article, which generated a lot of interest, Sally set out the main options for getting a book published and making money from it. She also revealed some resources she has used herself in her successful freelance writing career.

I’ll close with a reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as we have to call it now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out.

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. For the time being anyway, Twitter/X will remain my primary social media platform, but I will also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!


If you enjoyed this post, please link to it on your own blog or social media:
Why Has My Bank Abandoned Me?

Guest Post: Why Has My Bank Abandoned Me?

Today I am sharing something a bit different – an opinion piece by a fellow writer who asks to be known as SD.

In her article, SD expresses her frustration with banks who no longer seem to care about their customers, especially the older ones. I guess this is something many Pounds and Sense readers may be able to relate to.

Over to SD, then…


I just read in the news about yet another banking app outage – this time, with serious consequences. Salaries were delayed, house moves disrupted, and critical money transfers put on hold. Everything ground to a halt, with no clear resolution in sight. And it got me thinking – if AI is so advanced, why can’t it fix outages like this?

Paying bills was stalled, and customers were understandably frustrated. These outages seem to be happening far too often. Yes, it’s 2025, but are our banking systems really ready for a fully digital future?

Not long ago, I was a customer of a high street bank. After years of in-person banking, staff encouraged me to “go digital” and use their app. I was reluctant. As someone who experiences anxiety and panic attacks, I find complex IT systems overwhelming. I’m over 57 – I wasn’t raised in the digital age.

Despite me sharing my concerns, the bank staff didn’t really listen. A sign on the wall said “Not all disabilities are visible”, yet this clearly didn’t apply to me. My local branch, which was always busy, was shut down – ATM and all. Another nearby branch followed suit. There was one left five miles away, but eventually even that became digital only.

When I visited and explained my situation, I was told bluntly that I couldn’t be helped – there were no counters any more. I didn’t need anything complicated. Just a basic, face-to-face banking service. Instead, I was simply dismissed. Invisible disabilities, it seems, were invisible to them too.

So I closed my account and went to another high street bank – only to be met with more unwelcome change. Gone was the polished wood floor and staffed counters. In their place: low, foam seats and whiteboards hiding the old counter space. It felt less like a bank and more like a waiting room.

These trendy seating areas? Not great if you’re elderly or disabled.

Still, I figured sitting here was better than trying to deal with a chatbot. Banks think chatbots are a great innovation, but they’re not yet smart enough to help with specific, real-world banking issues. I’ve tried. It’s frustrating. And I thought AI was supposed to solve problems?

There were only three staff members at the new branch, all run off their feet. When I asked about opening a new account, I was told I needed a smartphone. I declined and walked out.

If they still had real counters and six staff members, people might not mind standing in line. They’d actually get served.

Which brings me back to banking app outages – again. They’re frequent, disruptive, and a growing source of frustration. Yet I was told digital banking was “the future” and that I’d be left behind if I didn’t.

Tell that to the millions of customers now stuck in this digital mess. It’s a financial farce.

Call me a tech dinosaur, but I truly believe shutting down mass branches was one of the worst decisions banks ever made. Staff lost jobs. Customers lost peace of mind.

It all worked just fine – until the banks decided to “modernize”.

Yes, a few banking hubs have popped up. But most town-centre branches now sit empty, derelict, and forgotten. It’s a sad waste of once-useful community spaces.


Many thanks to SD for a thought-provoking (and clearly heart-felt) article.

I do agree that the so-called digital revolution has made life harder for many older people and those with disabilities. Yes, some have taken to banking apps and online banking without major issues. I have a friend in his eighties to whom I had to give a crash course after his wife (who previously handled all their finances) passed away. Despite my concerns he soon got the hang of it and uses his bank’s app like a professional now.

But plenty of older people do struggle, especially with apps and complicated online security systems. And clearly it doesn’t help if your memory and eyesight aren’t as good as they once were. I can understand why so many older folk yearn for times gone by, when you could speak to a real-life individual and they would help you with whatever issues you might be having.

But what do YOU think? Have the banks really abandoned older customers, or do we just need to accept change and “get with the programme”? I’d love to hear your views and experiences, as would SD!


If you enjoyed this post, please link to it on your own blog or social media:
Why UK Retirees Shouldn't Panic Over Trump's Tariffs

Why UK Retirees Shouldn’t Panic Over Trump’s Tariffs and Market Wobbles

If you’ve been watching the news lately, you’ll probably have seen headlines about stock markets taking a tumble thanks to a wave of tariffs announced by Donald Trump. It’s enough to make any retiree feel uneasy – especially if your pension is tied to the markets.

But before you start panicking or making any big changes, take a deep breath. Here’s what you really need to know.

What’s Going On?

President Trump’s tariffs are stoking fears of a global trade war. Investors don’t like uncertainty, and the markets are reacting with volatility. There have been drops not just in the US but across the globe, including here in the UK.

For retirees, that can feel personal. If your pension pot or retirement income is invested in stocks and shares, you might be wondering: Am I going to be okay?

Short answer: Yes, if you stay calm and avoid knee-jerk reactions.

Why This Isn’t the Time to Panic

Markets have always had ups and downs. That’s not new. Whether it was the financial crisis of 2008, the Brexit vote, or the COVID crash (see below), every downturn has sooner or later been followed by recovery.

If you sell investments during a dip, you lock in those losses. But if you ride it out, your portfolio has every chance to bounce back, as has happened before. History is on your side.

Speaking of which…

Consider The Covid Crash

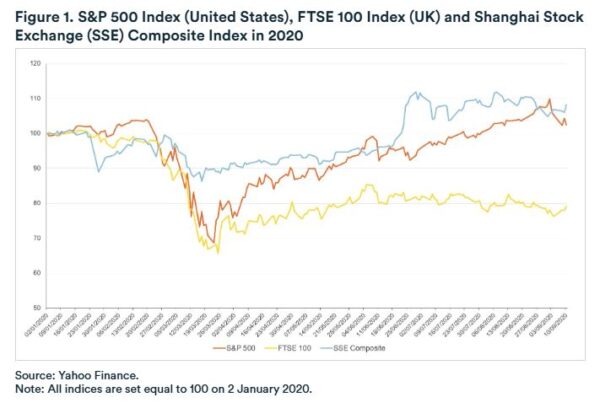
In early 2020 it became clear that COVID was going to be a massive deal, and markets world-wide fell dramatically. And yet by mid-March, as the chart below from Yahoo Finance reveals, they were already recovering.

Covid recoveryThe recovery in stock market values continued through 2021. If you check out my in-depth review of the Nutmeg robo-adviser investment platform, you can see this for yourself. Overall, the period from March 2020 to December 2021 saw a big rise in the value of my Nutmeg investments. If I had panicked in early 2020 and withdrawn all my money then, I would certainly have been thousands of pounds worse off.

Your Pension Is Built to Withstand This

Most UK pensions – especially workplace and private pensions – are designed for long-term sustainability. They’re usually diversified across different types of assets like stocks, bonds and property. This helps soften the blow when markets get rocky.

If you have a defined benefit pension, you’re likely shielded from market fluctuations altogether. These pensions pay a fixed income and aren’t directly tied to the stock markets.

For those with defined contribution pensions – the majority of us these days – yes, the value can go up and down. But remember, pensions are managed by professionals who adjust strategies to navigate global changes like the current one.

What You Can Do (Instead of Worrying)

  1. Check in with your adviser – They can help you understand how exposed your pension is to current events and whether any changes are needed. See also my article on Why Over-50s May Need an Independent Financial Adviser.

  2. Keep a cash buffer – If possible have a few months’ worth of living expenses in cash or savings, so you’re not forced to sell your investments during market lows.

  3. Stay diversified – A mixture of investments across regions and sectors helps spread risk.

  4. Ignore the noise – Newspaper headlines are designed to grab attention. Focus on your long-term goals instead.

One other point is that, if you’re in the early days of retirement especially, dips can present an opportunity to buy while values are depressed, in the hope of gaining when (hopefully) they recover. This won’t be appropriate for everyone and it’s important to proceed cautiously. Timing the market is notoriously difficult, and if you get this wrong you can lose money rather than making it. But if you are careful (and not overly risk-averse) there are undoubtedly opportunities to be found at these times.

Bottom Line

Trump’s tariffs might be shaking the markets, but your retirement doesn’t have to be shaken with them. Your pension plan is more robust than you might think, and a temporary dip doesn’t mean disaster.

If you’re feeling anxious, that’s normal – but don’t let fear drive your financial decisions. Speak to a financial adviser if you need reassurance (I have one myself) and above all, keep your cool. Retirement is a long game, and a smart strategy will see you through.

As always, if you have any comments or questions about this article, please do leave them below.

DISCLOSURE: I am not a professional financial adviser and nothing in this article should be construed as personal financial advice. If you are uncertain how best to proceed, I strongly recommend speaking to a qualified financial adviser or planner. They will take the time to fully understand your particular circumstances and advise you how best to proceed. All investing carries a risk of loss.

Housemartin

If you enjoyed this post, please link to it on your own blog or social media:
Tow Like a Pro - Caravan Safety Tips from the Experts

Tow Like a Pro – Caravan Safety Tips From the Experts

The weather is warming up at last. And that means many Brits will be planning a trip with a caravan, in some cases for the first time.

So today I’m sharing some top tips to ensure you (and your caravan) stay safe and reach your destination without any dramas. This post has been written in association with my friends at Compass, who are specialists in caravan and leisure insurance

As staycations continue to boom across the UK, more and more drivers are taking to the roads with caravans in tow. But with this rise in travel comes a sharp reminder: towing a caravan can be tricky, especially for the inexperienced.

According to recent claims data from Compass, a whopping 60.5% of touring caravan insurance claims are due to accidental damage. With the Easter holidays almost here and thousands of caravan enthusiasts preparing for trips, taking precautions on the road is more important than ever.

The Most Common Causes of Accidental Damage

Accidents often occur during reversing, navigating tight spots, or colliding with stationary objects like posts and curbs. Kevin Minnear, Head of Underwriting at Compass, explains:

“Accidental damage claims typically arise from drivers struggling with visibility and alignment when reversing. Misjudging turn angles or road positioning can result in costly repairs. Swaying at high speeds or during windy conditions is also a major factor, particularly for less experienced drivers.”

Caravan sites, service stations, and even parking areas can become challenging environments for manoeuvring, especially without prior practice or the right equipment.

Top Towing Tips to Help Prevent Accidents

To help you stay safe and avoid unnecessary claims, Compass shares these essential towing safety tips:

  • Check your towing match: Make sure your vehicle is suitable for towing your caravan. A good rule of thumb is the 85% rule – your caravan’s laden weight should not exceed 85% of your car’s kerb weight.

  • Distribute weight wisely: Keep heavy items low and close to the axle to maintain balance and reduce the risk of swaying.

  • Practice makes perfect: Reversing and manoeuvring can be difficult – especially under pressure. Practice in a quiet, open space and consider using a spotter or installing a reversing camera.

  • Adjust your driving: Towing affects acceleration, braking, and cornering. Drive at moderate speeds, allow for longer stopping distances, and watch out for crosswinds.

  • Run pre-journey checks: Check tyre pressures, lights, towing connections, wheel nuts, and mirrors before every trip.

  • Know the law: Ensure you have the correct driving licence and stick to legal speed limits: 60 mph on motorways and dual carriageways, and 50 mph on single carriageways.

Insurance and Training Matter

With accidental damage such a common issue, having the right insurance is crucial. Caravan insurance is separate from car insurance and is necessary to cover damages specific to your caravan.

Minnear adds:

“Many caravan accidents are avoidable with the right precautions. We encourage all caravan owners to familiarize themselves with safe towing practices and ensure their insurance covers what they need. DVSA-accredited towing courses are a great way to build confidence – and some insurers even offer discounts to those who complete them.”

As more Brits embrace caravanning, being informed and prepared is key – not only for protecting your caravan but also for ensuring your family’s safety and that of others on the road.

For more information about specialist caravan and leisure insurance, visit compass.co.uk.


Many thanks again to my friends at Compass for their assistance with this article. If you’re holidaying in a caravan this Easter – or later in the summer – I do hope your journey is both safe and enjoyable.

Happy caravanning!

As always, if you have any comments or questions about this article, please do leave them below.


If you enjoyed this post, please link to it on your own blog or social media:
How to Publish Your Book

Guest Post: How to Publish Your Book (and Earn Royalties!)

Today I’m pleased to bring you a guest post from my friend and near-neighbour Sally Jenkins, a successful published fiction and non-fiction author (check out her latest novel Out of Control – a later-life romance perfect for summer holiday reading!).

Many older people (in particular) harbour an ambition to write a book and make money from it. If that includes you, I hope you will find Sally’s article of interest. In it she sets out the main options for getting your book published, and shares some valuable resources she has found.

Over to Sally then…


Everyone has at least one book in them, or so the saying goes. It might be a thriller, a memoir, a collection of poems or short stories, a ‘how-to’ non-fiction manual or something completely different. Finishing that manuscript is a laudable achievement in itself but don’t stop there. It takes guts to send any literary work out into the public arena; however, doing so can lead to an additional passive income stream in the form of royalties that continue to hit your bank account long after you’ve finished writing.

There are three main routes to publication that you might like to consider:

Traditional Publishing

Traditional publishers come in all shapes and sizes, from the giants like Penguin and Hachette to far smaller, less well-known companies who publish in e-book format only.

Traditional publishers bear all the costs of publishing a book, meaning there is no financial risk for the author. These costs may include editing, proofreading, cover design, marketing and the printing of physical copies. The author contributes nothing to these costs and receives a small royalty for each copy of the book sold.

The competition to be signed by a traditional publisher is fierce and only a very small number of authors are taken on. The larger companies will only accept manuscript submissions via a literary agent but it is possible for authors to submit directly to many of the small publishing houses. There is nothing to lose by trying this traditional route but be prepared to develop a thick skin to deal with the probable rejections. A good place to start is an up-to-date copy of the Writers’ and Artists’ Yearbook, which contains a comprehensive list of publishers and literary agents.

Partnership Publishing

In the partnership publishing model, the publisher and the author share the financial risk of publishing the book. This means the author will be asked to make a financial contribution towards the publishing costs. What proportion and how much this means in monetary terms will vary from company to company, so it’s worth approaching more than one partnership publisher and requesting explicit information about their offering. In return for contributing to the publishing costs, the author can expect to receive a higher percentage of royalty payments than under the traditional model.

However, care is needed when choosing a partnership company to work with – there are many rogue or ‘vanity’ publishers out there who will publish anything and charge a lot of money for very little service. Ensure that the company you choose has a manuscript selection process – even if this means you might face rejection as in the traditional model. A true partnership publisher will only publish books that it thinks have merit and will sell. Even so, there is no guarantee that you will recoup all or any of your publishing costs via royalties. Do not spend more than you can afford to lose.

The Writers’ Beware website has a section devoted to avoiding vanity publishers.

Self-Publishing

Authors who self-publish carry all the financial risk themselves but retain all the royalties (bar the amount taken by distribution platforms such as Amazon). It is possible to self-publish on Amazon at no cost or you might choose to spend hundreds of pounds depending on what services you buy in. The main services requiring financial outlay will be:

Cover Design – don’t attempt this yourself unless you are a graphic designer with a knowledge of the book covers currently selling in your genre. An amateur cover design will be obvious and off-putting to potential readers.

Editing – a novel (particularly a first novel) may benefit from a full structural edit. This will advise on plot, character development, pace etc. You might also want to consider a sentence level copyedit and/or proofread.

Formatting – some authors pay for this but, with a little patience, anyone who can use Microsoft Word can do this themselves.

Printing – there is no need to pay for a print run of books and hold them in stock.

Amazon (and other companies) use print-on-demand (POD) technology. This means that when someone orders a copy of your book it is printed individually and sent direct to the customer. Authors can also order copies at a reduced rate to sell direct to friends, family or the public at large.

The Alliance of Independent Authors has a directory of reputable editors, cover designers, proofreaders, etc. The directory also lists companies who can offer a complete self-publishing service for authors who don’t want to do any of the leg work – but this can be very expensive. As with partnership publishing, never spend more than you can afford to lose.

KIndle Direct Publishing for Absolute Beginners If you would like to know more about low-cost self-publishing via Amazon, the e-book Kindle Direct Publishing for Absolute Beginners (pictured, left) offers a good introduction. If you don’t currently read on Kindle, download the free Kindle app to your laptop, tablet or smartphone.

Whichever publishing route you choose, enjoy the journey and the royalties!

Sally JenkinsBio: Sally Jenkins (pictured, right) currently writes uplifting and hopeful novels for the traditional publisher Choc Lit (part of Joffe Books). She has also had a novel published in partnership with The Book Guild and has self-published several books via Amazon KDP. When not at the keyboard, she feeds her addiction to words by working part-time in her local library and running two reading groups. Sally can also be found walking, church-bell ringing and enjoying shavasana in her yoga class. Follow her writing blog at https://sally-jenkins.com/.


If you enjoyed this post, please link to it on your own blog or social media:
Investments Update April 2025

My Investments Update – April 2025

Here is my latest monthly update about my investments (slightly earlier than usual due to other commitments). You can read my March 2025 Investments Update here if you like.

I’ll begin as usual with my Nutmeg Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

As the screenshot below for the year to date shows, my main Nutmeg portfolio is currently valued at £25,065. Last month it stood at £25,850, so that is a drop of £785.

Nutmeg main port April 25

Apart from my main portfolio, I also have a second, smaller pot using Nutmeg’s Smart Alpha option. This is now worth £4,027 compared with £4,151 a month ago, a fall of £124. Here is a screen capture showing performance for the year to date.

Nutmeg Smart Alpha April 25

Finally, at the start of December 2023 I invested £500 in one of Nutmeg’s new thematic portfolios (Resource Transformation). In March I also invested a further £200 from referral bonuses. As you can see from the YTD screen capture below, this portfolio is now worth £783 compared with £803 last month, a fall of £20.

Nutmeg Thematic port April 25

As you can see, March has been another disappointing month for my Nutmeg investments. Overall I am down by £929. This is mostly due to the continuing instability in world markets, caused by the the trade tariffs imposed by US President Donald Trump and other economic and social factors.

Nonetheless, the value of my Nutmeg investments is still up £1,477 in the last twelve months. And their value has increased by £3,559 or 13.52% since the start of January 2024. So the recent falls do need to be taken in context. Ups and downs are always to be expected with stock market investments, and over time they tend to even themselves out. In general the worst thing you can do is panic and sell up when downturns occur, as you are then crystallizing your losses. Indeed, I am considering topping up some of my investments now while values are depressed. That’s just how I’m thinking, of course, and doesn’t constitute investment advice!

You can read my full Nutmeg review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last eight years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Assetz Exchange. As discussed in this recent post, the company recently rebranded as Housemartin.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £238.70 in revenue from rental income. Capital growth has slowed, though, in line with UK property values generally.

At the time of writing, 15 of ‘my’ properties are showing gains, 2 are breaking even, and the remaining 19 are showing losses. My portfolio of 36 properties is currently showing a net decrease in value of £52.78, meaning that overall (rental income minus capital value decrease) I am up by £185.92. That’s still a decent return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

The overall fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my full review of Assetz Exchange/Housemartin here and my article about the rebranding to Housemartin here. You can also sign up for an account directly via this link [affiliate].

In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

As you can see from the screen captures below, my original investment (total value £888.36 in pounds sterling) is today worth £1,072.80, an overall increase of £184.44 or 20.76%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.

Etoro Home April 2025

Etoro port April 2025

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this recent post. The latter also reveals why I took the somewhat contrarian step of choosing the oil industry for my first thematic investment with them.

As you can see, my Oil WorldWide investment is currently showing a profit of 12.31%. That’s a welcome improvement since the portfolio was rebalanced by eToro. The investment team at eToro periodically rebalance all smart portfolios to ensure that the mix of investments remains aligned with the portfolio’s goals, and to take advantage of any new opportunities that may present themselves.

My copy trading investment with Aukie2008 has been doing better, with an overall 32.06% profit. To be fair, I have held the latter investment a bit longer.

My Tesla shares, which I bought as an afterthought with a bit of spare cash I had in my account, have done particularly well since I bought them, with an overall profit of 144.84%. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio!

  • eToro also offer the free eToro Money app. This allows you to deposit money to your eToro account without paying any currency conversion fees, saving you up to £5 for every £1,000 you deposit. You can also use the app to withdraw funds from your eToro account instantly to your bank account. I tried this myself and was impressed with how quickly and seamlessly it worked. You can read my blog post about eToro Money here. Note that it can also serve as a cryptocurrency wallet, allowing you to send and receive crypto from any other wallet address in the world.

If you would like more information about setting up an eToro account, please click on this no-obligation website link [affiliate]. Don’t forget that you also get a free $100,000 virtual portfolio, which you can use to experiment with trading and investing strategies. I have certainly earned a lot from mine.

Moving on, as I said last time, I am no longer writing for the Mouthy Money website, as they have decided to take their content creation in-house. From a personal perspective I am obviously disappointed about this, but I had a good run with them and wish them every success going forward. You can still read all the articles I contributed to Mouthy Money over the years by visiting my profile page on the website. How long they will keep this in place I really can’t say!

I also published several posts on Pounds and Sense in March. Some are no longer relevant, but I have listed the others below.

In Beat the Postage Stamp Price Rise!, I pointed out that stamp prices are rising again on 7th April 2025. This will actually be the the SIXTH rise in the price of first class stamps in just three years. See what prices are going up, along with my recommendations for mitigating the effects of the increases.

And in From Saving to Spending – The Retirement Mindset Shift I discussed a subject that has been on my mind recently as I enter my 70th year. This is how to negotiate the mindset shirt from saving to spending in retirement, and how (hopefully) to get the balance right.

The Pros and Cons of Investing for Dividends discusses a strategy that has been growing in popularity with older investors particularly. Dividend investing offers the potential for generating income combined with capital appreciation. In this post I examine the pros and cons of a dividend investing strategy and set out a few tips and guidelines for those new to this.

Finally, in Spotlight: The Mintos P2P European Investing Platform I take a closer look at Mintos, Europe’s largest P2P investment platform. As well as the ability to generate above-average returns by investing in loans to businesses world-wide, they have added new diversification options, including bonds, ETFs and real estate. And until the end of April they have a bonus offer for anyone investing €1,500 or above on the platform. In my blog post I look at the pros and cons of investing with Mintos and provide more details about their April bonus offer.

One other thing is that we’re currently just over a week away from the end of the 2024/25 financial year. If you still haven’t used all of your 2024/25 £20,000 tax-free ISA allowance, you have just a few days left before it’s gone. It is more important than ever to use all your tax-free allowances while you can, as the government looks set to reduce some of these allowances later in the year. See my recent blog post for more information.

I’ll close with a reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as we have to call it now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out.

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. For the time being anyway, Twitter/X will remain my primary social media platform, but I will also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!


If you enjoyed this post, please link to it on your own blog or social media:
The Pros and Cons of Dividend Investing

The Pros and Cons of Investing for Dividends

Today I’m looking at investing for dividends. This is an increasingly popular strategy among investors seeking to generate passive income while potentially also growing their capital. 

Dividend stocks can provide a steady income stream, but they also come with risks and considerations. So I’ll begin by looking at the pros and cons of this approach. I will set out some hints and tips for anyone who may be interested in getting started at dividend investing. I will also mention some established UK companies that have a reputation for paying regular dividends, and some online share-dealing platforms that may be suitable for anyone applying this strategy.

Let’s begin with some of the attractions of dividend investing, though…

Pros

  1. Regular Income Stream

One of the biggest benefits of dividend investing is receiving regular cash payments, typically every quarter or six months, though occasionally monthly. This can be particularly appealing for retirees or anyone seeking passive income.

  1. Potential for Long-Term Growth

Many well-established companies that pay dividends also experience share price growth. Reinvesting dividends through a dividend reinvestment plan (DRIP) can compound returns over time.

  1. Stability in Market Downturns

Dividend-paying companies are often large, well-established firms that can weather economic downturns better than smaller, high-growth companies. Investors may find these stocks less volatile.

  1. Tax Efficiency for UK Investors

UK investors benefit from the £500 dividend allowance (as of 2024/25) before dividend income is taxed. Additionally, holding dividend stocks in an ISA (Individual Savings Account) or SIPP (Self-Invested Personal Pension) shields the income from tax altogether.

  1. Indication of a Strong Business

Companies that consistently pay and grow dividends often have strong financials, stable earnings, and a track record of profitability. This can be a sign of a well-managed company.

Cons

  1. Slower Growth Compared to High-Growth Stocks

Dividend stocks are typically in mature industries, meaning they may not offer the rapid price appreciation seen in high-growth technology or small-cap stocks.

  1. Dividends Are Not Guaranteed

A company can cut or suspend its dividend payments if it faces financial trouble, as seen during economic crises. This can lead to both income loss and share price declines.

  1. Dividend Tax for Higher Earners

If your dividend income exceeds the £500 tax-free allowance, you will pay 8.75% tax (basic rate), 33.75% (higher rate), or 39.35% (additional rate) on the excess amount. This reduces overall returns compared to capital gains, which have different tax rates.

  1. Sector Concentration Risk

Many high-dividend stocks are concentrated in certain industries, such as utilities, oil, and consumer goods. This can limit diversification and expose investors to sector-specific risks.

Tips for Beginners

If you’re new to dividend investing and want to try it, here are a few tips and guidelines to get you started…

Look for Dividend Growth, Not Just High Yields – A high yield can be a red flag if unsustainable. Instead, focus on established companies with low volatility and a history of gradually increasing dividends over time.

Diversify Your Portfolio – Don’t put all your money into one or two high-dividend stocks. Consider spreading investments across different sectors and countries.

Check the Dividend Cover Ratio – This metric (earnings per share divided by dividends per share) shows whether a company can afford its dividend. A ratio above 1.5 is generally considered safe.

Use Dividend Reinvestment – Reinvesting dividends can significantly increase long-term returns through compounding. Many brokers and online share-dealing platforms offer automatic reinvestment options.

Consider Dividend-Focused Funds – If picking individual stocks feels overwhelming, dividend ETFs or investment trusts like City of London Investment Trust (CTY) and Murray Income Trust (MUT) provide diversification and professional management. Popular dividend-focused ETFs include Vanguard High Dividend Yield Trust (VYM) and iShares Select Dividend ETF (DVY), which invests in high dividend yielding US stocks.

Examples of Strong Dividend-Paying UK Companies

Here are some UK companies known for consistent dividend payments in recent years.

Unilever (ULVR) – A consumer goods giant with a strong dividend history and steady growth.

Legal & General (LGEN) – A leading financial services company offering an attractive dividend yield.

National Grid (NG) – A stable utility company known for reliable dividend payouts.

BP (BP) – A major oil company that has historically paid strong dividends, though with some fluctuations.

Diageo (DGE) – A global leader in alcoholic beverages with a track record of dividend growth.

Online Share Dealing Platforms

Here are three UK share dealing platforms that are well-suited for dividend investors looking for relatively low costs.

  1. Interactive Investor (ii)

  • Flat-fee pricing model, which can be cost-effective for those with larger portfolios.
  • Monthly plans start from £4.99, including a Stocks & Shares ISA.
  • Offers one free trade per month, with additional trades at £5.99.
  • Free regular investing option for cost-effective reinvestment of dividends.

Visit Interactive Investor

  1. IWeb Share Dealing

  • One-off account opening fee of £100, but no annual fees after that.
  • Low-cost dealing with £5 per trade.
  • Supports shares, funds, ETFs, and investment trusts.
  • No regular investing feature, but good for long-term investors who trade occasionally.

Visit IWeb Share Dealing

  1. Trading 212

  • Commission-free trading on UK and international stocks.
  • Allows fractional share investing, which is great for reinvesting dividends.
  • Offers an AutoInvest feature for automated investing and reinvesting.
  • Offers ‘pies’ (ready-made portfolios) focused specifically on dividend investing, e.g. (Almost) Daily Dividends
  • No monthly fees for basic accounts, though there are forex fees for currency conversion.

Visit Trading 212

Each of these platforms has strengths depending on your investing style. Trading 212 (a personal favourite of mine) is great for beginners and low-cost investors; Interactive Investor suits those with larger portfolios; and IWeb is a solid, no-frills option for long-term dividend investors.

Closing Thoughts

Dividend investing can be a great way to generate passive income, but it requires careful stock selection and risk management. 

By focusing on financially strong companies with sustainable dividends and using tax-efficient accounts, investors can make the most of this strategy. 

If you’re looking for a regular income from your investments combined with the potential for long-term growth, dividend investments have the potential to play a valuable role in your investing portfolio..

  • See also this guest post by my colleague Lewys Lew on his personal approach to dividend investing. Although it was published a while ago, there are still some useful tips to be gleaned from it.

PLEASE NOTE: I am not a qualified financial adviser and nothing in this article should be construed as personal financial advice. You should always do your own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss.


If you enjoyed this post, please link to it on your own blog or social media:
From Saving to Spending - The Retirement Mindset Shift

From Saving to Spending: The Retirement Mindset Shift

Today I’m looking at a subject that may affect many readers of this blog who have recently (or not so recently) retired. It’s certainly a concern that I’ve faced myself (discussed later in the article).

For decades, many of us save diligently for retirement, carefully managing our finances to ensure what we hope will be a comfortable future. But once we finally reach retirement, a surprising challenge can emerge: shifting from a saving mentality to a spending one.

This transition can be difficult, even stressful, leading to problems such as excessive frugality, missed opportunities for enjoyment and unnecessary financial anxiety. Understanding why this happens – and how to navigate it – can help retirees make the most of their ‘golden years’.

Why Can it be Hard to Spend in Retirement?

For most of our working lives, we are conditioned to save for the future. The importance of building a pension pot, maximizing savings and preparing for the unexpected is constantly emphasized. Over time, this mindset becomes deeply ingrained, making it hard to reverse once retirement begins.

Here are some key reasons why many retirees struggle with spending…

Fear of Running Out of Money – With no regular salary coming in, retirees often worry that their savings won’t last. This fear can be worsened by rising living costs, potential healthcare expenses, and uncertainty about how long they will need their money to last.

A Lifetime Habit of Frugality – Many people have spent decades budgeting carefully, avoiding unnecessary expenses and prioritizing financial security. Suddenly being told it’s ‘okay’ to start spending feels unnatural, even reckless.

Uncertainty About the Future – Unlike a working salary, which can be replenished, a pension pot or savings account feels (and generally is) finite. Economic uncertainty, stock market fluctuations and potential care costs make it difficult for retirees to gauge how much they can safely spend.

The Problems of Excessive Frugality

While being cautious with money is clearly advisable, being overly frugal can unnecessarily reduce quality of life. Some retirees deny themselves experiences, comforts and even essentials because they feel they ‘shouldn’t’ spend. Here are some reasons why this can be problematic…

Missed Opportunities – Retirement is meant to be enjoyed, yet some people avoid holidays, hobbies or social outings because they fear dipping into their savings.

Health and Well-being Risks – Reluctance to spend on home improvements, heating or even nutritious food can have serious consequences for health and safety.

Unnecessary Financial Stress – Constantly worrying about money can take a toll on our mental well-being, even when there are sufficient funds available.

Regret Later in Life – Some realize too late that they were overly cautious and could have enjoyed their retirement more. By the time they feel comfortable spending, they may no longer be fit and healthy enough to do so.

How to Develop a Healthy Spending Mindset

Making the shift from saver to spender requires a conscious effort, but is possible with the right approach. Here are some suggested guidelines to embrace the opportunities presented by retirement whilst still maintaining financial security…

Create a Retirement Spending Plan
Just as saving required a strategy, so too does spending. Work out a realistic budget that includes essentials, discretionary spending and an emergency fund. This can provide reassurance that spending on enjoyment is both affordable and sustainable.

Think of Your Savings as a Paycheque
Rather than seeing savings as a lump sum to be preserved, treat it like an income stream. Regular withdrawals – whether from a pension or other savings – can make spending feel more structured and less daunting.

Prioritize Experiences
Research shows that spending money on experiences rather than possessions leads to greater happiness. Travel, hobbies and social activities can provide fulfilment while keeping finances under control.

Reframe Money as a Tool for Happiness
Rather than viewing savings as something to hoard, retirees can shift their perspective to see money as a resource for a fulfilling and comfortable life. This change in mindset can help ease spending anxieties.

Consider Gradual Adjustments
If spending feels uncomfortable, starting small can help. For example, try increasing your leisure budget gradually or treating yourself to one extra luxury per month. Over time, this can help you feel more at ease with enjoying your wealth.

Take Financial Advice
A professional financial adviser can help retirees feel confident about how much they can afford to spend while ensuring their money lasts. Regular reviews of pensions and investments can provide reassurance (see My Experience, below).

Give Yourself Permission to Enjoy the Rewards of Saving
Remember why you saved in the first place – to have security and enjoyment in later life. A balanced approach ensures financial stability while allowing for a fulfilling retirement.

My Experience

I have been officially retired for several years now. I still do a bit of freelance work (and run this blog) but my freelance income has tapered off. I am fortunate to have some savings and investments, the bulk of which I acquired through inheritances (though some from money I saved over the years).

As regular readers will know, although I’m a money blogger with a particular interest in such matters, I do have a personal financial adviser myself (I talked about this a while ago in this article). His name is Mike, and in my recent annual review he gently suggested that I could afford to withdraw a bit more from my investments. Essentially, he told me that I wasn’t getting any younger (I’m 70 this year) and there would be no benefit to dying with a lot of money left in my account. In some ways I found this advice encouraging, in others a bit depressing!

I do accept the gist of Mike’s advice, though. Even though I’m basically in good health, none of us knows what the future may hold. So I have promised Mike that I will think about what he has said and consider whether to draw more from my investments, while still leaving enough to cover my possible health and care needs in future. Of course, without a functioning crystal ball this isn’t an easy task, especially with the very high cost of care in the UK. But it’s important to take a balanced view and ensure you aren’t depriving yourself unnecessarily now whilst still retaining sufficient funds in case circumstances change in future.

Closing Thoughts

As I said at the start, the shift from saving to spending can be one of the biggest psychological adjustments in retirement.

Retirement is meant to be enjoyed, but many retirees find themselves trapped in a frugality mindset that stops them fully embracing the opportunities presented by this stage of life.

While financial prudence is important, excessive caution can lead to missed opportunities and unnecessary sacrifice. By shifting perspectives, planning carefully and embracing the idea that money is there to be used and enjoyed, retirees can – hopefully – strike a balance between financial security and enjoying their hard-earned wealth.

As ever, I’d love to hear any views (or tips) from readers about walking the tightrope between preserving your savings and making the most of life while you can.


If you enjoyed this post, please link to it on your own blog or social media:
My Investments Update - March 2025

My Investments Update – March 2025

Here is my latest monthly update about my investments. You can read my February 2025 Investments Update here if you like.

I’ll begin as usual with my Nutmeg Stocks and Shares ISA. This is the largest investment I hold other than my Bestinvest SIPP (personal pension).

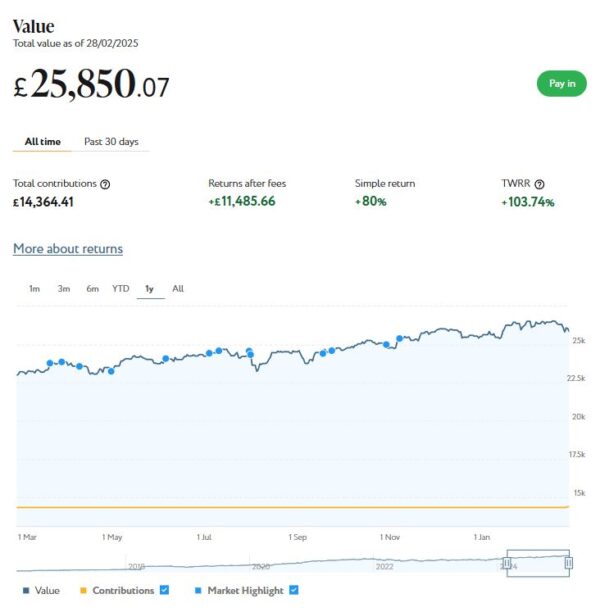
As the screenshot below for the last twelve months shows, my main Nutmeg portfolio is currently valued at £25,850. Last month it stood at £26,528, so that is a decrease of £678.

Nutmeg main port March 25

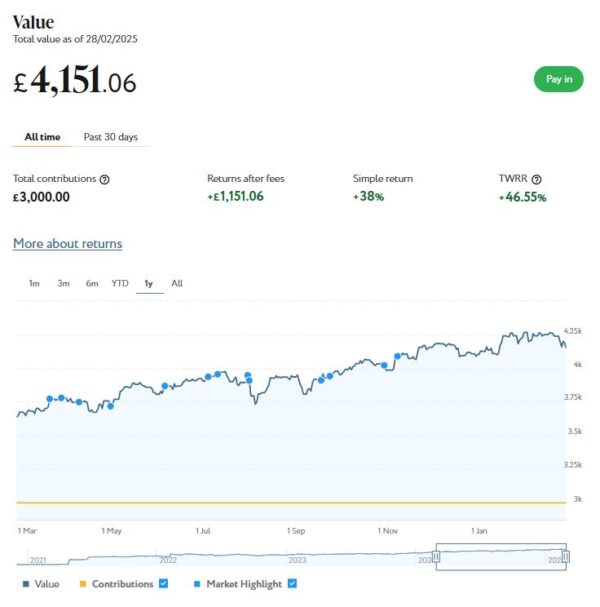
Apart from my main portfolio, I also have a second, smaller pot using Nutmeg’s Smart Alpha option. This is now worth £4,151 compared with £4,267 a month ago, a fall of £116. Here is a screen capture showing performance over the last twelve months.

Nutmeg Smart Alpha March 25

Finally, at the start of December 2023 I invested £500 in one of Nutmeg’s new thematic portfolios (Resource Transformation). In March I also invested a further £200 from referral bonuses. As you can see from the screen capture below, this portfolio is now worth £803 (rounded up) compared with £832 last month, a fall of £29.

Nutmeg Thematic Mar 25

As you can see, February has been a disappointing month for my Nutmeg investments. Overall I am down by £823. This is mostly due to a general decrease in share values in the second half of the month.

Nonetheless, the value of my Nutmeg investments is still up £390 since the start of the year. And their value has increased by £3,441 or 12.67% in the twelve months since the end of February 2024.

You can read my full Nutmeg review here. If you are looking for a home for your annual ISA allowance, based on my overall experience over the last eight years, they are certainly worth considering. They offer self-invested personal pensions (SIPPs), Lifetime ISAs and Junior ISAs as well.

Moving on, I also have investments with P2P property investment platform Assetz Exchange. As discussed in this recent post, the company recently rebranded as Housemartin.

My investments with Housemartin continue to generate steady returns. Housemartin focuses on lower-risk properties (e.g. sheltered housing). I put an initial £100 into this in mid-February 2021 and another £400 in April. In June 2021 I added another £500, bringing my total investment up to £1,000.

Since I opened my account, my HM portfolio has generated a respectable £235.31 in revenue from rental income. Capital growth has slowed, though, in line with UK property values generally.

At the time of writing, 17 of ‘my’ properties are showing gains, 1 is breaking even, and the remaining 19 are showing losses. My portfolio of 37 properties is currently showing a net decrease in value of £50.24, meaning that overall (rental income minus capital value decrease) I am up by £185.07. That’s still a decent return on my £1,000 and does illustrate the value of P2P property investments for diversifying your portfolio. And it doesn’t hurt that with Housemartin most projects are socially beneficial as well.

The overall fall in capital value of my Housemartin investments is obviously a little disappointing. But it’s important to remember that until/unless I choose to sell the investments in question, it is largely theoretical, based on the latest price at which shares in the property concerned have changed hands. The rental income, on the other hand, is real money (which in my case I’ve reinvested in other HM projects to further diversify my portfolio).

To control risk with all my property crowdfunding investments nowadays, I invest relatively modest amounts in individual projects. This is a particular attraction of Housemartin as far as i am concerned. You can actually invest from as little as £1 per property if you really want to proceed cautiously.

  • As I noted in this blog post, Housemartin is particularly good if you want to compound your returns by reinvesting rental income. This effectively boosts the interest rate you are receiving. Personally, once I have accrued a minimum of £10 in rental payments, I reinvest this money in either a new HM project or one I have already invested in (thus increasing my holding). Over time, even if I don’t invest any more capital, this will ensure my investment with Housemartin grows at an accelerating rate and becomes more diversified as well.

My investment on Housemartin is in the form of an IFISA so there won’t be any tax to pay on profits, dividends or capital gains. I’ve been impressed by my experiences with Housemartin and the returns generated so far, and intend to continue investing with them. You can read my full review of Assetz Exchange/Housemartin here. You can also sign up for an account directly via this link [affiliate]. Bear in mind that, as from the current financial year (2024/25), you can open more than one IFISA per year.

In 2022 I set up an account with investment and trading platform eToro, using their popular ‘copy trader’ facility. I chose to invest $500 (then about £412) copying an experienced eToro trader called Aukie2008 (real name Mike Moest).

In January 2023 I added to this with another $500 investment in one of their thematic portfolios, Oil Worldwide. I also invested a small amount I had left over in Tesla shares.

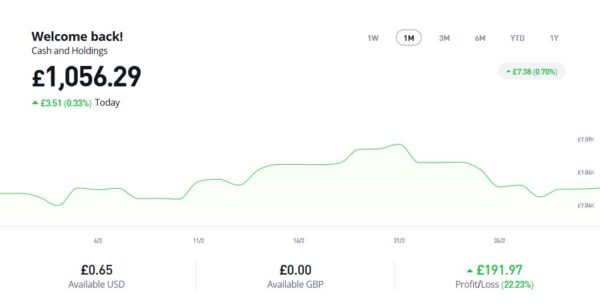
As you can see from the screen captures below, my original investment (total value £888.36 in pounds sterling) is today worth £1,056.29, an overall increase of £167.93 or 18.90%.

  • Note: eToro now displays the value of investments in your native currency, although you can change this if you wish.

eToro main March 25

eToro port Mar 25

You can read my full review of eToro here. You may also like to check out my more in-depth look at eToro copy trading. I also discussed thematic investing with eToro using Smart Portfolios in this recent post. The latter also reveals why I took the somewhat contrarian step of choosing the oil industry for my first thematic investment with them.

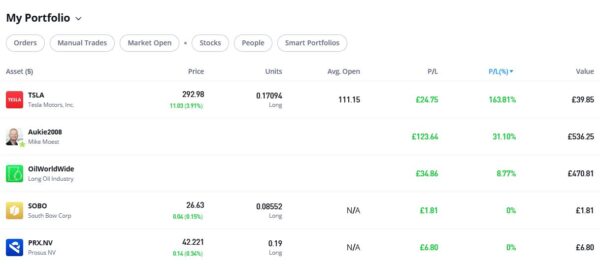
As you can see, my Oil WorldWide investment is showing a profit of 8.77%. That’s a small but nonetheless welcome improvement since the portfolio was rebalanced by eToro. The investment team at eToro periodically rebalance all smart portfolios to ensure that the mix of investments remains aligned with the portfolio’s goals, and to take advantage of any new opportunities that may present themselves.

My copy trading investment with Aukie2008 has been doing better, with an overall 31.18% profit. To be fair, I have held the latter investment a bit longer.

My Tesla shares, which I bought as an afterthought with a bit of spare cash I had in my account, have done particularly well since I bought them, with an overall profit of 163.81%. If only I had put a bit more money into this!

You might also notice that I have small holdings in Prosus NV, a Dutch internet group, and South Bow, a Canadian energy infrastructure company. To be honest I don’t understand how I acquired these, but I assume they are some sort of bonus I was awarded. In any event, I am happy to have them in my portfolio!

  • eToro also offer the free eToro Money app. This allows you to deposit money to your eToro account without paying any currency conversion fees, saving you up to £5 for every £1,000 you deposit. You can also use the app to withdraw funds from your eToro account instantly to your bank account. I tried this myself and was impressed with how quickly and seamlessly it worked. You can read my blog post about eToro Money here. Note that it can also serve as a cryptocurrency wallet, allowing you to send and receive crypto from any other wallet address in the world.

If you would like more information about setting up an eToro account, please click on this no-obligation website link [affiliate]. Don’t forget that you also get a free $100,000 virtual portfolio, which you can use to experiment with trading and investing strategies. I have certainly earned a lot from mine.

I had six more articles published in February on the excellent Mouthy Money website. The first is titled Travelling to Europe This Year? Here’s Why You Need a GHIC Card. If you’re unfamiliar with the GHIC or how it differs from the previous European Health Insurance Card (EHIC), this article reveals everything you need to know, from how to apply to why it’s so important for your travels.

Also in February Mouthy Money published How to Check Your Tax Code and Correct it if Necessary. Understanding your tax code and ensuring its accuracy can prevent you from overpaying (or underpaying) tax. In this article I explained everything you need in order to check and understand the code you have been allocated.

And in Make Extra Money Renting a Room I turned the spotlight on this traditional (but none the worse for that) method for making some extra money. If your circumstances allow it, letting a room in your home can be a great way of generating a sideline income. It will provide a regular, ongoing income stream, which could prove a lifeline in these financially challenging times. And you can choose between getting a full-time lodger or offering short-term lets. Better still, under the Rent a Room Scheme you can make up to £7,500 a year this way entirely tax free!

In What is the Trading Allowance and How Can You Profit From It? I discussed this valuable allowance for UK residents looking to earn extra income from trading or side hustles. Even if you have a full-time job already, under the Trading Allowance you can earn up to £1,000 a year without having to declare that income to the taxman or paying tax on it. Read my article for the full lowdown!

And in Could You Benefit From the Help to Save Scheme? I discussed this lesser-known government initiative which, if you’re eligible, can give your finances a valuable boost. The Help to Save scheme aims to help people on lower incomes build up their savings. Offering generous tax-free bonuses, Help to Save can provide significant benefits for qualifying individuals.

Finally, in Could a Smart Thermostat Save You Money?, I revealed how these clever devices can save you money on your energy bills. I recently had one fitted myself. In this article I reveal which I chose (and why) and share some tips based on my own experiences. My heating engineer Dave, who installed it for me, also gets an honourable mention!

As I’ve said before, Mouthy Money is a great resource for anyone interested in money-making and money-saving. From the range of articles published in February, I particularly enjoyed Where to Find the Best Money-Saving Resources in 2025 by regular MM contributor Shoestring Jane. Jane writes mainly about money saving and frugal living. You can see all of her articles for Mouthy Money via this web page.

  • The not-so-good news about Mouthy Money is that due to a change in their business strategy they will no longer be commissioning external content writers such as me and Jane. From a personal perspective I am obviously disappointed about this, but I have had a good run with them and wish them every success going forward. I will continue to follow Mouthy Money with interest and recommend PAS readers do the same. I am also available for other writing work in the personal finance sphere if anyone else should need me!

I also published several posts on Pounds and Sense in February. Some are no longer relevant, but I have listed the others below.

Debunking Common Myths About Over-50 Life Insurance is a guest post on behalf of my friends at British Seniors Insurance Services. It sets out seven common myths about life insurance for over-50s, including ‘I’m too old to get life insurance’ and ‘Life insurance for over-50s is too expensive’, and explains why these commonly-held beliefs are incorrect.

Marriage in Later Life – A Guide to the Financial and Legal Implications is another guest post, this time by my colleagues at HCR Law. In this eye-opening article, their family law specialist, Victoria Fellows, sets out some important considerations to take into account if you are thinking of marrying (or remarrying) in later life.

In How to Make Money From Stoozing, I discuss this method of making extra income by taking advantage of interest-free offer periods on credit cards. If you are well organized you can make hundreds of pounds by doing this, but there are certain pitfalls to avoid. My article sets out everything you need to know and shares some useful resources.

Don’t Miss Out! Use Your £20,000 ISA Allowance Before It’s Too Late is a reminder that the current tax year ends on 5 April 2025 – and if you don’t use your 2024/25 tax-free ISA allowance before that date, it will be gone forever. In my article I explain the main types of ISA and reveal the ones I invest in myself. I also reveal why using your ISA allowance may be especially important in the current tax year if certain rumours are to be believed.

Finally, in Get Your Will Written Free of Charge in March, I discuss Free Wills Month, which actually starts today (3rd March 2025). This event brings together a group of well-respected charities to offer members of the public aged 55 and over the chance to have their wills written (or updated) free using participating solicitors across the UK. If you don’t currently have a will, this no-obligation opportunity is well worth checking out.

I’ll close with a reminder that you can also follow Pounds and Sense on Facebook or Twitter (or X as we have to call it now). Twitter/X is my number one social media platform and I post regularly there. I share the latest news and information on financial matters, and other things that interest, amuse or concern me. So if you aren’t following my PAS account on Twitter/X, you are definitely missing out.

  • I am also on the BlueSky social media network under the username poundsandsense.bsky.social. For the time being anyway, Twitter/X will remain my primary social media platform, but I will also post details of my latest blog posts, third-party articles and other financial news and resources on BlueSky for those who prefer to follow me there.

As always, if you have any comments or questions, feel free to leave them below. I am always delighted to hear from PAS readers 🙂

Disclaimer: I am not a qualified financial adviser and nothing in this blog post should be construed as personal financial advice. Everyone should do their own ‘due diligence’ before investing and seek professional advice if in any doubt how best to proceed. All investing carries a risk of loss. 

Note also that posts on PAS may include affiliate links. If you click through and perform a qualifying transaction, I may receive a commission for introducing you. This will not affect the product or service you receive or the terms you are offered, but it does help support me in publishing PAS and paying my bills. Thank you!

If you enjoyed this post, please link to it on your own blog or social media:
How to Make Money from Stoozing

How to Make Money From Stoozing

Having fallen out of favour for a while due to a lack of suitable opportunities, the sideline-earning system of stoozing is back in the spotlight again!

Stoozing is a financial strategy that allows individuals to profit by leveraging 0% interest credit card offers. By using the interest-free periods, you can earn interest on borrowed funds without incurring additional costs.

Here’s a guide to effectively implementing a stoozing strategy…

1. Understanding Stoozing

Stoozing involves borrowing money through a credit card offering a 0% interest period and depositing that money into a high-interest savings account. The goal is to earn interest on the borrowed funds and repay the credit card balance before the interest-free period ends. This method requires careful planning and discipline to ensure profitability.

2. Steps to Implement Stoozing

Select a Suitable 0% Interest Credit Card

Begin by researching credit cards that offer a 0% interest period on purchases or balance transfers. Opt for cards with the longest interest-free durations to maximize potential gains. Ensure you understand any associated fees, such as balance transfer fees, which could impact your overall profit. A useful resource for tracking down cards with 0% interest-free offers can be found on the popular MoneySavingExpert website.

Use the Credit Card for Everyday Purchases

Instead of using your debit card or cash, utilize the 0% interest credit card for daily expenses. This approach allows your regular income to remain in your bank account. This money can then be transferred to a high-interest savings account. Note that you should never withdraw cash directly from your credit card as you will be charged interest on this and it may also adversely affect your credit score (see below).

Deposit Funds into a High-Interest Savings Account

Transfer the money that would have been used for purchases into a high-interest savings account. This strategy enables you to earn interest on funds that would otherwise have been spent. Regularly monitor interest rates using a platform such as MoneySuperMarket to ensure you’re getting the best possible return on your savings.

Make Minimum Monthly Payments

It’s essential to make at least the minimum monthly payments on your credit card to maintain the 0% interest offer. Setting up a direct debit can help prevent missed payments, which could result in losing the interest-free benefit.

Repay the Full Balance Before the 0% Period Ends

Before the end of the 0% interest period, ensure you repay the entire credit card balance using the funds in your savings account. The difference between the interest earned and any fees paid represents your profit.

3. Example of Potential Earnings

Let’s say you obtain a 0% interest credit card with a 24-month interest-free period and a credit limit of £5,000. You deposit the full £5,000 into a high-interest savings account offering an annual interest rate of 5%.

  • Year 1 Interest: £5,000 x 5% = £250
  • Year 2 Interest: £5,000 x 5% = £250
  • Total Interest Earned Over 2 Years: £500

Assuming there are no fees and you meet all minimum payments on time, your profit from stoozing would be £500, simply by leveraging the 0% interest period.

4. Calculating Potential Profits

To assess the potential gains from stoozing, you can use online calculators designed for this purpose. These allow you to enter details such as the balance to be transferred, the introductory period, balance transfer fees, and minimum monthly payments to estimate your profit. One such calculator is available at stoozing.com.

5. Risks and Considerations

While stoozing can be profitable, it’s important to be aware of potential risks:

  • Discipline Required: Failure to make minimum payments or repay the balance before the 0% period ends can lead to interest charges that outweigh your earnings.
  • Credit Score Impact: Applying for multiple credit cards can affect your credit score. It’s advisable to check your credit report before proceeding. And it may be best to avoid stoozing if you plan to apply for a mortgage or business loan in the near future.
  • Changing Interest Rates: Savings account interest rates can vary, potentially reducing your anticipated profits.
  • Fees: Be mindful of any fees associated with the credit card or savings account, as they can erode your gains.

6. Closing Thoughts

Stoozing offers a method to earn additional income by strategically using 0% interest credit card offers and high-interest savings accounts.

Success in stoozing hinges on careful planning, disciplined financial management, and a thorough understanding of the terms and conditions associated with the financial products involved. Always ensure that the interest earned exceeds any fees incurred to achieve a net profit.

As always, if you have any comments or questions about this post, please do leave them below.


If you enjoyed this post, please link to it on your own blog or social media: